U.S. Diesel Price Hits Another Record Above $6.20 as Fresh Hormuz Attack Deepens Supply Fears
The national diesel average climbed above $6.20 a gallon Sunday, extending a record run as a new vessel strike in the Strait of Hormuz added to supply concerns.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy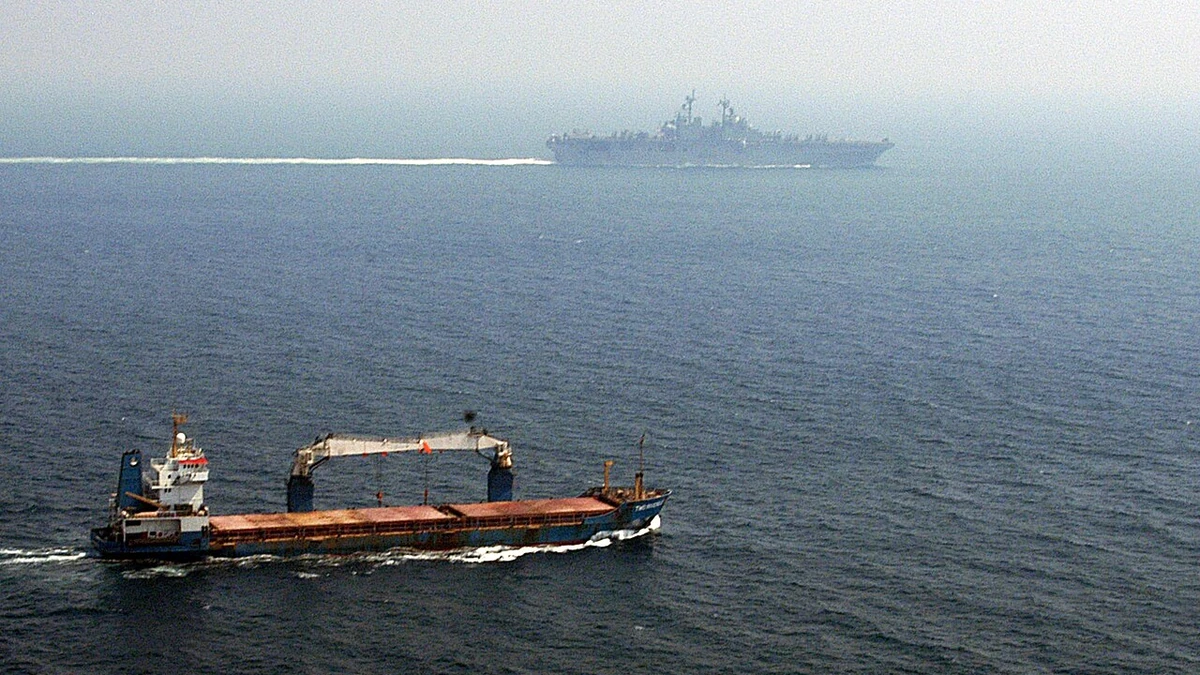
The U.S. national average diesel price moved above $6.20 a gallon on Sunday, Reuters reported, extending a record-setting run just as another vessel attack in the Strait of Hormuz renewed concern about the security of a route that remains central to global oil trade. The latest jump adds pressure to freight, farming and other diesel-intensive parts of the economy at a time when fuel markets already have little room for another supply shock.
Primary price data already showed how quickly the move had developed. AAA’s latest published national snapshot, dated September 12, put diesel at $6.1602 a gallon, up from $6.0556 a day earlier, $5.8819 a week earlier and $3.7029 a year earlier. AAA lists the September 12 reading as the highest recorded national diesel average in its series. Reuters reported Sunday that newer market data had pushed the average above $6.20.
The escalation came as the United Kingdom Maritime Trade Operations center issued Warning 134-26 after receiving a report that a vessel transiting the Strait of Hormuz had been struck by an unknown projectile. Early information did not establish who was responsible, and the condition of the crew, the extent of damage and any environmental impact were not immediately clear. The limited facts matter because the incident adds a fresh security risk without yet establishing the scale of any physical supply loss.
Diesel’s record has accelerated in a matter of days
The current level is not simply a continuation of normal seasonal movement. AAA’s national diesel average rose by more than 10 cents between September 11 and September 12 alone, and by roughly 28 cents from a week earlier. Compared with a year ago, the increase is about $2.46 a gallon, or roughly two-thirds. That kind of move feeds quickly into operating costs for businesses that cannot readily substitute away from diesel.
Diesel has an unusually broad economic footprint. Heavy trucks, delivery fleets, construction equipment and much of the agricultural machinery used during harvest season depend on distillate fuel. Higher pump prices do not translate mechanically into an identical increase in consumer prices, but they raise transportation and production costs across supply chains. The effect can show up with a lag as carriers adjust fuel surcharges and businesses decide how much of the added expense they can absorb.
U.S. Energy Information Administration data underline how exceptional the recent move has been. Its weekly retail diesel series averaged $5.967 a gallon for the week ending September 7, already well above late-August levels. In its September outlook, EIA raised its 2026 average retail diesel forecast to $5.07 a gallon and projected a $5.55 average for the fourth quarter. Those forecasts were completed using assumptions finalized on September 3, before the newest rise in retail prices and before Sunday’s reported Hormuz strike.
Hormuz remains the central supply vulnerability
The Strait of Hormuz has been one of the main sources of uncertainty in oil markets throughout the conflict. EIA’s latest energy-security analysis estimates that crude oil and petroleum liquids moving through the strait averaged 4.9 million barrels per day in the second quarter of 2026. That compares with 21.6 million barrels per day in the fourth quarter of 2025, before the conflict sharply disrupted the waterway.
The same EIA analysis shows how difficult it is to replace those volumes quickly. Producers can redirect some barrels through pipelines and alternative ports, but those routes have finite capacity and can add time and cost. The agency’s September outlook assumed that flows through Hormuz would gradually increase as the year progressed. A new attack does not by itself prove that those flows will fall again, but it raises the risk that shipowners, insurers and governments will remain cautious about a route that was already operating far below its pre-conflict level.
U.S. maritime authorities were already treating the region as dangerous. The Maritime Administration’s active advisory covering the Persian Gulf, Strait of Hormuz and Gulf of Oman says commercial vessels face a high risk of attack and notes threats that include missiles, armed unmanned aerial vehicles and armed unmanned surface vessels. Sunday’s incident fits the broader security problem even though responsibility for the reported projectile strike had not been established.
That distinction is important for the diesel story. A security incident can lift risk premiums and alter shipping behavior even before there is evidence of a large new loss of crude or refined products. At the same time, attributing the entire U.S. diesel increase to one attack would overstate what is known. The market has been dealing with months of Middle East disruption, tight distillate supply and other global refinery and export constraints. The Hormuz strike adds to those pressures rather than creating them from scratch.
U.S. distillate inventories offer only a limited cushion
Domestic stocks have improved from late-August lows, but they remain a key constraint. EIA reported total U.S. distillate fuel oil inventories of 106.274 million barrels for the week ending September 4, up from 104.187 million barrels a week earlier. That increase provided some breathing room, yet the agency’s September forecast still expects inventories to fall below 100 million barrels in October for the first time since 2003 and to remain below the five-year low through the first quarter of 2027.
That outlook helps explain why diesel can react so sharply to new supply threats. When inventories are comfortable, refiners, distributors and end users have more ability to absorb interruptions. When stocks are thin and global trade routes are unreliable, a new shipping incident can affect expectations well before physical shortages appear at U.S. filling stations. Refining margins for distillates also tend to strengthen when buyers compete for a smaller pool of available barrels.
There is still an important difference between a price record and an outright shortage. Fuel remains available across the United States, and the latest weekly inventory data do not show stocks collapsing from one week to the next. The immediate issue is cost and the risk that additional disruptions keep prices elevated. EIA’s outlook anticipates some recovery in Middle East production and trade as Hormuz flows improve, but the agency also says it expects global inventories to remain under pressure through the rest of 2026.
For U.S. consumers and businesses, the next useful signals will be the next AAA national price update, EIA’s weekly inventory data and any confirmed change in shipping conditions through Hormuz. If traffic continues to recover despite Sunday’s incident, some of the current risk premium could ease. If attacks begin to interrupt more voyages or alternative export routes, the record diesel price could become part of a longer period of unusually high transportation costs rather than a short-lived spike.
More News
Latest News
View all news- First Trust’s Palantir Target-Income ETF Registration Takes Effect
- Saudi Stocks Post Sharpest Drop Since April as Energy-Supply Risks Escalate
- South Korea Broadens Espionage Law to Foreign States as Seoul Targets Chip and AI Technology Leaks
- New Hampshire Raises Housing Finance Authority Bond Caps to $1 Billion
- Trump Says Iran Probably Behind Saudi Pipeline Attack as Energy-Route Risk Deepens