
Michael Dell’s DFO and Sequence Agree to Take Baldwin Group Private for $7.7 Billion
Baldwin shareholders will receive $32.50 a share in cash, while the $7.7 billion enterprise value includes about $3.1 billion of net debt.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy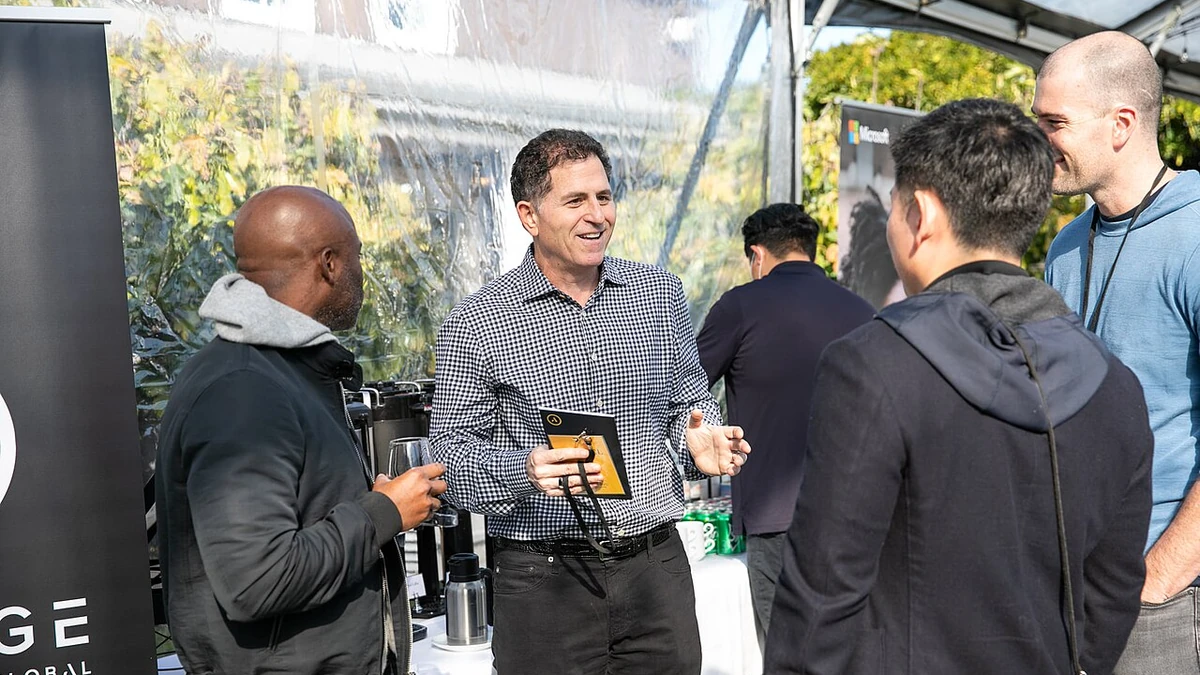
The Baldwin Group has agreed to be acquired by an entity formed by Sequence Holdings and DFO Management, Michael Dell’s family investment office, in an all-cash take-private deal with an enterprise value of about $7.7 billion. Baldwin shareholders will receive $32.50 a share in cash, an 88% premium to the company’s June 17 closing price, the last unaffected trading day before reports emerged that the insurance broker was exploring a sale.
The headline value includes a large debt component. Baldwin said the acquisition implies an equity purchase price of about $4.6 billion and includes roughly $3.1 billion of net debt that will be assumed or refinanced. On the company’s figures, the $7.7 billion enterprise value is about 20 times trailing-12-month adjusted EBITDA of approximately $396 million.
Baldwin’s board unanimously approved the agreement after a unanimous recommendation from a special committee of independent, disinterested directors. The company’s investor-relations release page is the primary company source for the announcement. The acquisition is expected to close in the first quarter of 2027, subject to shareholder approval, required regulatory clearances and other customary conditions. Baldwin said the closing is not subject to a financing condition.
The $7.7 billion figure is enterprise value, not the cash paid for shares
The distinction between enterprise value and equity purchase price is important in this deal. The $32.50-a-share consideration represents what holders of Baldwin common stock will receive, while the larger $7.7 billion figure also reflects debt that the buyer group expects to assume or refinance. Treating the enterprise value as though it were the amount being paid directly to shareholders would overstate the cash equity consideration by roughly $3.1 billion.
The 88% premium cited by Baldwin uses the June 17 unaffected closing price, not the share price immediately before Monday’s announcement. That reference point predates reports that the company was considering a take-private, which had already pushed the stock closer to the eventual offer price. The premium therefore measures the value uplift from the pre-sale-speculation level rather than the final trading session before the agreement was announced.
When the acquisition closes, Baldwin will become a privately held company and its common stock will no longer trade on Nasdaq. Eligible employees who already own Baldwin equity will be allowed to roll over a portion of their holdings and retain what the company described as a significant minority stake alongside Sequence and DFO. That structure gives some employees continuing exposure to the business after public shareholders are cashed out.
The board process also matters because the sale involves a full change in public ownership. Baldwin said a special committee made up of independent and disinterested directors evaluated the proposal with its own legal and financial advisers before recommending approval. The shareholder vote and regulatory reviews are the main remaining external gates before the expected first-quarter closing.
Sequence and DFO are pairing long-duration capital with a technology agenda
The buyer group is unusual compared with a traditional private-equity sponsor structure. DFO says it is the family investment office of Dell Technologies founder, chairman and CEO Michael Dell and his family, with roots in MSD Capital, which was established in 1998 and restructured as DFO at the end of 2022. Its mandate spans a wide range of asset classes rather than a single buyout fund with a fixed investment horizon.
Sequence, meanwhile, describes itself as a permanent holding company focused on established businesses in the service economy. On its official company site, Sequence says it brings capital, engineering and operating expertise to acquired companies and deploys its Atlas technology platform across the businesses it owns. That model helps explain why technology and artificial intelligence feature prominently in the rationale for the Baldwin acquisition.
Baldwin had already been moving in that direction before the sale process. In May, the insurance group announced an expanded enterprise relationship with Anthropic to deploy Claude across the firm. Baldwin said the rollout was intended to help advisers and operating teams analyze risk, synthesize client information, support insurance recommendations and automate more complex workflows. The company also said it planned to extend the technology toward more advanced agentic workflows over time.
The take-private therefore does not create Baldwin’s AI strategy from scratch. It puts an existing technology program under owners that are explicitly emphasizing longer-duration capital and software-driven operating changes. Michael Dell said in the acquisition announcement that Baldwin had built a data and platform advantage over 15 years. Sequence’s own operating model similarly centers on applying engineering and software to established service businesses.
That does not guarantee that spending on AI will improve margins or growth. Insurance brokerage remains dependent on client relationships, producer productivity, pricing conditions and acquisition execution, and technology investments can take time to translate into financial returns. The ownership change does, however, remove the quarterly reporting cycle and public-market share-price pressure that can make large, multi-year operating investments harder to manage.
Baldwin enters the deal after a sharp expansion in reported revenue
The acquisition comes after a period of rapid reported growth at Baldwin, helped by acquisitions and partnerships. In the second quarter of 2026, the company reported revenue of $492.9 million, up 30% from a year earlier. Adjusted EBITDA increased 37% to $116.7 million, while adjusted diluted earnings per share rose 14% to $0.48.
The GAAP picture was less flattering. Baldwin recorded a second-quarter net loss of $56.0 million, or a diluted loss of $0.42 per share, even as adjusted EBITDA margins expanded to 23.7% from 22.6% a year earlier. For the first six months of 2026, revenue reached about $1.03 billion and adjusted EBITDA was $254.0 million. The company also reported $184.5 million of cash and cash equivalents at June 30 and $259.4 million of available borrowing capacity under its revolving credit facility.
One important driver of Baldwin’s larger scale was its January 2026 merger with CAC Group, which expanded the company’s specialty and middle-market insurance brokerage operations. Baldwin said CAC generated $94 million of revenue in the second quarter, up 23% from the comparable period. That acquisition, along with other partnerships, helped lift reported revenue even though Baldwin’s companywide organic revenue growth was 2% for the quarter.
The agreed sale price suggests DFO and Sequence are willing to pay for that broader platform while also taking on substantial leverage. Baldwin’s own deal announcement pegs the enterprise value at roughly 20 times trailing adjusted EBITDA, a valuation that leaves the new owners with a meaningful execution burden if they want technology investment, operating changes and growth to justify the purchase price.
The next concrete steps are the Baldwin shareholder vote and regulatory approvals. If those conditions are satisfied on schedule, the company expects the acquisition to close in the first quarter of 2027, after which Baldwin will cease to be publicly listed and the employee rollover holders will remain minority owners alongside Sequence and DFO.
More from Investing
Latest News
View all news- Corteva Board Gives Final Approval for Vylor Separation and October 1 Distribution
- Rainier Acquisition Holders Can Begin Separating SPAC Units Into Shares and Warrants
- NUBURU Returns to NYSE American After July Trading Suspension
- Onconetix Extends Up to $5 Million Bridge Financing to Realbotix Ahead of Acquisition
- BioNTech and OncoC4 Report Survival Gain in Phase 3 Lung Cancer Trial
