
Bamboo Insurance Seeks Up to $3.24 Billion Valuation in U.S. IPO
Selling shareholders plan to offer 35 million shares at $18 to $20 each, and Bamboo itself will not receive proceeds from the stock sale.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy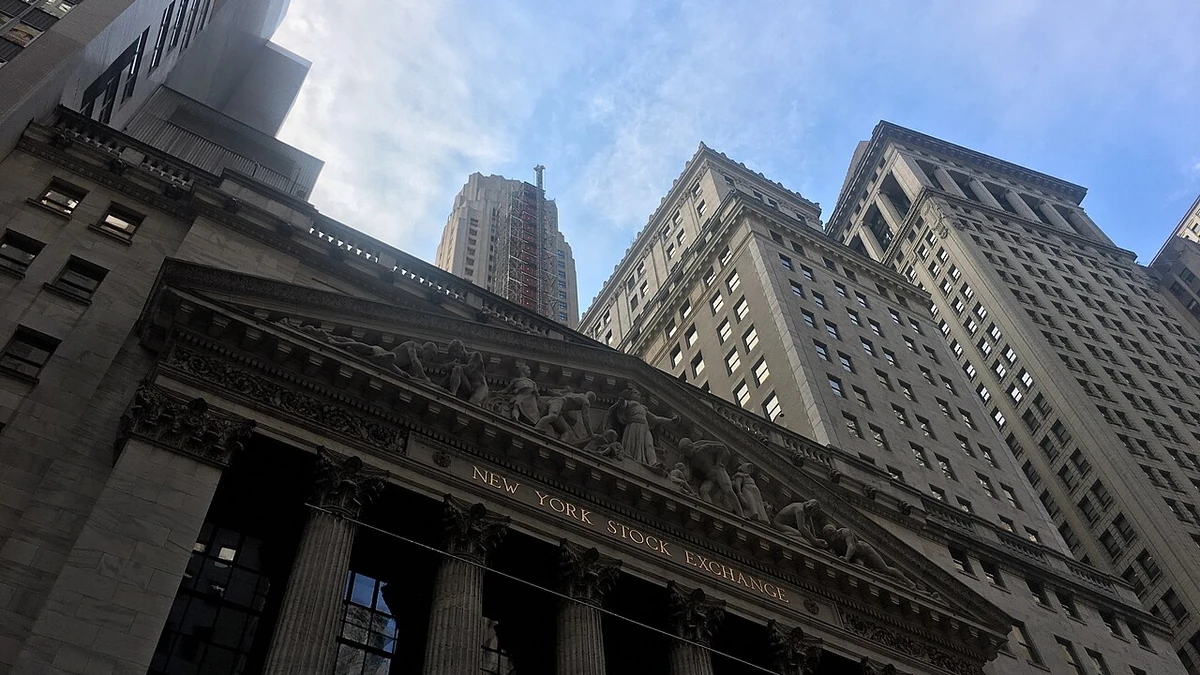
Bamboo Insurance Services is seeking a fully diluted valuation of as much as $3.24 billion in its U.S. initial public offering, with existing shareholders planning to sell 35 million Class A shares at $18 to $20 each. Reuters reported the terms Monday, citing a new filing. At the top of the proposed range, the base offering would amount to $700 million before underwriting discounts and expenses.
The structure is important because Bamboo itself is not selling shares for its own account. Its registration statement filed with the Securities and Exchange Commission says the selling stockholders are offering the Class A shares and that the company will not receive proceeds from those sales. Bamboo has applied to list on the New York Stock Exchange under the ticker BMB, subject to approval of the listing application.
Selling shareholders, not Bamboo, are raising the cash
The proposed $3.24 billion figure is a fully diluted valuation, while the $700 million figure represents the gross value of the 35 million-share base offering if it is priced at $20. Those numbers answer different questions. The valuation describes the implied equity value of the company on a diluted share basis, while the offering size measures the stock that existing holders are seeking to sell to public investors.
That also means the IPO is not designed to put the base offering proceeds onto Bamboo’s balance sheet. The company said in its prospectus that it will receive no proceeds from the selling stockholders’ shares. For investors, the offering is therefore primarily a change in ownership liquidity and public-market access rather than a direct capital raise for the operating business.
Bamboo Insurance Services was formed in Delaware in March 2026 as the issuer for the planned public listing. The operating business has historically been conducted through Miramar Holdco and subsidiaries including Bamboo Ide8 Insurance Services. After the reorganization tied to the IPO, Bamboo Insurance Services is expected to serve as the sole manager of Miramar Holdco and hold a majority economic interest, while other owners retain interests through the structure described in the prospectus.
The filing also outlines two classes of common stock. Class A shares, including those being offered to the public, carry one vote per share. Class B shares also carry one vote per share but have no economic rights at the public-company level and are intended to be held by continuing equity owners. The arrangement lets those owners retain voting participation alongside their underlying economic interests in Miramar Holdco.
Growth and profitability are central to the IPO pitch
Bamboo describes itself as an underwriting-first, capital-light homeowners insurance managing general underwriter, or MGU. Rather than functioning like a traditional carrier that keeps most insurance risk on its own balance sheet, Bamboo originates and services policies, handles functions such as underwriting, policy administration and claims, and works with outside capacity providers that assume most of the insurance risk. Bamboo earns revenue largely from commissions and policyholder fees.
The prospectus shows rapid recent growth. Revenue reached $173 million in the first six months of 2026, up from $124 million in the comparable 2025 period. Net income was $14 million, down from $24 million a year earlier, while the company’s non-GAAP adjusted EBITDA rose to $77.2 million from $42.5 million. Bamboo reported an adjusted EBITDA margin of 45% for the 2026 half-year, compared with 34% in the prior-year period.
Premium volume has also expanded. Bamboo reported $451.4 million of managed premium for the first six months of 2026, up from $337.8 million a year earlier. Managed premium for the 12 months ended June 30 was $879.3 million, and policies in force reached 401,787 on that trailing basis. Managed premium is a company operating metric representing the premium placed through its platform, not revenue retained by Bamboo.
California remains the core market. Bamboo says it had about 4% of the state’s homeowners insurance premium at the end of 2025 after expanding during a period when several established insurers reduced their appetite for new business. The company entered Texas in September 2025 and has positioned geographic expansion as a future growth avenue. As of June 30, 2026, it reported relationships with seven program partners, 60 global reinsurers and 28 institutional investors participating in its capacity strategies.
That growth comes with insurance-market risks that public investors will have to price. Bamboo’s prospectus warns that catastrophe exposure, changes in reinsurance availability, competition, regulatory requirements, housing-market conditions and a shift toward a softer property-insurance market can affect volumes and margins. The company also depends on capacity partners to support the policies it places, even though it has broadened that provider base over time.
CVC ownership frames the public-market debut
The IPO follows a major ownership change less than a year ago. White Mountains Insurance Group agreed in October 2025 to sell a controlling interest in Bamboo to funds advised by CVC Capital Partners, and the sale closed in December. White Mountains said the sale valued Bamboo at $1.75 billion and left it with an approximately 15% fully diluted equity stake after closing.
The earlier $1.75 billion figure and the proposed $3.24 billion IPO valuation should not be treated as a simple like-for-like appreciation measure. White Mountains described the 2025 figure as enterprise value, while Monday’s IPO figure is being reported on a fully diluted equity basis. Enterprise value incorporates the effect of debt and cash, whereas equity value focuses on the value attributable to shareholders. The different bases can produce materially different numbers even before considering changes in the business between the two dates.
CVC became the majority capital partner at the end of 2025, with White Mountains retaining a minority position. The planned IPO would introduce public shareholders without changing the fact that the offering shares are being sold by existing holders rather than issued by Bamboo to fund operations. The prospectus identifies J.P. Morgan, Morgan Stanley, Deutsche Bank Securities, Evercore ISI and Wells Fargo Securities among the underwriters.
The $18 to $20 range is not a final IPO price. Pricing can still change before the offering becomes effective, and the NYSE listing remains subject to approval. The next concrete milestone is the final prospectus and pricing decision, which will determine the actual per-share price, the proceeds received by the selling shareholders and the market valuation at which BMB begins trading.
More from Investing
Latest News
View all news- Corteva Board Gives Final Approval for Vylor Separation and October 1 Distribution
- Rainier Acquisition Holders Can Begin Separating SPAC Units Into Shares and Warrants
- NUBURU Returns to NYSE American After July Trading Suspension
- Onconetix Extends Up to $5 Million Bridge Financing to Realbotix Ahead of Acquisition
- BioNTech and OncoC4 Report Survival Gain in Phase 3 Lung Cancer Trial
