
TWC Enterprises’ New TSX Buyback Authorization Takes Effect for Up to 1.21 Million Shares
The ClubLink golf operator may repurchase up to 1,205,556 common shares through Sept. 19, 2027, although management retains discretion over the amount and timing.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy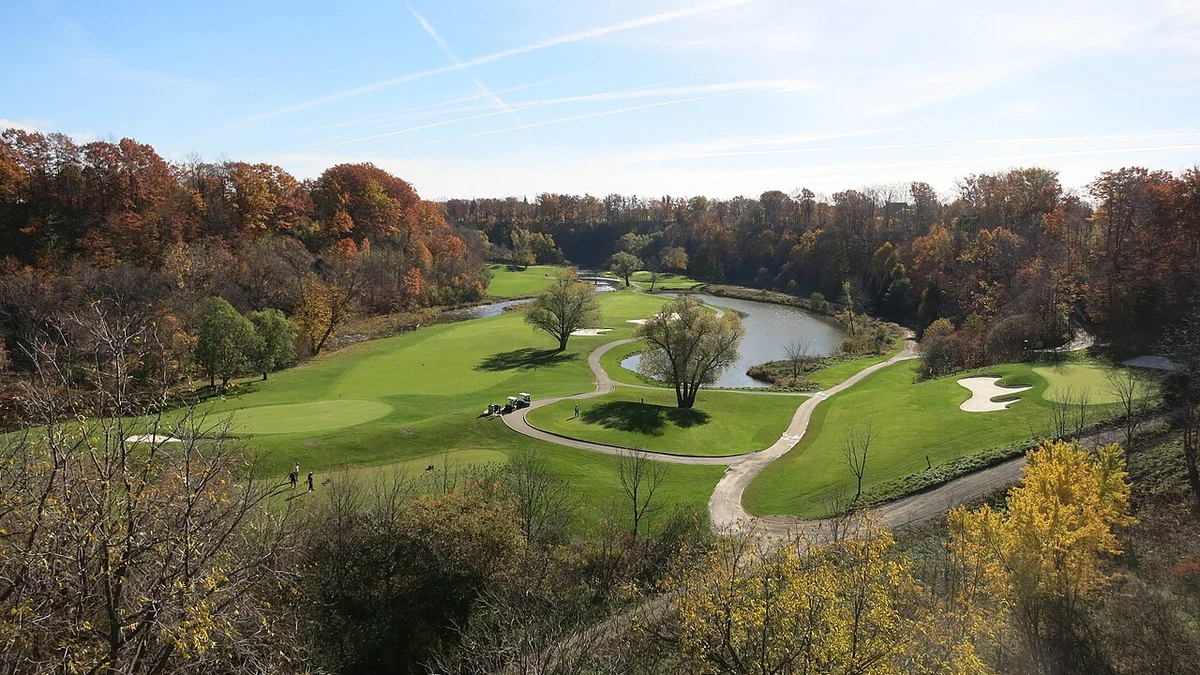
TWC Enterprises Limited’s renewed normal course issuer bid begins September 20, giving the ClubLink golf operator authority to buy back up to 1,205,556 common shares through the Toronto Stock Exchange or alternative Canadian trading systems. The ceiling represents about 5% of the company’s issued and outstanding common shares, and the authorization runs through September 19, 2027.
The size of the authorization is not a commitment to purchase the full amount. TWC said management will determine both the number of shares actually acquired and the timing of those purchases, with any repurchased shares cancelled. The company will pay the market price at the time of each acquisition.
In its September 17 announcement, TWC said it had 24,111,121 common shares outstanding as of September 10. If the full new authorization were used and no other share issuances or cancellations occurred, the share count would fall to roughly 22.91 million. That calculation illustrates the maximum scale of the program, not an expected outcome.
New bid resets TWC’s annual repurchase capacity
The new ceiling is only slightly below the 1,208,438 shares authorized under the program that expired September 19, 2026. TWC used just a small part of that earlier capacity, buying 70,500 shares for cancellation at an average cost of C$25.69 per share. Based on the reported average price, that represents roughly C$1.81 million of repurchases and about 5.8% of the prior share authorization.
That history matters because the headline figure sets a maximum rather than a target. A normal course issuer bid gives a company flexibility to buy shares when management considers the price and other conditions attractive, but it does not require the company to exhaust the limit. TWC’s own experience during the prior year shows that the gap between authorized capacity and actual purchases can be wide.
The company also reported an average daily trading volume of 1,359 shares over the prior six months. Daily purchases under the new bid will be limited to 1,000 common shares, except where block-purchase exceptions apply. With an annual ceiling above 1.2 million shares but a relatively modest ordinary daily limit, the pace of any repurchases will depend heavily on market conditions, management decisions and whether qualifying block purchases become available.
TSX rules constrain how the buyback can be executed
TWC’s purchases are subject to Toronto Stock Exchange rules governing normal course issuer bids. The TSX rule framework says issuer purchases should occur through the open market and includes price restrictions designed to prevent a listed company from abnormally influencing the market price of its securities. Among other provisions, purchases are not supposed to be made above the last independent board-lot trade, subject to the applicable rules and exceptions.
For TWC shareholders, that structure means the company has a standing authorization, not a fixed-price tender. Repurchases can be spread across the authorization period, paused, or left unused. The number bought on any given day can therefore be far below the annual maximum, and the average price paid over the year can differ materially from the market price when the program begins.
TWC said it believes its common shares have traded in ranges that do not adequately reflect the value of the business and its future prospects. That is management’s stated rationale for the repurchase program rather than an independent valuation conclusion. The company also said cancelling repurchased shares is expected to increase the proportionate ownership interest of shareholders who continue to hold their shares.
The arithmetic behind that second point is straightforward. When shares are repurchased and cancelled, the ownership denominator shrinks. If all else stays equal, a shareholder who does not sell owns a slightly larger percentage of the company afterward. The economic benefit still depends on the price paid for the shares, the amount of cash used and the alternatives available for that capital.
Golf operations provide the backdrop for the capital return
TWC operates golf clubs under the ClubLink brand. In the buyback announcement, the company described its portfolio as 46 18-hole equivalent championship courses and 2.5 18-hole equivalent academy courses, including three managed properties, across 34 locations in Ontario, Quebec and Florida. Glen Abbey Golf Club in Oakville, Ontario, which is shown in the featured image, is part of the ClubLink family.
The company’s most recent reported quarter provides additional context for the capital decision. For the three months ended June 30, 2026, TWC reported operating revenue of C$57.1 million, down from C$61.6 million a year earlier, while net earnings were C$19.4 million compared with C$21.5 million. For the first six months of 2026, operating revenue was C$93.1 million versus C$102.3 million in the prior-year period, while net earnings increased to C$25.6 million from C$22.6 million.
Those figures show why the buyback should be read as one part of TWC’s broader capital allocation rather than as a standalone signal about near-term operating performance. The company remains exposed to the economics of its golf properties, membership activity, rounds played, real estate activity and other items that can move earnings from period to period. A repurchase program changes the share count only to the extent that shares are actually bought and cancelled.
The renewed bid is now in effect through September 19, 2027. TWC retains discretion over whether to buy, when to buy and how much of the 1,205,556-share authorization to use, subject to the daily limit, block-purchase exceptions and applicable TSX rules.
More from Investing
Latest News
View all news- France and Canada Put LNG, Energy and Critical Minerals on Macron-Carney Agenda
- U.S. and China Open New York Economic Talks on Trade, AI and Critical Minerals
- Australia Raises Pension Payments and Deeming Rates From Sept. 20
- Coforge Expands AI Vehicle-Lifecycle Capabilities for Lenders and Remarketing Firms
- REPT BATTERO and Germany’s Haller Group Sign European Battery Partnership
