
Hut 8 Secures $1.07 Billion Revolving Credit Facility as AI Infrastructure Buildout Expands
The four-year senior secured facility gives Hut 8 more than $1 billion of committed parent-level liquidity as it develops a growing pipeline of power and AI data center projects.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy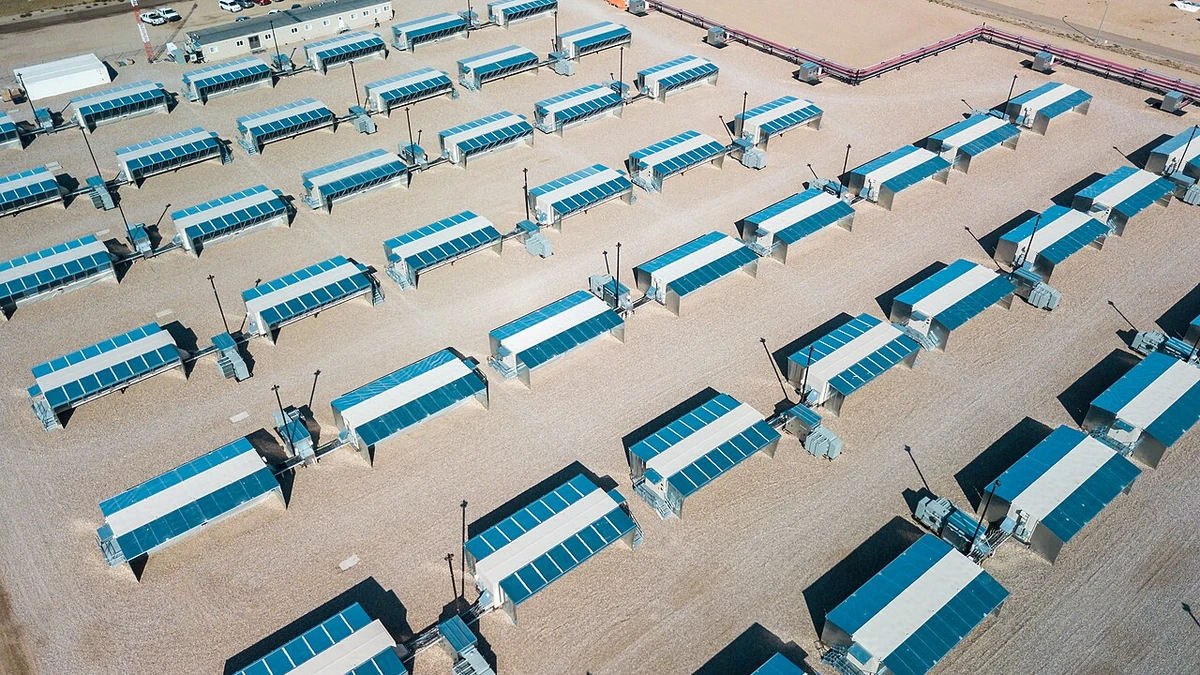
Hut 8 Corp. has closed a $1.07 billion four-year senior secured revolving credit facility, adding a new layer of parent-level liquidity as the company expands its power and artificial intelligence infrastructure pipeline.
The financing gives Hut 8 access to committed bank capital that can be drawn as needed for development-stage spending and working capital. The company said the structure is intended to bridge projects through earlier phases before longer-term, non-recourse project financing is put in place. That approach matters for a developer pursuing large data center campuses, where interconnection deposits, equipment commitments and other costs can arise well before a project reaches stabilized operations.
Hut 8’s announcement comes after a rapid increase in the scale of its AI infrastructure program. The company has already raised $7.5 billion of project-level investment-grade financing for its River Bend and Beacon Point data center campuses, while reporting an 8,660-megawatt development pipeline as of June 30. The new revolver is designed to sit at the corporate level rather than replace those project-specific financings.
The revolver adds flexible parent-level liquidity
In its September 28 announcement, Hut 8 said borrowings under the facility will carry a margin ranging from SOFR plus 150 to 200 basis points, based on its consolidated total debt-to-market-capitalization ratio. The initial margin at closing is SOFR plus 175 basis points.
Borrowings can be drawn when needed and repaid without prepayment penalties, subject to customary conditions. The facility also includes a $1.07 billion letter-of-credit sublimit. Hut 8 said that sublimit can support collateral requirements tied to site development, including interconnection deposits and obligations to utilities and equipment vendors. Using letters of credit for those obligations can reduce the amount of cash that must otherwise be posted as collateral while a site is still being developed.
J.P. Morgan acted as lead left arranger and bookrunner and is serving as administrative agent. Citi, Goldman Sachs and Morgan Stanley are joint lead arrangers and joint bookrunners. Hut 8 said the facility was provided by a syndicate of 12 lenders.
The distinction between committed liquidity and long-term project debt is central to the financing strategy described by management. Chief Financial Officer Sean Glennan said the facility gives Hut 8 the ability to fund projects through development while choosing when and how to arrange non-recourse financing as those projects become less risky. In practical terms, the revolver gives the company a corporate funding source during periods when a project may have meaningful cash needs but is not yet ready for permanent financing.
AI data center projects have pushed funding needs higher
The new credit line follows two large construction financings completed earlier this year. Hut 8 closed $3.25 billion of senior secured notes for its River Bend data center project in Louisiana in April. The company described that financing as fully amortizing, non-recourse to Hut 8 and structured to fund development of the 245-megawatt facility without an expected additional equity contribution from the parent.
In June, Hut 8 closed another $4.25 billion of senior secured notes for the first phase of its Beacon Point campus in Texas. That financing was also structured at the project level and was intended to fund a 352-megawatt turnkey data center and related substation infrastructure. Together, River Bend and Beacon Point account for the $7.5 billion of investment-grade project financing cited by the company in Monday’s announcement.
Those projects illustrate why a revolving facility can serve a different purpose from construction bonds. Long-dated project debt is generally tied to a specific asset and its contracted economics. A corporate revolver can instead provide liquidity before a project has reached the point where that type of financing is economical or available. Hut 8 said the new facility is meant to support interim working-capital needs and allow it to optimize the timing and structure of long-term financing.
The scale of the development pipeline increases the usefulness of that flexibility. In its second-quarter results, Hut 8 said its pipeline totaled about 8,660 megawatts at the end of June, including capacity under diligence, exclusivity, development and construction. The company has increasingly positioned itself around power availability and large-scale digital infrastructure rather than treating bitcoin mining as its only growth avenue.
The balance-sheet strategy is shifting with the business
Hut 8 entered the second half of 2026 with a larger liquidity base than it had at the start of the year. The company reported approximately $8.1 billion of unrestricted cash, restricted cash and cash equivalents, and Bitcoin holdings as of June 30, including amounts attributable to both Hut 8 and its American Bitcoin business. It also said at that time that it had refinanced a $200 million Bitcoin-backed facility through FalconX and, following conversion of a $150 million convertible note, carried no general recourse debt at the parent level.
The $1.07 billion revolver changes that funding toolkit by adding committed bank liquidity directly at the parent. It does not mean Hut 8 has raised another $1.07 billion of project financing, nor does the facility itself represent revenue from AI customers. Its value is access: the company can use the line for general corporate and development needs, then repay and reuse borrowings under the agreed terms.
That flexibility may become more important if Hut 8 advances multiple sites at the same time. Data center development often requires spending on land, engineering, power interconnections, utility deposits and equipment before a project reaches the financing and construction stages associated with contracted cash flows. Hut 8’s letter-of-credit sublimit is specifically aimed at some of those early obligations, which can otherwise tie up cash.
The company is also pursuing an investment-grade corporate profile, according to Monday’s announcement. The new bank facility does not itself establish that outcome, but it adds a diversified source of committed liquidity alongside the project-level financing already raised for River Bend and Beacon Point. The next test will be how quickly Hut 8 converts more of its development pipeline into contracted projects and whether it can continue using non-recourse financing without placing disproportionate funding pressure on the parent company.
More from Investing
Latest News
View all news- Meta Launches Enterprise AI Platform and Hires MongoDB CEO CJ Desai to Run It
- MongoDB CEO CJ Desai Steps Down for Meta; Dev Ittycheria Returns as Interim Chief
- Strategy Discloses $142.7 Million Bitcoin Purchase and $151.7 Million STRC Buyback
- Troilus Secures $850 Million Debt Commitment for Quebec Gold-Copper Project
- GOWell Energy Starts Nasdaq Trading After SPAC Merger and $70 Million PIPE
