
Devon Energy Agrees to Sell Eagle Ford Assets to Crescent Energy for $4.2 Billion
The South Texas acreage contributes roughly 68,000 barrels of oil equivalent a day; Crescent expects the acquisition to close by early 2027.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy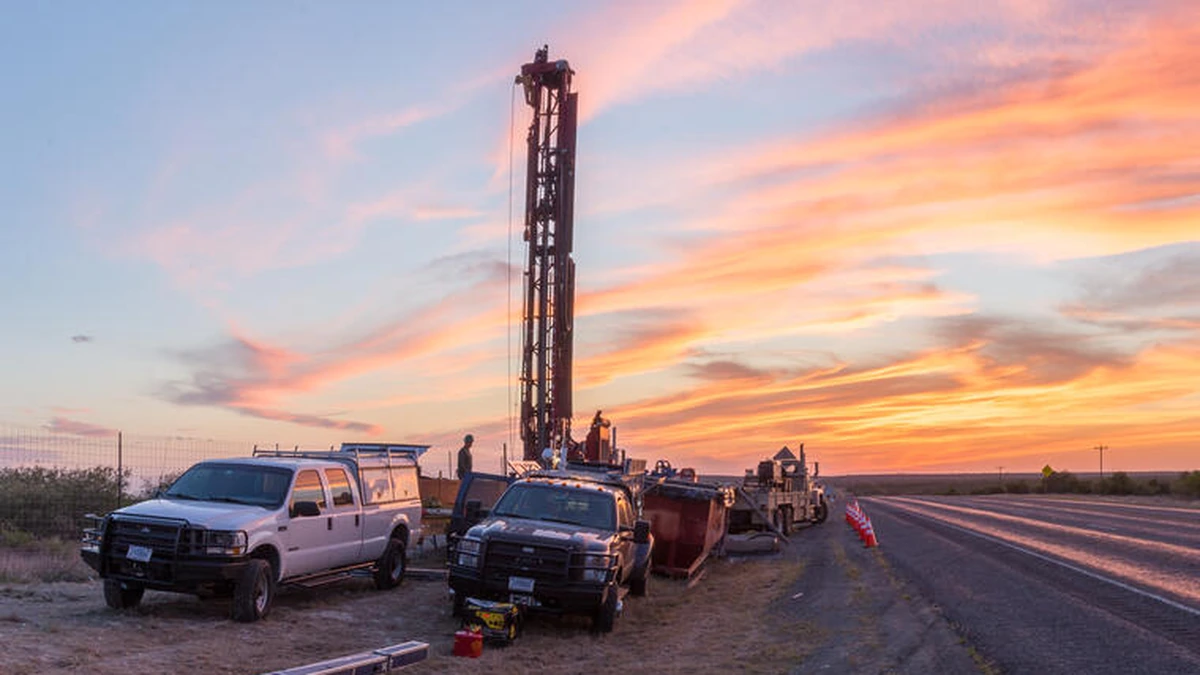
Devon Energy has agreed to sell its Eagle Ford oil and gas assets in South Texas to Crescent Energy for $4.2 billion in cash, a disposal that would narrow Devon’s operating portfolio while enlarging Crescent’s position in one of its main producing areas. The companies announced the agreement on October 8, 2026. The sale has not yet closed and remains subject to adjustments and closing conditions.
The properties cover approximately 90,000 net acres across Karnes, DeWitt and Gonzales counties. Devon says they account for about 4% of its total oil-equivalent production. Crescent estimates the assets currently produce around 68,000 barrels of oil equivalent per day and says much of the acreage lies directly beside its existing Eagle Ford operations.
There are two important price figures. Devon’s announcement identifies $4.2 billion as the cash consideration before customary adjustments. Crescent, the buyer, puts the estimated net purchase price at about $3.85 billion after anticipated adjustments linked to the July 1 effective date. The lower figure is not a separate agreed headline price; it reflects the buyer’s estimate of how the contractual adjustment mechanism affects the ultimate payment.
Devon redirects capital after its Coterra merger
For Devon, the sale follows the completion of its all-stock merger with Coterra Energy in May. That merger expanded the company’s scale and reinforced the Delaware Basin as its principal operating focus. Selling the Eagle Ford properties is part of a broader review aimed at concentrating capital on what management regards as its highest-return acreage.
The decision does not mean the Eagle Ford assets have stopped producing attractive cash flow. Chief Executive Clay Gaspar described the properties as relatively mature and said the company had improved costs and well productivity during its ownership. Devon’s assessment is that selling them now, at the negotiated price, offers a better use of capital than retaining the future production and drilling inventory.
Devon expects the divestiture to lengthen its remaining drilling-inventory life and reduce both its corporate production-decline rate and the oil price needed to cover its go-forward costs. Those are management’s forward-looking assessments, not operating improvements already recorded. A smaller proportion of mature production can change a company’s decline profile, but the eventual financial benefit depends on how the rest of its fields perform and how it deploys the proceeds.
The company intends to direct the after-tax cash from the sale toward faster share repurchases and debt reduction. It has not stated that the full $4.2 billion will be available for those uses: taxes, price adjustments and any other applicable costs affect net proceeds. The distinction matters because the announced purchase price is not the same as cash remaining after the divestiture.
Devon plans to give investors a fuller picture of the effect on its production and financial outlook when it reports third-quarter results on November 5, with a conference call scheduled for November 6. Until then, its stated capital-allocation intentions are clearer than the eventual size or timing of either debt repayment or additional buybacks.
Crescent gains production, drilling inventory and mineral interests
Crescent is buying an operating position that fits alongside its existing Eagle Ford properties rather than entering an unfamiliar basin. Its SEC-filed acquisition announcement describes the new acreage as concentrated in the Karnes Trough, an area where Crescent already owns mineral interests and operates nearby wells. That proximity is a central part of the buyer’s case for the acquisition.
The acquired production is oil-weighted, and Crescent estimates it will add more than 600 net drilling locations that it categorizes as Tier 1, with locations normalized to 10,000-foot well laterals. “Tier 1” is the buyer’s investment classification rather than an independently established ranking. The number describes a prospective development inventory, not wells that are already drilled or guaranteed to be economically productive under every oil-price scenario.
Crescent believes the shared operating footprint can support longer laterals and lower development costs. Longer horizontal wellbores can allow a producer to access more rock from fewer drilling locations, although their economic value depends on geology, completion design and actual well performance. Crescent is presenting those potential efficiencies as reasons the newly acquired acreage could earn a place in its future capital program.
The company has identified approximately $140 million in potential annual savings across drilling and completions, lease operating expenses and marketing. This is a management estimate that must be achieved after closing; it should not be treated as cash flow already generated by the properties. The magnitude of the savings will depend on execution, cost conditions and Crescent’s ability to apply its operating methods to the acquired wells and development plans.
The purchase also includes Devon-owned mineral interests, which Crescent expects to enlarge its Crescent Royalties business. Mineral ownership and working interests have different economics: a mineral owner generally receives royalties tied to production, while the operator bears a share of drilling and operating costs. Crescent says increasing its operating role around properties in which it already holds mineral interests should give it more control over development timing and better visibility into future royalty receipts.
That leaves Crescent acquiring both current production and opportunities to develop additional wells. The current barrels underpin near-term revenue, while the prospective drilling inventory and operating savings support its longer-term return assumptions. Those future benefits are more exposed to commodity prices, development spending and execution than the existing production figure.
Financing and regulatory approvals set the closing timetable
Crescent expects to finance the purchase using cash on hand and a mix of debt and equity, with the precise proportions depending on market conditions. It has disclosed commitments for debt-financing options from JPMorgan Chase Bank and RBC Capital Markets, with KKR Capital Markets advising on the financing. The company has also disclosed a conditional $2 billion, 364-day senior unsecured bridge commitment in its SEC materials. A bridge commitment is a potential funding backstop, not evidence that the entire amount has already been borrowed.
The funding choice creates a different set of considerations for Crescent shareholders than for Devon shareholders. More borrowing could raise interest costs and leverage, while issuing equity could dilute existing holders. Management argues that the additional production and expected free cash flow will support debt reduction over time, but those benefits depend on closing the acquisition and delivering the anticipated performance.
The purchase has a July 1, 2026 effective date for economic adjustments, even though the agreement was announced in October. That allows specified revenues and expenses between the effective date and closing to be allocated under the contract. It also helps explain why Crescent’s estimated $3.85 billion net price differs from the $4.2 billion cash consideration disclosed by Devon.
Devon expects the sale to close around year-end, while Crescent gives a window extending from the fourth quarter of 2026 into early 2027. The agreement remains subject to customary conditions, including applicable regulatory clearance and the antitrust waiting-period requirements identified in Crescent’s SEC materials. Until the sale closes, Devon retains the assets and Crescent’s anticipated operating benefits remain prospective.
More from Investing
Latest News
View all news- U.S. Initial Jobless Claims Fall to 197,000 as Layoffs Remain Historically Low
- New Zealand Household Net Worth Falls NZ$8.4 Billion in June Quarter
- Main Street Capital Originates $157.2 Million of New or Increased Private-Loan Commitments in Q3
- GlobalFoundries Signs $2 Billion TSMC Deal to Make AI-Packaging Interposers in New York
- German Exports Fall 0.8% in August as Trade Surplus Narrows to €19.5 Billion
