
German Exports Fall 0.8% in August as Trade Surplus Narrows to €19.5 Billion
Shipments to the United States weakened even as exports to Britain and China rose, while higher imports reduced Germany’s monthly goods-trade surplus.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy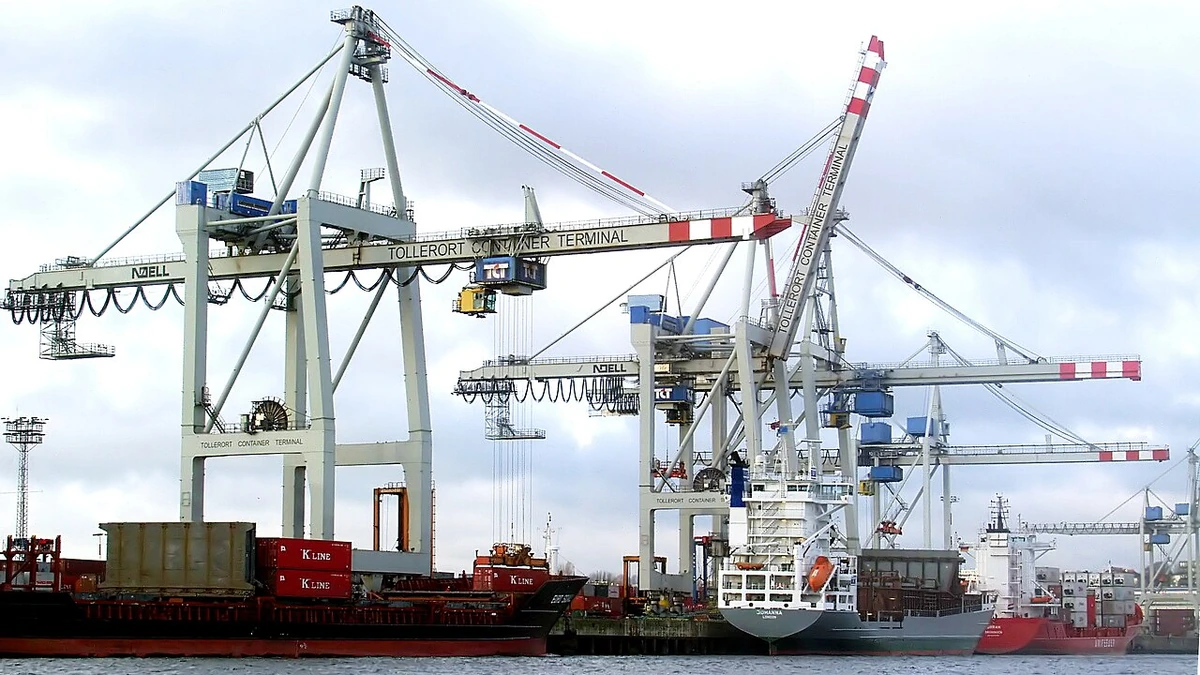
German goods exports fell 0.8% in August from July, while imports rose 0.9%, reducing the country’s trade surplus to €19.5 billion, according to figures released Thursday by the Federal Statistical Office (Destatis). The decline left exports at €137.6 billion and imports at €118.1 billion after adjustment for seasonal and calendar effects.
The surplus narrowed from a revised €21.6 billion in July, a decline of €2.1 billion. That makes August a weaker month for Germany’s trade balance, although the surplus was still larger than the €17.6 billion recorded in August 2025. Destatis reported the figures in its October 8 foreign-trade release, which it described as provisional.
Exports had already slipped in July, and the August decline extended the retreat from June’s €139.3 billion adjusted total. The latest figures put July’s decline at a revised 0.5%, followed by a further 0.8% decrease in August. Behind those national totals, trade moved quite differently across Germany’s major overseas markets.
U.S. shipments drop, but Britain and China post gains
The United States remained Germany’s largest individual export destination in August, even as shipments there fell 6.3% from July to €13.5 billion. The monthly setback followed an especially strong July, making the change in direction more striking than the headline decline in total exports. On a year-earlier comparison, German exports to the United States were still 22.6% higher in August.
Sales to two other important non-EU markets improved. Exports to the United Kingdom rose 16.7% month on month to €7.9 billion, and those to China increased 4.7% to €5.9 billion. These gains were not sufficient to offset weaker shipments elsewhere. Germany exported €60.0 billion of goods to countries outside the European Union, down 1.1% from July.
The EU picture was mixed as well. Exports to the bloc declined 0.6% to €77.5 billion, but sales to euro-area members increased 0.8% to €54.3 billion. The drop was concentrated in EU countries that do not use the euro, where shipments fell 3.5% to €23.2 billion. That distinction matters because a decline in exports to the EU does not necessarily mean demand weakened across every part of the single market.
China was also central to the import side of the report. Germany bought €16.8 billion of goods from China in August, an 11.0% increase from July and more than from any other individual country. Imports from the United States eased 0.5% to €8.1 billion, while those from Britain fell 3.8% to €3.2 billion. Overall imports from outside the EU rose 2.2% to €58.8 billion; imports from EU members declined 0.4% to €59.3 billion.
The longer view reveals a persistent imbalance in trade with China despite August’s export improvement. In the first eight months of 2026, Germany’s adjusted exports to China were down 12.9% from the corresponding period of 2025, while imports from China were up 10.1%. Exports to the United States, by comparison, were 1.1% higher over those eight months. Those year-to-date figures should not be confused with the more volatile changes from July to August.
The smaller surplus sits alongside annual export growth
August’s monthly decline does not mean German exports were below their level a year earlier. On a calendar- and seasonally adjusted basis, exports were 6.2% higher than in August 2025, and imports were up 5.5%. The trade surplus, although smaller than in July, exceeded its year-earlier level by €1.9 billion. The distinction between monthly momentum and annual growth is important when judging the condition of an export-dependent economy.
Across January through August, adjusted goods exports reached €1,092.7 billion, an increase of 4.4% over the same eight months of 2025. Imports totaled €946.7 billion and also rose 4.4%. Trade with EU members expanded more rapidly on the export side over that period, with exports up 7.2%, whereas exports to non-EU countries grew just 0.8%. The August weakness therefore came after several months in which Europe had accounted for much of the year’s export growth.
Destatis also publishes figures that have not been adjusted for seasonal or calendar patterns. On that original, nominal basis, exports were €123.4 billion and imports €108.4 billion in August, giving a surplus of €15.0 billion. Exports in that series were up 7.0% from August 2025, and imports increased 6.0%. These unadjusted levels are different from the €137.6 billion export and €118.1 billion import figures used for the month-to-month comparison; mixing the two series would give a misleading reading of the balance.
The July comparison has also changed as updated data became available. Destatis initially reported a €21.3 billion adjusted surplus for July in September, but its latest release puts the figure at €21.6 billion. Revised July exports are now €138.7 billion, rather than the €138.2 billion first reported. The August decline should be measured against those newer July numbers, not the earlier estimates.
Factory orders and higher trade prices complicate the picture
Other recent German economic indicators underline why one month’s exports cannot, on their own, settle the outlook for manufacturing. Destatis said on October 6 that price-adjusted new manufacturing orders fell 10.6% in August. Most of that drop reflected a reversal in unusually large orders for ships, aircraft, trains and other transport equipment after an exceptional July. Without large-scale orders, the monthly decline was only 0.1%.
Foreign manufacturing orders nonetheless weakened by 5.4%, with orders from euro-area customers and customers outside the currency bloc both falling by roughly that amount. Over the three months through August, total orders rose 1.3% from the preceding three-month period, but excluding large orders they fell 2.6%. That split suggests the monthly headline was distorted by individual contracts while the less volatile underlying trend also deserved caution.
Price data add a separate complication. Germany’s import-price index was 8.3% above its August 2025 level, the strongest annual increase since December 2022, and rose 1.0% from July. Export prices increased 4.7% from a year earlier and 0.4% month on month. Destatis attributed much of the import-price pressure to energy and intermediate goods, with energy imports costing 43.0% more than a year earlier.
These price movements matter because the trade report’s goods values are measured in euros, not as a direct count of physical goods shipped. A rise in the value of exports over a year can reflect higher prices as well as changes in quantities. The August figures establish that adjusted export values fell from July and import values rose; they do not show that a particular tariff, energy-price change or supply disruption caused the move.
Destatis explicitly cautioned that its first provisional monthly results do not yet contain enough detail to explain the changes in total trade or individual partner-country flows. The agency said fuller foreign-trade results are due on October 20. Those figures should help clarify which products contributed most to August’s softer exports and higher imports.
More News
Latest News
View all news- Viatris Agrees to Acquire Pacira BioSciences for $1.65 Billion
- Samsung Guides to KRW107.4 Trillion Q3 Operating Profit on KRW195 Trillion Sales
- PepsiCo Reports 5.6% Q3 Revenue Growth but Cuts Core EPS Growth Outlook
- GlobalFoundries Signs $2 Billion TSMC Deal to Make AI-Packaging Interposers in New York
- Devon Energy Agrees to Sell Eagle Ford Assets to Crescent Energy for $4.2 Billion
