
U.S. Durable Goods Orders Rise 1.8% in September, Led by Transportation Equipment
Orders reached $345.4 billion, with transportation equipment contributing $5.2 billion of the $6.3 billion monthly increase.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy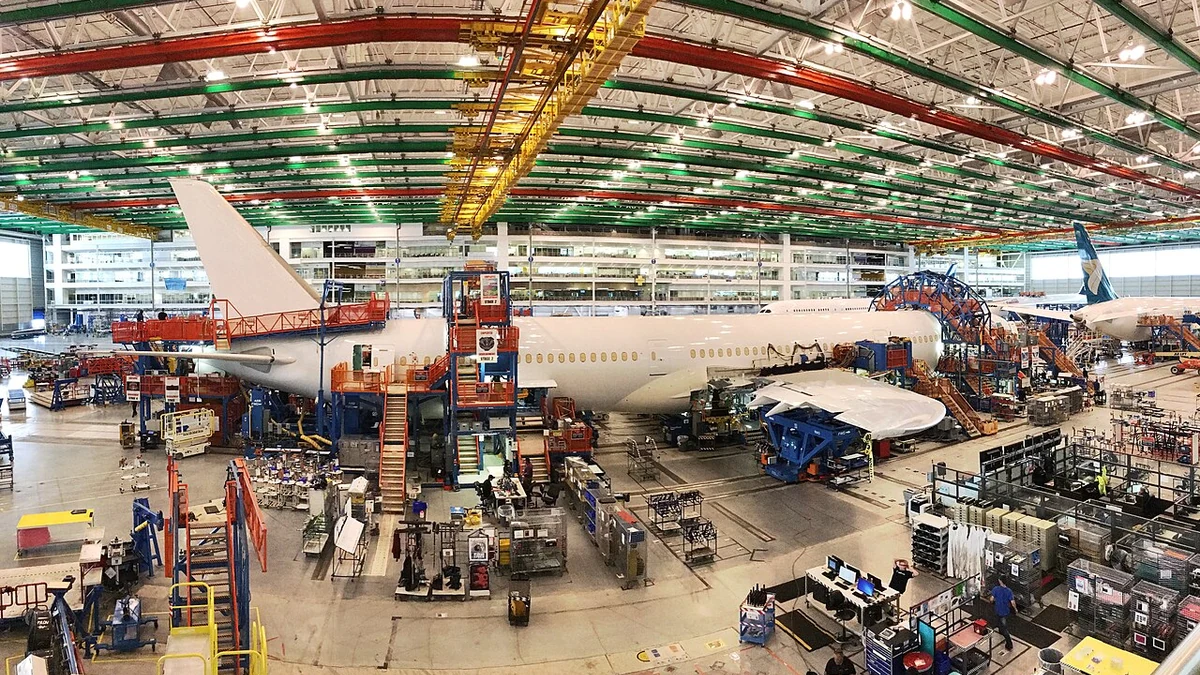
New orders for U.S.-manufactured durable goods increased 1.8% in September to $345.4 billion, the Commerce Department’s Census Bureau reported Tuesday. Transportation equipment provided most of the lift, with orders for that category rising $5.2 billion, or 4.6%, as manufacturers recorded a $6.3 billion increase across durable goods.
The rise followed a revised 0.1% increase in August and marked the sixth monthly gain in seven months. The headline suggests firmer demand for long-lasting manufactured products, but the concentration in transportation makes it important to separate the overall increase from what happened elsewhere in the factory sector.
Transportation equipment drove the September increase
Transportation equipment orders reached $119.8 billion in September. Based on the rounded figures in the Census Bureau’s advance durable goods release, the category accounted for about four-fifths of the month’s total dollar increase. It represented roughly 35% of all new durable goods orders, yet contributed substantially more than that share of the monthly gain.
Those proportions help explain both the strength and the limits of the headline. A large increase in one capital-intensive industry can move the national total even when orders among other manufacturers grow much more slowly. Transportation covers several types of equipment, including aircraft and motor vehicles, so the broad category alone does not identify which products or buyers were responsible for the September change.
The Census Bureau said transportation equipment orders were higher in two of the latest three months. That pattern is consistent with an uneven sequence rather than uninterrupted growth. The latest advance summary does not establish that any particular aircraft manufacturer, automaker or defense contractor received the orders behind the increase, and the data should not be read as a company-specific sales report.
Order figures also describe commitments rather than finished products. Manufacturers can receive orders for items that will take months or longer to make, and reported new orders are calculated after cancellations. A strong month for transportation bookings can therefore precede, rather than coincide with, a comparable change in shipments or factory output.
Demand outside transportation showed a smaller gain
Excluding transportation equipment, durable goods orders increased 0.5% in September. That positive reading matters because it means the rest of the sector was not, in aggregate, declining while transportation lifted the total. Still, a half-percent rise is much more modest than the 4.6% increase recorded by the transportation category.
A different measure, orders excluding defense, rose 2.2%. The two exclusions answer separate questions: one removes transportation equipment and the other removes defense-related orders. They should not be treated as equivalent measures of underlying demand, particularly because transportation and defense can overlap. Taken together, the readings show that the 1.8% headline is not the only useful way to assess September manufacturing orders.
For business investment, economists also examine orders for nondefense capital goods excluding aircraft. That narrower series is often used to judge demand for the equipment businesses intend to purchase, without the direct effect of military procurement or large aircraft orders. It offers a useful comparison with the transportation-heavy headline, although one month of orders does not by itself establish the pace of actual equipment spending.
Orders measure commitments, not completed output
The Census Bureau’s Manufacturers’ Shipments, Inventories, and Orders survey tracks several measures that describe different points in the production cycle. New orders reflect purchase commitments net of cancellations. Shipments measure products sold by manufacturers, while unfilled orders are work that has been booked but not yet recorded as sales. Inventories measure goods and materials still held by manufacturers.
Those measures do not necessarily move together in any given month. A factory might book additional future work before it raises output, or ship products against orders received earlier in the year. Backlogs can grow when orders outpace the amount of work completed. Looking at shipments and unfilled orders alongside new bookings helps clarify whether demand is translating into current activity or building a pipeline of later production.
The figures are seasonally adjusted, but they are not adjusted for inflation. As a result, a higher dollar value of orders does not automatically mean the same percentage increase in the physical quantity of goods ordered. Changes in prices or the mix of products can affect the totals. That qualification is especially useful for a report influenced by expensive transportation equipment.
The M3 survey draws on reports from manufacturers to estimate monthly industry movements, rather than measuring every order placed in the United States. Census Bureau methodology also cautions that the panel is not a probability sample, so conventional sampling errors cannot be calculated. Advance readings can change as additional information is incorporated into the full monthly report.
The Census Bureau is scheduled to publish the full September manufacturers’ shipments, inventories and orders report on November 3, 2026. That release will provide a broader view of factory activity, including nondurable goods, and may revise the advance durable goods estimates. The next advance report, covering October, is scheduled for November 25. Those updates will help show whether September’s transportation-led order growth carried into subsequent months.
More News
Latest News
View all news- New PBGC Pension Valuation Spreads Take Effect for Terminating Plans
- Three State Street SPDR Bond ETFs Adopt New Names on October 31
- Taiwan Launches Expanded Credit-Information Sharing Between Banks and Securities Firms
- New Zealand Eases Trustee Requirements for Four Retirement Schemes
- France Reopens Agricultural Diesel Aid Claims With New November Deadline
