
Bank of Canada Brings Real-Time Rail Payments System Under Formal Oversight
The central bank placed the newly launched payments network under risk-management oversight, effective November 8, as Payments Canada begins a phased national rollout.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy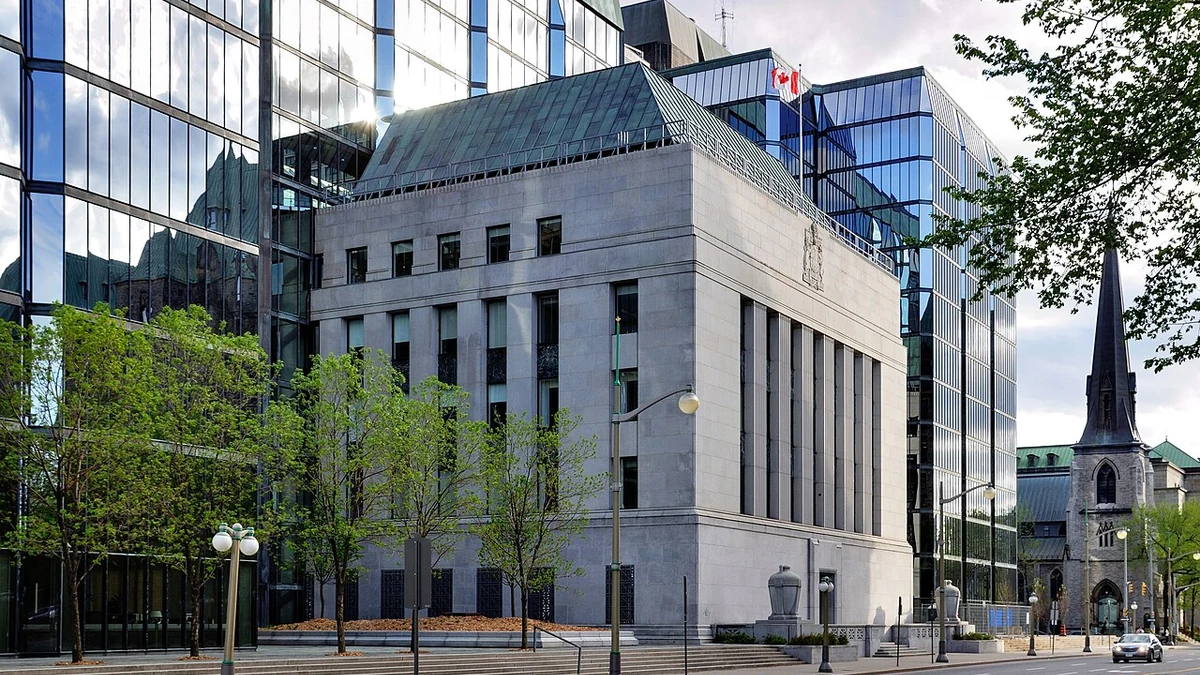
The Bank of Canada has designated Canada’s new Real-Time Rail (RTR) a prominent payment system, bringing the national instant-payments network under formal central-bank oversight as it begins operating. Governor Tiff Macklem’s designation took effect November 8, 2026, one day before Payments Canada announced the system’s launch on November 9.
The decision puts the operator’s risk controls and operational resilience under the Bank’s supervision from the outset. Payments Canada will continue to run the network, but its role now carries requirements intended to limit disruption to a service built for payments that can clear and settle around the clock.
Oversight designation sets standards for a critical payment network
In its designation announcement, the Bank said RTR falls under the Payment Clearing and Settlement Act, which gives the central bank authority to oversee clearing and settlement systems capable of creating material financial or payments-system risks. Payments Canada must ensure the new rail complies with the Bank’s risk-management standards, including controls for safety and resilience.
The designation is more specific than a general endorsement of faster payments. Under the Bank’s framework, a prominent payment system is one whose disruption could significantly impair economic activity, including people’s or businesses’ ability to make payments. That category is distinct from a systemically important financial market infrastructure, where failures may spread financial distress between institutions. The distinction determines the type of risk the regulator is overseeing, rather than declaring the new rail free of broader financial risks.
The operator is also subject to the Bank’s resolution regime for designated domestic clearing and settlement systems. That framework is meant to preserve essential services if a system were to become non-viable. It is a continuity arrangement for the infrastructure, not a promise that individual users will be reimbursed for mistaken or fraudulent transfers.
Bank supervision will sit alongside the rules and obligations governing institutions that participate in RTR. The Bank’s oversight guidance calls on designated systems to maintain appropriate risk-management practices and provide information needed to assess whether they are operating safely. That matters more for a rail designed to work continuously, when technical faults or a participant’s inability to process payments could affect users beyond normal banking hours.
There is already a regulatory precedent for overseeing everyday payment services in Canada. Interac e-Transfer and Payments Canada’s existing clearing systems are among the networks listed in the Bank’s oversight framework. The new designation brings RTR into that supervisory landscape as an additional piece of national payment infrastructure, rather than replacing those services overnight.
Payments Canada begins a phased real-time rollout
Payments Canada announced the launch of RTR on November 9, saying participating members can exchange, clear and settle payments in real time, 24 hours a day and every day of the year. The rail is designed to make funds available immediately and to carry richer payment information through the ISO 20022 messaging standard, which can help businesses match receipts to invoices and track incoming payments.
The first group of active participants includes Wealthsimple, Questbank, Peoples Trust Company, Paramount Commerce, KOHO, DoBusiness.com, Digital Commerce Bank and Bank of America, according to Payments Canada. Those names illustrate the mix of financial institutions and payment service providers joining at launch. They do not mean that every customer at every Canadian bank can already send a new RTR payment through their existing account.
Payments Canada is introducing participants and payment volumes in stages. Its published target timetable calls for initial participants to migrate Interac e-Transfer clearing and settlement to RTR in the first quarter of 2027, followed by additional migration participants in the second quarter. The plan targets full volumes for participants in the initial launch phases in the third quarter of 2027. Those dates are rollout targets, not a confirmation that each institution will make identical consumer-facing features available at the same time.
The distinction between the network going live and wider availability is important. RTR provides a foundation on which banks and other providers can offer payment products, while each participant still needs to complete the necessary technical and operational steps. Payments Canada expects the service to become available to more than nine in 10 Canadians during its first year, but that is the operator’s projected reach, not a current usage figure.
The new infrastructure is also intended to support business payments that currently depend on processing schedules. A retailer receiving an electronic payment or a small company awaiting funds from a customer could benefit from more predictable cash flow as participating providers add services. Those advantages will depend on actual adoption and product design, and should not be confused with guaranteed instant access for every type of payment from launch day.
Fraud safeguards and settlement access remain separate tests
Speed introduces a different operational challenge: once money moves and settles in seconds, there is less time to identify suspicious instructions before a transfer is completed. Payments Canada says the rail begins with mandatory centralized fraud services operating alongside participants’ existing controls. They include confirmation of payee for consumer accounts, a payment-risk score, a repository of fraud indicators and a platform for reporting and sharing fraud intelligence.
Those measures are part of the system’s design, but they do not make fraud impossible. The Bank of Canada expressly notes that its oversight of designated clearing and settlement systems does not extend to consumer protection. It expects appropriate fraud-prevention measures, while advising people who experience fraud to contact their financial institution and notify the Canadian Anti-Fraud Centre. The regulatory designation should therefore not be read as a new guarantee for consumer losses.
Participation also depends on arrangements for settling obligations. Under the Bank’s RTR settlement-account policy, applicants must qualify for Payments Canada membership and satisfy the system’s participation requirements. The Bank distinguishes restricted accounts, which permit settlement only for the account holder, from unrestricted accounts that may also support approved settlement-agent activity. Applicants face assessments that include their financial viability and financial-crime risk controls. These checks are separate from the designation of the rail itself.
The Bank’s decision arrives at the point when oversight and operations become closely connected. As more institutions join RTR and existing e-Transfer clearing and settlement begins migrating, the value of the new network will increasingly depend on sustained reliability, effective fraud controls and orderly onboarding. Payments Canada’s first scheduled migration phase, targeted for early 2027, will be an important operational test of that expansion.
More from Banking
Latest News
View all news- U.S. Wholesale Sales Jump 2.8% in September as Inventories Rise 0.7%
- USDA Finalizes Rural Mortgage Rule Excluding Agent Commissions From Seller Concession Cap
- SEC Holds Roundtable on AI-Readable Financial Data and Market Risks
- NRG Energy Agrees to Sell Six Natural Gas Power Plants to LS Power for $4 Billion
- IRS Car Loan Interest Deduction Regulations Take Effect With $10,000 Annual Limit
