CareTrust Agrees £1.1 Billion Deal for 45 UK Care Homes, Raises 2026 Guidance
CareTrust’s £576 million first tranche covers 24 recently built care homes, while 21 development properties are scheduled for rolling acquisitions through 2027.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy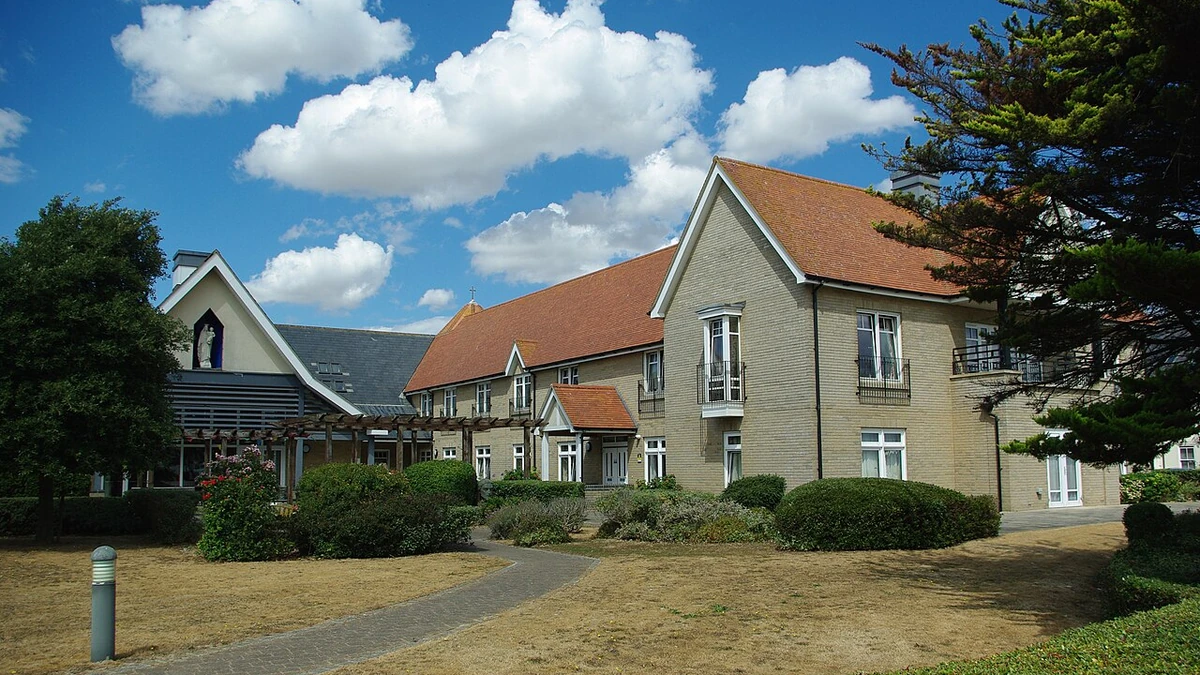
CareTrust REIT has agreed to acquire 45 newly built care homes in the United Kingdom from LNT Care Developments Holdings for about £1.1 billion, while raising its full-year 2026 earnings outlook as the healthcare property owner expands its U.K. senior housing strategy.
The acquisition is not a single completed purchase. CareTrust said in its SEC-filed announcement that the first tranche began closing on October 1 and covers 24 care homes built within the past two years for approximately £576 million, or about $764 million using the company’s September 28 exchange-rate assumption. The company funded that initial investment with proceeds from settled forward equity agreements and a draw on its revolving credit facility.
One detail in the filing matters for understanding the closing status. CareTrust’s announcement describes the first tranche as 24 homes, but a footnote says one completed and operating property in that group still requires regulatory approval, which the company expects during October. The other 21 homes in the broader 45-property acquisition remain under development. CareTrust expects to buy those properties for roughly £504 million after construction is finished and approvals are received, with closings anticipated on a rolling basis throughout 2027.
First tranche starts a 45-home, 2,970-unit expansion
CareTrust’s investor presentation says the full portfolio represents 2,970 units across the 45 care homes. The properties are spread across multiple U.K. regions, with the largest concentrations in the South West, East Midlands and South East. The homes are designed for private-pay residents and are part of LNT’s purpose-built development model.
During the initial lease-up period, the homes are, or will be after closing, leased to subsidiaries of Crystal Care, LNT’s operating business, under triple-net leases. In that structure, the operator is responsible for property-level operating costs in addition to rent. CareTrust’s presentation describes leases generally running 20 to 21 years, with LNT providing a guarantee and contractual annual rent increases.
The structure is intended to give CareTrust rental income while newly developed homes fill their beds, rather than exposing the REIT immediately to the early operating ramp of each property. CareTrust expects the lease-up period to be accretive to normalized funds from operations per share, including the effect of straight-line rent accounting. That is a company forecast rather than a guaranteed outcome.
The scale is meaningful relative to CareTrust’s existing U.K. business. In its presentation, the company estimates that, on a pro forma run-rate basis after all 45 homes are acquired and moved into the planned operating structure, the U.K. could account for about 33% of annualized portfolio income, up from roughly 17% before the LNT portfolio. Those percentages depend on the company’s operating assumptions and on the later homes being completed and acquired as expected.
CareTrust plans to shift the homes into its SHOP portfolio
The longer-term strategy goes beyond collecting rent. After each home stabilizes, CareTrust and LNT intend to move the properties into a RIDEA structure with Crystal Care, placing them in CareTrust’s senior housing operating portfolio, or SHOP. CareTrust expects those transitions to begin between two and four years after each home is completed, with the first move targeted as early as the fourth quarter of 2027.
That planned shift would change CareTrust’s exposure from a largely fixed-rent relationship during lease-up to participation in the properties’ operating performance after stabilization. CareTrust expects the first year of the SHOP phase to generate an all-in pre-tax yield in the mid- to high-7% range. The company has also received an option to acquire the broader LNT platform in the future, although no such acquisition has been announced.
CareTrust’s presentation shows why the SHOP component is strategically important. On the company’s pro forma run-rate assumptions, SHOP would rise from about 2% of annualized senior housing and skilled nursing income to about 20% after the full LNT portfolio is converted. The model therefore combines a near-term landlord structure with a later operating-property strategy, rather than moving all 45 homes directly into SHOP at closing.
The approach also leaves execution risk spread over several years. The remaining 21 homes must be completed and obtain required approvals before CareTrust purchases them. The timing of stabilization will vary by property, and the expected SHOP economics depend on occupancy, operating performance and costs after the homes move beyond their initial lease-up periods.
Raised guidance includes the initial LNT tranche, not the 21 development homes
Alongside the acquisition announcement, CareTrust increased its 2026 guidance. The REIT now expects net income attributable to CareTrust of $1.54 to $1.57 per share, normalized FFO of $2.06 to $2.09 per share and normalized funds available for distribution of $2.02 to $2.05 per share.
Those ranges are higher than the outlook CareTrust issued with its second-quarter results in August. At that time, management projected net income of $1.53 to $1.56 per share, normalized FFO of $2.03 to $2.06 and normalized FAD of $2.01 to $2.04. The latest guidance therefore raises both ends of each range, with the largest increase coming in normalized FFO.
CareTrust says the revised 2026 forecast includes the initial LNT acquisition of 24 care homes that closed or is expected to close during October, but excludes the remaining 21 LNT homes that are still under development. The new outlook also assumes no additional investments, loans, dispositions, debt issuance or equity issuance beyond activity already completed or announced, and it assumes no material change in the pound-dollar spot exchange rate.
The LNT agreement arrives during an unusually active investment year for CareTrust. The company said it has closed about $488 million of other investments since its second-quarter earnings report. Including the LNT activity and those other investments, CareTrust put its third-quarter and subsequent investment total at roughly $1.6 billion and its year-to-date total at a record $2.7 billion. Management also reported a near-term actionable pipeline of about $525 million that does not include the 21 LNT development homes already under contract.
For 2026, the immediate financial effect comes mainly from the homes in the first tranche and CareTrust’s other recently completed investments. The larger strategic effect will take longer to emerge, because nearly half of the 45-home portfolio still has to be built and acquired, and the planned move from triple-net leases into SHOP is expected to occur property by property after stabilization.
More from Investing
Latest News
View all news- Standard Chartered Redeems €500 Million of Fixed-Rate Reset Notes
- Resources Connection Names Jessica Block Interim CFO, Trisha Jenks Chief Accounting Officer
- France Launches Bpifrance Zero-Interest Loan Program for Fishing and Marine Aquaculture
- FinCEN’s Southwest-Border Cash-Reporting Compliance Deadline Takes Effect
- Federal Reserve Runs Scheduled Fedwire Production Testing on October 3