
ConocoPhillips Raises Quarterly Dividend 11% After Q3 Earnings Reach $4 Billion
The oil producer lifted its payout to 93 cents a share and returned $3.4 billion to investors, even as quarterly production declined.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy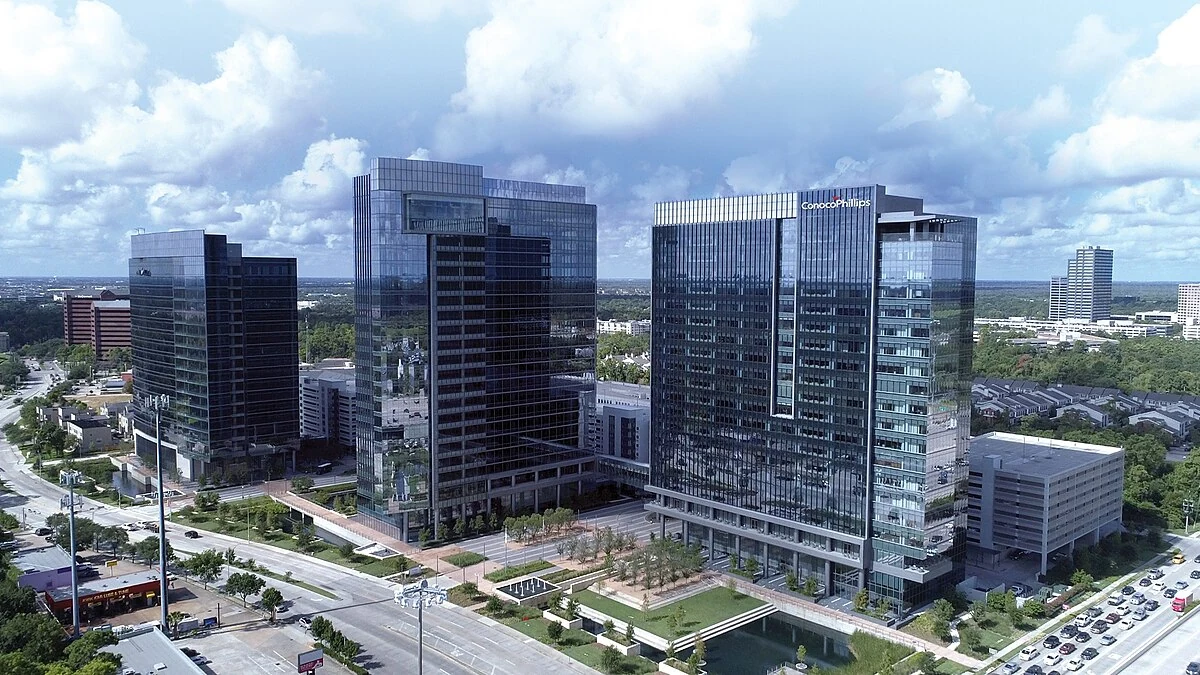
ConocoPhillips raised its quarterly ordinary dividend by 11% after reporting $4.0 billion in third-quarter 2026 earnings, more than double its profit a year earlier. The Houston-based oil and gas producer increased the dividend to $0.93 per share from $0.84, with the higher payment taking effect in the fourth quarter.
Net earnings reached $3.34 per share for the three months ended September 30, compared with $1.7 billion, or $1.38 per share, in the same period last year. Adjusted profit, which excludes special items, increased to $3.9 billion, or $3.27 a share, from $2.0 billion, or $1.61 a share. The company said the latest quarter benefited mainly from higher commodity prices, despite lower oil and gas production.
ConocoPhillips announced the results November 5 and furnished its earnings release and supplemental financial information with a Form 8-K. The company’s investor-relations filings page lists that report alongside its quarterly Form 10-Q. The dividend increase comes as the producer directs a sizable portion of operating cash toward both its regular shareholder payout and stock repurchases.
Higher Oil Prices Offset Weaker Production
The biggest change in the earnings picture was the price ConocoPhillips received for the oil and gas it sold. Its average realized price across the portfolio rose to $61.40 per barrel of oil equivalent, up 32% from $46.44 a year earlier. That improvement helped lift earnings even though overall volumes were lower. Realized prices reflect the mix of hydrocarbons sold and the markets in which they are priced, rather than a single benchmark crude price.
Companywide production averaged 2.302 million barrels of oil equivalent per day, down 97,000 barrels per day from the third quarter of 2025. After accounting for acquisitions and asset sales that changed the size of the portfolio, underlying production declined by 40,000 barrels per day, or about 2%. The distinction matters because the headline volume decrease includes businesses that were added or removed between the two reporting periods.
ConocoPhillips attributed the underlying decline to the effect of the Middle East conflict on its operations in Qatar and higher royalty volumes at Canada’s Surmont oil sands project. Those pressures more than offset organic growth from its Lower 48 business. Management did not present the stronger quarterly profit as evidence that output was expanding across the company.
The Lower 48 produced 1.517 million barrels of oil equivalent per day, making it the largest component of the total. Within that business, the Delaware Basin contributed 757,000 barrels a day, the Eagle Ford 369,000, the Midland Basin 197,000 and the Bakken 191,000. Those assets remain central to ConocoPhillips’ ability to adjust near-term drilling activity and capital spending as market conditions change.
Reported net income was also affected by a reversal of a tax reserve, which the company identified as the primary special item for the quarter. That is why the adjusted earnings figure of $3.9 billion provides a useful comparison with last year’s adjusted $2.0 billion, without implying that the entire increase in reported profit came from operations alone.
Cash Flow Funds the Higher Dividend and Buybacks
ConocoPhillips generated $7.2 billion in cash provided by operating activities during the quarter and reported the same amount for its cash-from-operations measure, which adjusts for working-capital timing effects. Capital expenditures and investments totaled $3.1 billion. On the company’s definition, free cash flow is cash from operations less those expenditures and investments, leaving approximately $4.0 billion for the quarter.
The company distributed $3.4 billion to shareholders, split between $2.4 billion of stock repurchases and $1.0 billion of ordinary dividends. Repurchases accounted for most of the quarter’s shareholder returns. Unlike the recurring dividend, however, the volume of buybacks can be adjusted as cash generation, investment needs and the share price change.
ConocoPhillips said it remains on track to return about 45% of full-year 2026 cash from operations to shareholders. That figure is a company objective for the year, not a promise that the same percentage will be distributed in each quarter. The latest dividend increase commits the producer to a higher regular payment per share, subject to future board decisions, even if commodity prices move lower.
The new $0.93 quarterly dividend is payable December 1, 2026, to shareholders of record at the close of business on November 16. It follows the company’s decision last year to lift its ordinary dividend to $0.84 a share. The November announcement therefore extends a series of increases rather than establishing a new payout for the first time.
Cash flow from continuing operations was not the only source of funds available during the period. ConocoPhillips also received $1.6 billion from disposals of noncore assets, proceeds that are separate from its reported operating cash flow. It ended September with $10.4 billion of cash and short-term investments and held another $1.1 billion of long-term investments, providing a financial cushion alongside its ongoing capital program.
Fourth-Quarter Outlook and Longer-Term Projects
For the final quarter of 2026, ConocoPhillips expects production of 2.32 million to 2.36 million barrels of oil equivalent per day. The forecast is slightly above the third-quarter average at both ends of the range, although it remains guidance rather than a reported result. The producer left its full-year capital expenditure and adjusted operating cost guidance unchanged, signaling no broad revision to its spending plan in the earnings announcement.
Operational updates provided a view of where that capital is going. At the Willow development in Alaska, the company said more than 75% of the module fabrication work was complete and maintained its target of first oil in early 2029. The schedule remains a forward-looking expectation, and completing fabrication does not by itself mean the project is ready to begin production.
Elsewhere, ConocoPhillips reported that the Surmont Pad 104W-B development in Canada began production ahead of schedule and under budget. In the Permian Basin, it said completion crews achieved 15% more pumping hours than the prior-year average, an efficiency measure that can help reduce the time needed to bring wells online. The company also expanded its portfolio of contracted liquefied natural gas offtake to 13 million metric tons per year.
Those developments could support future cash generation, but the quarter demonstrated how strongly results can still move with commodity prices and production disruptions. ConocoPhillips’ larger dividend will begin with the December payment; its next reported production and cash-flow figures will show how much of the stronger third-quarter earnings performance carries into the final months of 2026.
More from Investing
Latest News
View all news- EIA Finds U.S. Refiners Shifting Production Toward Diesel and Jet Fuel
- U.S. Productivity Rises 3.6% in Q3 as Unit Labor Costs Fall 0.7%
- U.S. Employers Announce 43,994 Job Cuts in October, Down 71% Year Over Year
- U.S. Weekly Jobless Claims Fall to 189,000
- U.S. Private Employers Add 86,000 Jobs in October, ADP Reports
