
Mission Critical Group Closes Preferred Investment Led by Liberty Mutual Investments
Invesco Senior Secured Management, Aventail Capital Group and Brigade Capital Management also joined the preferred investment, whose size and detailed terms were not disclosed.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy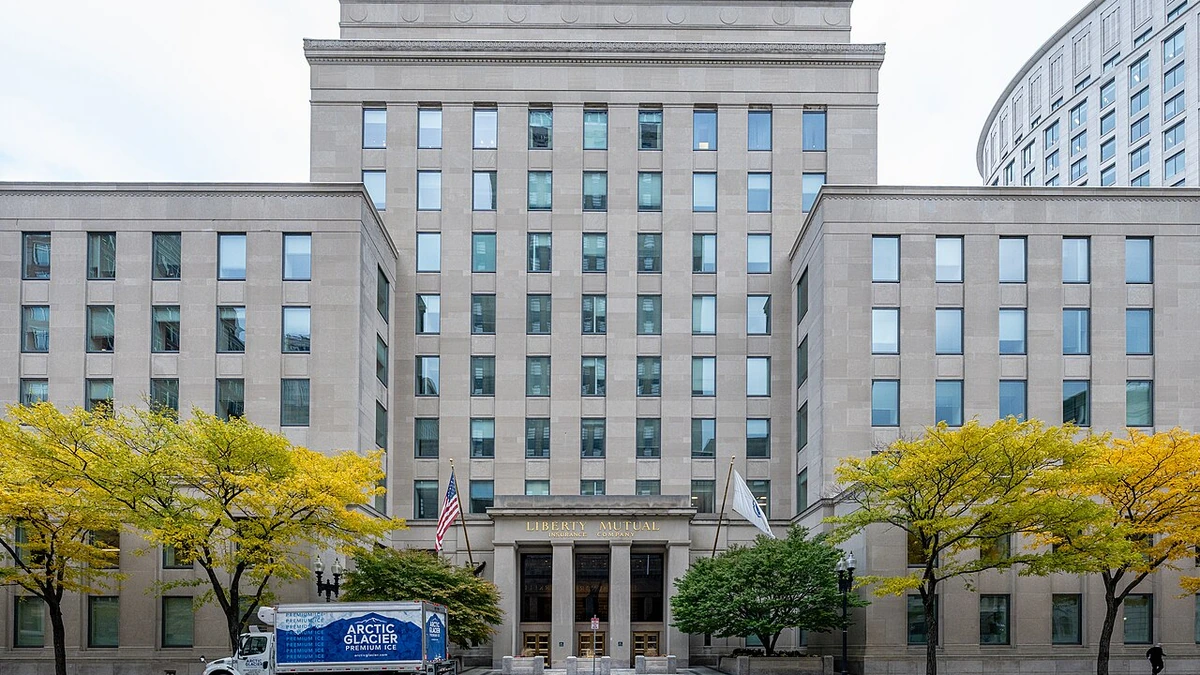
Mission Critical Group has closed a preferred investment led by Liberty Mutual Investments, bringing in new institutional capital as the privately held electrical-infrastructure supplier expands its manufacturing and product reach. Invesco Senior Secured Management, Aventail Capital Group and Brigade Capital Management also participated.
The Frisco, Texas-based company did not disclose the size, pricing or detailed terms of the investment. It also did not identify the exact form of the preferred security or provide ownership percentages, so the public announcement does not establish how the new capital changes MCG’s ownership or what economic rights accompany the investment.
MCG remains a portfolio company of Emerald Lake Capital Management, the private equity firm that helped build the platform. In its September 18 announcement, MCG said the new investor group is backing its growth strategy as demand rises for electrical infrastructure serving data centers, manufacturing plants and energy facilities.
Liberty Mutual’s infrastructure team led the investment
Liberty Mutual Investments, the investment arm of Liberty Mutual Group, led the financing through its Energy & Infrastructure team. MCG said Liberty Mutual Investments manages more than $130 billion of long-term capital globally on behalf of Liberty. Charley Poole, head of Energy & Infrastructure at the firm, pointed to expanding data center capacity, rising electrical loads and labor scarcity as factors behind the investment thesis.
The mandate fits the areas Liberty Mutual Investments says it is already targeting. Its investment platform lists $3.5 billion of assets under management for Energy & Infrastructure, says the strategy was established in 2015 and records 24 investments in 2025. The group says it looks for opportunities tied to rising power demand, expanding data consumption, decarbonization and aging infrastructure, using fund investments, co-investments and direct investments.
MCG’s business sits directly in the physical power chain that supports those themes. The company designs, manufactures and services equipment including switchgear, e-Houses, power skids, backup power systems and transformers. It says it operates more than 18 manufacturing facilities in the United States and serves technology, manufacturing, healthcare and energy customers across North America.
The preferred structure gives MCG another source of institutional capital, but the announcement leaves the economics largely private. It does not state the amount invested by Liberty Mutual Investments or the other participants, the security’s priority relative to existing owners and lenders, or whether it carries dividend, conversion, redemption or governance provisions. Those omissions matter because the label “preferred investment” can cover materially different financing structures.
MCG has been building scale through acquisitions and manufacturing
The new capital arrives after a rapid expansion of MCG’s operating footprint. In April, the company acquired TxLa Systems, a Texas manufacturer of electrical switchgear and modular systems. MCG said TxLa brought 400 employees, multiple Texas facilities and additional capacity for switchgear, e-houses and modular systems, while also bringing part of the supply chain in-house.
That acquisition was supported by a sizeable debt package. PGIM disclosed that it served as a joint lead arranger on a $547 million senior secured credit facility in April 2026 that allowed MCG to fund the TxLa acquisition and refinance debt facilities. The facility included a term loan, a delayed-draw term loan and a revolving credit facility. The newly announced preferred investment is separate from that earlier debt financing, and MCG has not disclosed how the proceeds will be allocated among specific projects or acquisitions.
MCG continued adding capabilities through the summer. In June, it brought several legacy operating brands under the Mission Critical Group name. In July, MCG entered into a merger agreement with CORE Transformers, a supplier of engineered-to-order transformers for data center, grid and industrial applications. In August, it acquired Anchor Automation, adding industrial automation, controls and connected-services capabilities to its field-service offering.
Two days before announcing the preferred investment, MCG and Hitachi said they had signed a memorandum of understanding for a strategic partnership focused on data center solutions. The companies plan to work on modular data center projects, cross-sell energy products and develop offerings that connect Hitachi’s digital technologies with MCG’s modular power equipment. The timing places the new financing alongside an operating strategy aimed at serving larger and more complex power requirements.
Undisclosed terms limit what investors can infer
The financing announcement is notable for the caliber and number of institutional participants, but it provides little information for estimating MCG’s valuation or the return profile expected by the new investors. There is no disclosed investment amount, valuation, maturity, coupon or dividend rate, conversion formula, liquidation preference, board right or exit timetable. As a result, the release supports a conclusion that MCG has added preferred capital, but not a conclusion about how expensive that capital is or how much ownership it represents.
The company also stopped short of assigning the proceeds to a named factory, acquisition or product program. Chief Executive Jeff Drees tied the investment to MCG’s broader growth strategy and to demand for scalable power infrastructure, but the announcement did not provide a project-level use of proceeds. That distinction is important because MCG is simultaneously expanding manufacturing capacity, adding businesses and pursuing product partnerships.
Advisers on the financing included Jefferies as exclusive placement agent and Kirkland & Ellis as legal adviser to MCG. Paul Hastings served as counsel, BDO was financial adviser to Liberty Mutual Investments, and Davis Polk & Wardwell served as placement-agent counsel. Emerald Lake remains MCG’s private equity sponsor, and the company continues to describe itself as a portfolio company of the firm after the preferred investment closed.
More from Investing
Latest News
View all news- Berkshire Names Howard Buffett Chairman as Warren Buffett Becomes Chairman Emeritus
- Independent Fed Review Says Supervisors Knew or Should Have Known of SVB Risks by March 2022
- August Payrolls Rise in Four States as Jobless Rates Fall in Eight States and D.C.
- DWS-Advised RREEF Property Trust Board Approves Complete Liquidation Plan
- Progressive August Net Income Falls 22% as Combined Ratio Rises to 89.3
