SEC and French Regulator Sign Oversight Agreement for Cross-Border Investment Advisers
The SEC will resume processing new and pending U.S. registration applications from French asset managers supervised by the AMF, under a new cross-border oversight pact.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy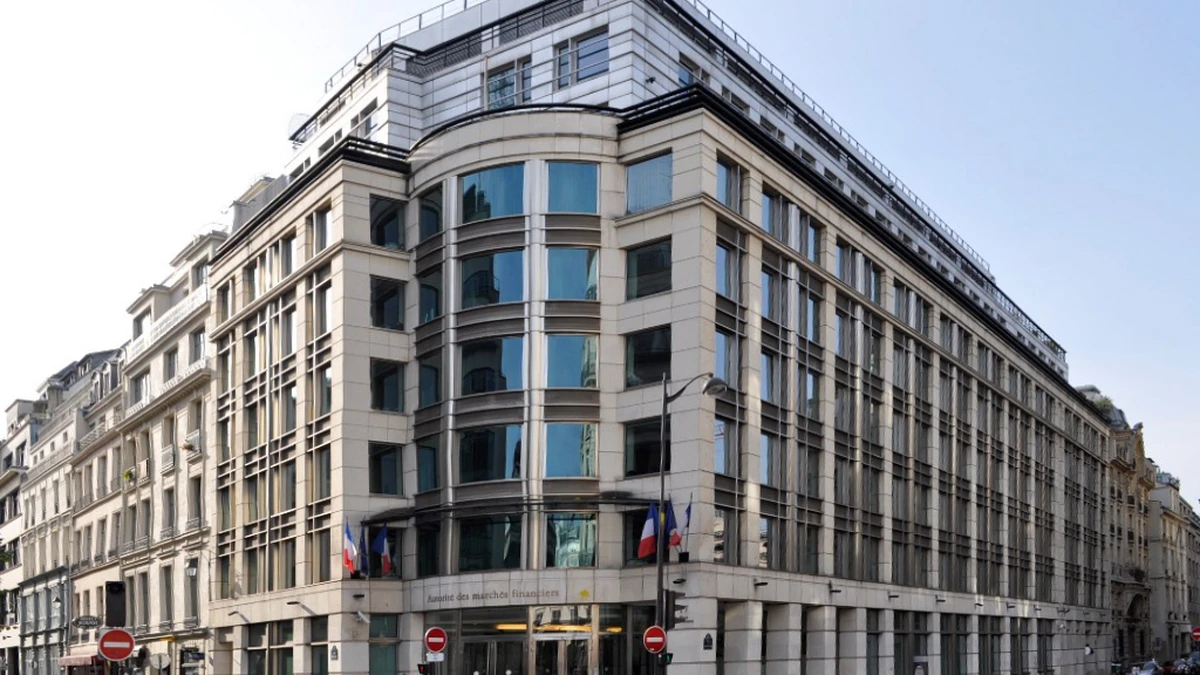
The U.S. Securities and Exchange Commission and France’s Autorité des Marchés Financiers (AMF) have signed a supervisory cooperation agreement for financial firms operating across the two countries, with the SEC saying it will resume processing registration applications from French asset managers seeking to work in the United States.
Announced on October 20, 2026, the memorandum of understanding gives the agencies a framework for consultation and sharing supervisory information about certain investment advisers, investment companies and investment service providers. The immediate practical change is on the U.S. registration side: new and pending applications from AMF-supervised asset management companies will be processed in light of the arrangement.
The announcement does not mean those applicants have been registered, or that French authorization can substitute for U.S. approval. Neither regulator identified affected firms or disclosed how many applications are awaiting a decision. Those limits matter when assessing what the agreement changes now, rather than what it might eventually allow firms to do.
SEC to resume reviewing French adviser applications
French firms seeking a U.S. advisory business answer to a different securities regulator when they apply for American registration. Home-country oversight can give the SEC important context about the applicant, but it does not resolve the U.S. filing on its own. The two agencies described the agreement as facilitating registration and ongoing supervision of AMF-supervised asset managers that want to conduct business in the United States.
In its October 20 announcement, the SEC explicitly said it would resume processing those applications. That is a change in administrative handling, not a blanket exemption from registration standards. A prospective adviser must still satisfy the requirements that apply to its business and obtain an effective SEC registration where registration is required.
The ordinary registration process is more than a request to enter the market. Applicants submit Form ADV electronically through the Investment Adviser Registration Depository, or IARD. Part 1 asks for details about a firm’s business, ownership, control and disciplinary history. Part 2 supplies information about its services, fees, business practices and conflicts of interest, providing material that clients and potential clients can review.
The new agreement sits alongside that process rather than replacing it. A French company might be authorized and supervised at home, yet the SEC still needs to assess its U.S. filing under American securities law. The regulators did not announce a special fast-track timetable or say that any particular pending application will be approved.
Responsibilities do not end when an adviser’s registration becomes effective. SEC guidance requires firms to keep their regulatory information up to date, including disclosures about business practices and potential conflicts. The new cooperation arrangement covers supervision as well as applications, so an approved French manager could remain the subject of information exchanges between the agencies while conducting its U.S. business.
A channel for ongoing supervision across borders
Beyond registrations, the memorandum addresses a problem that arises when a financial business is active in more than one jurisdiction: one regulator may supervise a firm whose management, records or regulated activities also fall within another authority’s reach. The SEC and AMF say the arrangement is intended to support consultation, cooperation and information exchanges tied to their oversight responsibilities.
Its stated scope includes investment advisers and investment companies regulated by the SEC, as well as investment service providers supervised by the AMF, where the relevant businesses operate in the United States and France. That is broader than the French applications singled out in the announcement. The applications are the near-term action, while the supervision framework can matter after a firm begins operating.
In practice, the importance of supervisory cooperation is not limited to a single registration decision. A regulator examining a cross-border firm may need a fuller view of its activities than domestic filings alone can provide. Sharing information and consulting the counterpart authority can help the agencies understand how a firm is organized and supervised on either side of the Atlantic. The announcement, however, does not specify individual cases or investigative steps.
The SEC has long drawn a distinction between routine supervisory cooperation and enforcement cooperation. In a 2013 explanation of arrangements with European regulators, it described supervision as continuing consultation about regulated entities, in contrast with exchanging investigative information about suspected securities-law violations. That distinction helps define Tuesday’s news: an avenue for continuing oversight, not an enforcement case against a particular firm.
Separate U.S. and French regulatory obligations remain
The French regulator already authorizes and supervises portfolio asset management companies under its own framework. Depending on their activities, such firms may manage investment funds, provide portfolio management services or offer investment advice. The SEC, meanwhile, administers the U.S. adviser registration process and supervises firms that fall within its jurisdiction. The new memorandum connects these oversight responsibilities without making them identical.
That is why the agreement should not be read as a mutual-recognition license or a general passport for French firms. It does not say that an AMF-authorized manager can automatically offer every service in the United States, nor does it change the separate rules governing investment products, marketing or client relationships. Each firm’s permissions still depend on the relevant laws and the business it proposes to conduct.
For investors, registration remains a useful distinction. Information about SEC-registered advisers is available through the agency’s public disclosure system, including Form ADV records. The existence of a cooperation memorandum does not by itself certify a manager’s investment performance or remove the need to understand its fees, services and disclosed conflicts.
The agencies also provided no estimate of the amount of assets that might become subject to additional cross-border management, no count of French firms expecting to file, and no projection of new U.S. business. Claims that the agreement will produce a particular amount of investment or a surge in approvals would go beyond what either authority announced.
The concrete next development is the SEC’s handling of new and outstanding applications from AMF-supervised companies. As those reviews proceed, an effective registration or a public filing for an individual adviser will offer a firmer measure of progress than the signing announcement alone.
More from Investing
Latest News
View all news- Pending U.S. Home Sales Drop 7.3% in September as All Four Regions Decline
- U.S. Housing Starts Fall 5.2% in September to 1.22 Million Annual Rate
- Philadelphia Fed Survey Shows Improving Service-Sector Activity but Persistent Cost Pressures
- NCUA Proposes Easing Three Credit Union Rules, Including Investment Reserve Requirements
- Instacart Agrees to $5 Million Settlement Over U.S. Hiring Discrimination Allegations