THOR Industries Reports Fiscal Q4 Results as RV Market Faces Continued Demand Pressure
Fiscal fourth-quarter sales fell 8.4% to about $2.31 billion and net income dropped to $40.8 million as affordability concerns and higher material costs weighed on the RV maker.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy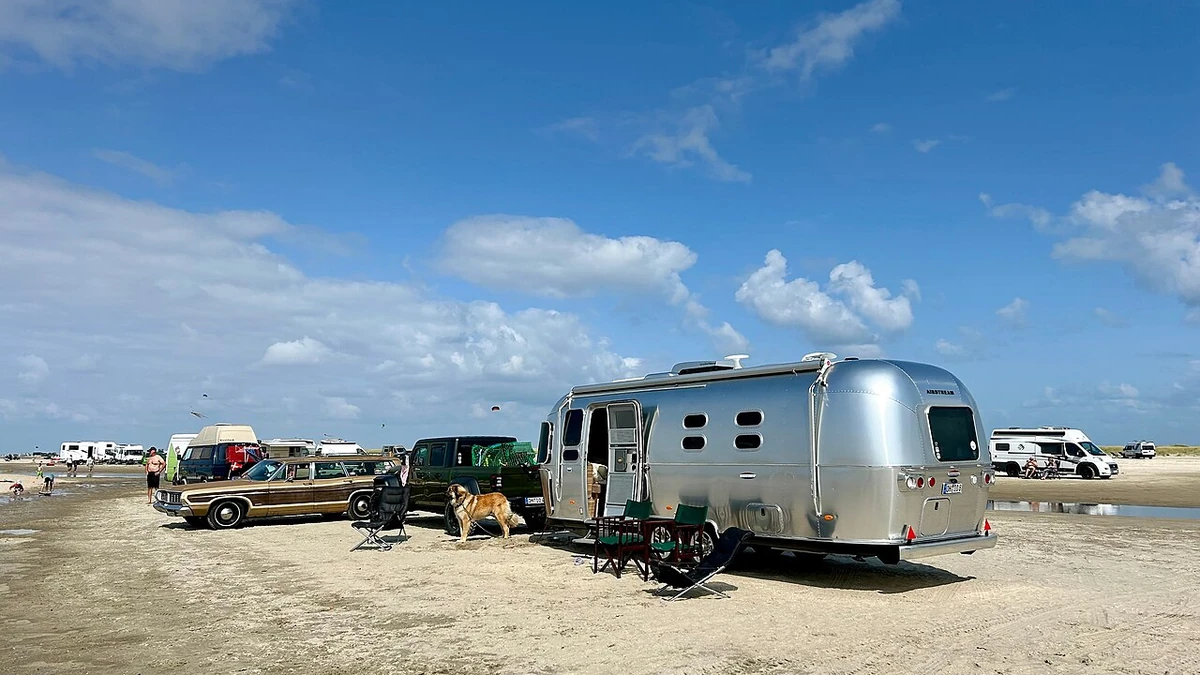
THOR Industries finished fiscal 2026 with a sharply weaker fourth quarter as soft recreational-vehicle demand and higher costs continued to weigh on profitability. Net sales for the three months ended July 31 fell 8.4% from a year earlier to about $2.31 billion, while net income dropped to $40.8 million from $125.8 million. Diluted earnings per share fell to $0.78 from $2.36.
The decline in earnings was much steeper than the sales drop, underscoring the pressure on margins in a market where manufacturers have been trying to protect consumer price points while absorbing higher material costs. Chief Executive Bob Martin said persistent interest-rate pressure, elevated fuel costs and inflation had continued to strain household budgets during the key selling season, leaving the retail market weaker than THOR had expected earlier in the year.
THOR had scheduled its fiscal fourth-quarter release for September 22 and said it would publish the earnings release, investor questions and answers, and a slide presentation on its investor website. The quarter closed a fiscal year in which the company repeatedly adjusted its expectations as North American consumer confidence and dealer ordering remained subdued.
Profit Falls Faster Than Fourth-Quarter Sales
The year-over-year comparison was especially difficult on the bottom line. In fiscal 2025’s fourth quarter, THOR reported $2.52 billion in net sales, a 14.7% gross margin, $125.8 million in net income and diluted earnings of $2.36 per share. This year’s $2.31 billion of quarterly sales represents a meaningful decline, but the fall in net income to $40.8 million shows how much more severe the pressure became below the revenue line.
That pattern was already visible before the final quarter. For the three months ended April 30, THOR posted $2.78 billion in sales, down 3.9% from the prior year, while gross margin narrowed to 12.8% from 15.3%. Third-quarter net income fell 28.1% to $97.2 million and diluted earnings per share declined to $1.86 from $2.53.
In June, management reduced its full-year fiscal 2026 earnings guidance to $3.30 to $3.80 per diluted share from $3.75 to $4.25, even as it kept the sales outlook at $9.0 billion to $9.5 billion. THOR also changed its gross-margin assumption to a decline at the midpoint of guidance. The company tied that revision to prolonged pressure on consumer confidence, cautious dealer ordering, and tariff-related and inflationary cost increases rather than to a single-quarter disruption.
The economics of the RV business make those pressures important on both sides of the income statement. RVs are discretionary purchases, often financed, so borrowing costs and household confidence can affect whether consumers enter the market or delay replacing an existing unit. At the same time, manufacturers and dealers have limited room to pass every cost increase through to buyers when affordability is already a constraint. THOR has emphasized production discipline and efforts to keep pricing competitive as it works through that tension.
Towable RV Weakness Remained the Main Pressure Point
THOR’s results have not been uniformly weak across its portfolio. The clearest strain during the spring selling season was in North American Towable RVs, a segment that includes travel trailers and fifth wheels. In the fiscal third quarter, towable sales fell 24.6% to $881.8 million and unit shipments declined 25.0%. Gross margin in the segment fell to 10.2% from 14.9%, while its order backlog dropped 39.1% to $386.0 million at April 30.
The company’s third-quarter earnings release filed with the SEC attributed the towable sales decline to a difficult retail environment and cautious dealer ordering. It also said the 470-basis-point drop in the segment’s gross margin reflected lower sales, a higher material-cost percentage and an unfavorable product mix. Those figures established the core problem heading into the quarter that ended July 31: demand was weak enough to limit volume, while cost pressure made lower volume more painful for profitability.
Other parts of THOR’s business held up better. North American Motorized sales increased 7.7% in the third quarter to $717.7 million as shipments rose 9.1%, although that segment’s gross margin still fell 170 basis points. European RV sales rose 11.8% to $987.6 million, helped in part by currency movements, but its gross margin also declined from the prior-year period. The mix helped keep consolidated revenue from falling as sharply as towable sales, yet it did not eliminate the broader margin problem.
Dealer behavior is another part of the demand picture. THOR has been managing wholesale production against retail sales rather than pushing excess units into the channel. That approach can restrain factory shipments when dealers are cautious, but it reduces the risk of building inventories that later require aggressive discounting. The company entered the final quarter saying wholesale and retail volumes were roughly balanced in its full-year assumptions and that production would remain tied closely to market conditions.
THOR Expects a Flat Retail Market in Fiscal 2027
Management is not signaling a quick demand rebound as the new fiscal year begins. Chief Operating Officer Todd Woelfer said THOR expects the retail environment in fiscal 2027 to be relatively flat compared with fiscal 2026, with many of the same near-term macroeconomic pressures still affecting consumers. The company has not yet issued its formal fiscal 2027 financial guidance and plans to provide that outlook later in the fall.
THOR is also changing how parts of its North American RV operations are organized. Earlier in 2026, it set out a structure that groups Jayco, Entegra, Open Range and Heartland with Tiffin Motorhomes, while Thor Motor Coach is paired with Keystone, Dutchmen and CrossRoads. Airstream and KZ continue to operate independently. By the end of the third quarter, management said initial assessments were largely complete and that initiatives involving sourcing, operating processes and enterprise data were moving forward.
The aim is to improve efficiency and protect margins without relying on a broad market recovery to do the work. THOR has also been expanding its owned-supplier businesses, managing production to retail demand and looking for savings across its manufacturing footprint. Those efforts can influence costs and execution, but the near-term earnings path will still depend heavily on how consumers respond to financing costs, fuel prices and pressure on household budgets.
The next major financial marker will be THOR’s fiscal 2027 guidance, which management plans to issue later in the fall. That outlook should show whether the company expects internal cost and operating measures to offset a retail market that it currently sees as roughly flat.
More from Investing
Latest News
View all news- Vertex Reports Positive Inaxaplin Data, Completes AMPLITUDE Enrollment
- Palo Alto Networks Launches Agentic AI Security Service Using Anthropic and OpenAI Models
- Fed’s Jefferson Says Discount-Window Upgrades Can Support Treasury-Market Liquidity
- New York Fed’s Williams Says Rate-Control Toolkit Is Working Well in Ample-Reserves Regime
- On Targets High-Teens Sales Growth and 22%+ EBITDA Margin by 2029