
U.S. Construction Spending Rises 0.9% in August to $2.20 Trillion Annual Rate
U.S. construction spending rose 0.9% in August to a seasonally adjusted annual rate of $2.203 trillion, led by gains in private residential and nonresidential building.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy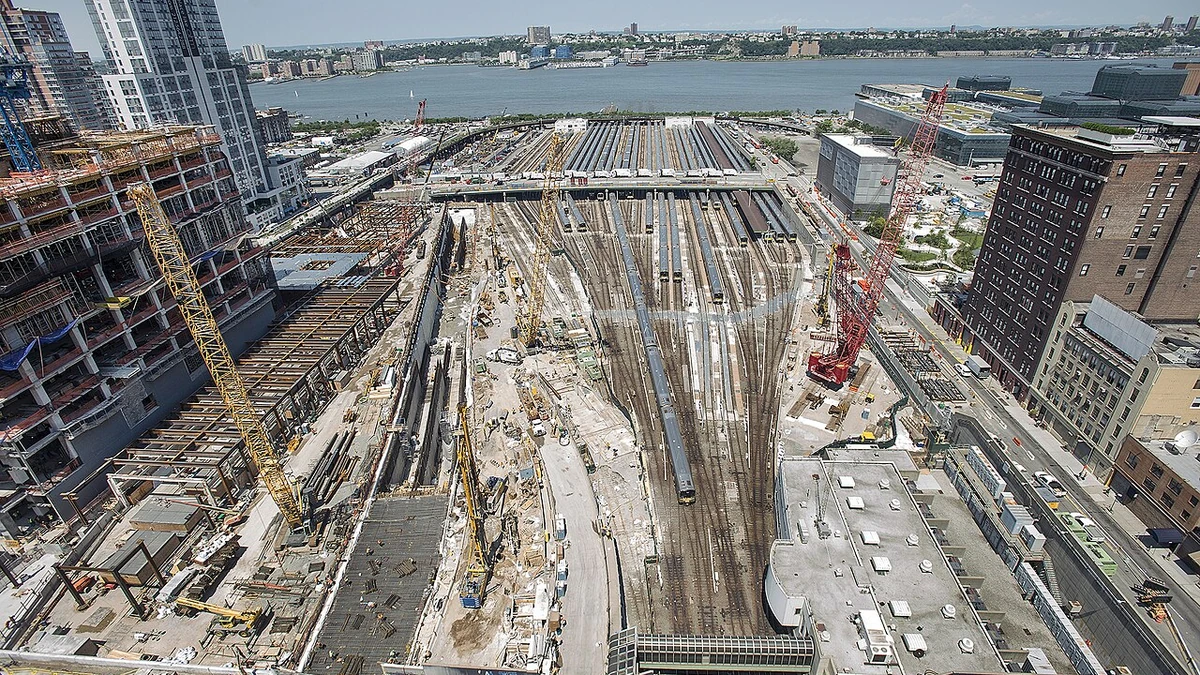
U.S. construction spending rose in August, reversing some of the softer tone seen in the summer and returning the headline figure above a $2.2 trillion annualized pace. The Census Bureau said total construction spending during the month was estimated at a seasonally adjusted annual rate of $2,203.1 billion, up 0.9% from a revised $2,184.5 billion in July.
Even with that monthly increase, spending remained below the level of a year earlier. August activity was 1.7% lower than the $2,242.0 billion annual rate recorded in August 2025. For the first eight months of 2026, total construction spending amounted to $1,450.4 billion, down 3.1% from $1,496.6 billion in the same period a year ago. Those figures show that the sector still faces a mixed backdrop: monthly activity improved, but the year-to-date picture has not fully recovered.
Private construction accounted for most of the August gain
According to the Census Bureau’s August construction spending release, private construction was the main driver of the monthly increase. Spending on private construction reached a seasonally adjusted annual rate of $1,655.3 billion in August, up 1.1% from the revised July estimate of $1,637.7 billion. That means the private side of the market contributed nearly all of the month’s headline improvement.
Within private construction, residential building rose to an annual rate of $882.3 billion, also up 1.1% from July’s revised $872.7 billion. Private nonresidential construction climbed to a $773.0 billion annual rate, a 1.0% increase from the prior month’s revised $765.0 billion. The fact that both residential and nonresidential work moved higher gave the August report a broader base than a gain driven by only one category would have suggested.
That breakdown matters because the construction spending report captures work put in place rather than only new project announcements. A rise in residential spending can reflect ongoing single-family and multifamily projects, improvements and related outlays, while higher nonresidential spending points to continued activity across commercial, industrial and institutional building categories. In other words, the August increase suggests more work was actually being done on sites across the country, not just that plans were being filed.
Public construction rose only slightly
Public construction spending increased much more slowly than private building. The Census Bureau estimated public construction at a seasonally adjusted annual rate of $547.8 billion in August, up 0.2% from the revised July level of $546.8 billion. That is still growth, but it was modest compared with the gains on the private side of the report.
Two of the most closely watched public subcategories barely changed. Educational construction came in at an annual rate of $113.1 billion in August, up 0.1% from a revised $112.9 billion in July. Highway construction was estimated at a $150.6 billion annual rate, also up 0.1% from a revised $150.5 billion. Those small moves suggest state and local infrastructure and institutional projects continued to provide support, but they were not the main reason total spending moved higher in the month.
The split between private and public activity is useful for reading the report. When private construction does the heavy lifting, the data can say more about the strength or weakness of housing, commercial development and business investment. When public construction accelerates, the report often reflects infrastructure programs, school building cycles and government capital plans. August leaned decisively toward the private side, with public spending essentially steady.
Revisions and the annual comparison kept the broader picture mixed
One of the more important details in the release was the revision to July. The previously published July estimate was lower, but the Census Bureau now puts that month at a $2,184.5 billion annual rate. That revision means August’s 0.9% increase came off a stronger base than first reported. It strengthens the month-to-month improvement, but it also means the overall level of spending has not accelerated as dramatically as an unrevised comparison might have implied.
The annual comparison also kept enthusiasm in check. August’s total remained 1.7% below the year-earlier level, and the first eight months of 2026 were down 3.1% from the same stretch in 2025. That indicates the sector has been operating below last year’s pace even though the latest monthly report showed resilience. For builders, suppliers, equipment companies and investors tied to construction demand, that is a reminder that one solid month does not by itself erase a softer trend over a longer horizon.
Still, the composition of the August increase could be read as encouraging. Private residential construction rose alongside private nonresidential work, which suggests the pickup was not confined to a single corner of the market. If that pattern continues, construction spending could stabilize further in coming months. For now, though, the August report presents a balanced message: activity improved and reclaimed a $2.20 trillion annual rate, but the sector as a whole remains below where it stood a year earlier.
More News
Latest News
View all news- PHINIA Completes stoba Group Acquisition, Broadening Semiconductor and Aerospace Reach
- National Fuel Completes $2.62 Billion Acquisition of CenterPoint’s Ohio Gas Utility
- McCormick Sales Jump 17% in Q3 as Company Reaffirms 2026 Outlook
- Italy’s Unemployment Rate Rises to 6.2% as Jobless Count Increases by 48,000
- Inseego Completes Acquisition of Nokia’s Fixed Wireless Access Business
