
U.S. Trade Deficit Widens 13.7% to $105.6 Billion in August as Imports Surge
Imports rose $17.2 billion to $420.8 billion while exports increased $4.5 billion to $315.2 billion, widening the monthly gap even as the year-to-date deficit remained below 2025.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy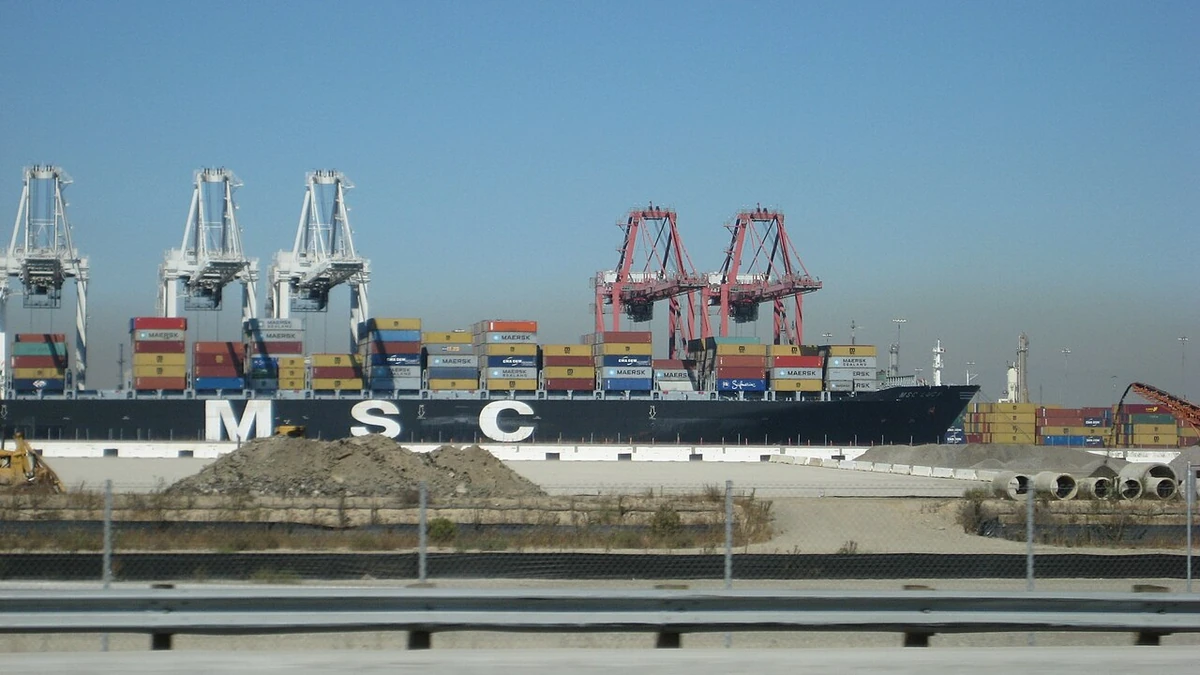
The U.S. trade deficit widened 13.7% in August to $105.6 billion as imports rose much faster than exports, reversing part of the improvement seen earlier in the year. The monthly gap increased by $12.7 billion from a revised $92.8 billion in July.
Imports climbed $17.2 billion, or 4.3%, to $420.8 billion. Exports also increased, but by a smaller $4.5 billion, or 1.4%, to $315.2 billion. The result was the largest monthly deficit of the year so far, based on the seasonally adjusted goods-and-services figures released Tuesday.
The Bureau of Economic Analysis and U.S. Census Bureau said the August widening came almost entirely from goods. The goods deficit increased $12.8 billion to $136.6 billion, while the services surplus edged up by less than $0.1 billion to $31.0 billion. The headline statistics are adjusted for seasonality but not for price changes.
Goods imports account for nearly all of the increase
Imports of goods rose $17.2 billion on a balance-of-payments basis to $342.2 billion in August. Services imports were essentially flat at $78.5 billion, increasing by less than $0.1 billion. That split makes the source of the wider trade gap unusually clear: the monthly change came from physical goods rather than a broad increase across both goods and services.
The Census-basis detail shows industrial supplies and materials as the largest contributor to the import increase. Imports in that category rose $9.1 billion, including a $3.3 billion increase in crude oil and a $3.1 billion increase in nonmonetary gold. Capital-goods imports increased another $6.2 billion. Within capital goods, semiconductor imports rose $2.4 billion and other industrial machinery increased $1.3 billion, while computer accessories fell $1.6 billion.
Exports moved higher as well, but the increase was not large enough to offset the jump in imports. Goods exports rose $4.4 billion on a balance-of-payments basis to $205.7 billion, while services exports increased by less than $0.1 billion to $109.5 billion.
On a Census basis, industrial supplies and materials exports increased $6.3 billion. Nonmonetary gold rose $2.3 billion, crude oil increased $2.0 billion and fuel oil was up $1.2 billion. Capital-goods exports added $1.3 billion. Those gains were partly offset by a $2.2 billion decline in consumer-goods exports, including a $2.4 billion drop in pharmaceutical preparations.
The mix is important because the headline $105.6 billion deficit combines several very different trade flows. August saw higher imports of energy, gold and investment-related goods at the same time that U.S. exports of industrial supplies also increased. The data establish that imports grew faster than exports during the month, but the release does not attribute that pattern to a single policy or economic cause.
A sizable July revision raised the comparison base
August’s increase was measured against a July deficit that was revised materially higher. The government had previously reported a July goods-and-services deficit of $88.6 billion. The latest release revised that figure to $92.8 billion, a $4.2 billion increase in the estimated gap.
The revision came primarily from imports. July goods imports were revised up $4.4 billion, while services imports were revised down $0.2 billion. Goods exports were revised up $0.2 billion and services exports were revised down by the same amount, leaving total exports effectively unchanged. The higher July import estimate therefore widened the revised July deficit before the August comparison was calculated.
Even using that higher base, the deficit expanded another 13.7% in August. The three-month moving average also deteriorated. The average goods-and-services deficit for the three months ending in August increased $9.9 billion to $89.9 billion. Average imports rose $8.3 billion to $404.3 billion, while average exports fell $1.6 billion to $314.4 billion.
That three-month measure helps separate the latest move from a single volatile month. It still shows a widening gap into August, although it remains a different measure from the monthly deficit and should not be read as an additional $9.9 billion deterioration in August itself.
The year-to-date deficit is still lower than in 2025
Despite the sharp August increase, the cumulative trade deficit through the first eight months of 2026 remained below the comparable period last year. The year-to-date goods-and-services deficit was down $138.2 billion, or 19.9%, from the same period of 2025. Exports increased $267.7 billion, or 11.8%, while imports rose $129.5 billion, or 4.4%.
Price-adjusted goods data also showed a wider August gap. In 2017 dollars and on a Census basis, the real goods deficit increased $8.7 billion, or 8.2%, to $114.7 billion. Real goods exports rose $1.9 billion to $153.0 billion, while real goods imports increased $10.7 billion to $267.7 billion. That means the widening was not solely a result of higher nominal prices, although the real-goods measure is not identical to the broader goods-and-services balance.
Gold is another reason to avoid drawing a direct line from the headline trade number to gross domestic product. BEA notes that when these trade statistics are incorporated into the national accounts, exports and imports of nonmonetary gold are replaced with an adjustment based on the difference between domestic production and industrial use. August contained sizable increases in both gold imports and gold exports, so the monthly trade release and the treatment used in GDP accounting are not mechanically identical.
The August report therefore delivers two different signals. The monthly trade gap widened sharply because goods imports increased far more than exports, and the recent three-month average also moved in the same direction. At the same time, the cumulative deficit for 2026 remained substantially below its level in the first eight months of 2025 because exports have grown faster than imports on a year-to-date basis.
The next U.S. international trade report, covering September, is scheduled for November 4. It will show whether August’s import-heavy widening persisted into the following month or proved to be a shorter-lived shift in the composition and timing of trade flows.
More News
Latest News
View all news- Google, Constellation Sign 3.59-GW PJM Power Deal, With $4.3 Billion-Plus Going to Nuclear Uprates
- RPM Posts Record $2.22 Billion Fiscal Q1 Sales, Narrows FY2027 Outlook
- Type One Energy Raises $200 Million Series B to Advance Tennessee Fusion Project
- MIAX Hits Record 17.1% YTD U.S. Options Share as ADV Rises 22%
- Informa to Buy Clarion for £2.24 Billion, Plans £940 Million Equity Raise and Taylor & Francis Separation
