
Bank of England Holds Rate at 3.75% in 6-3 Vote, Sets Gilt Unwind Plan
Three MPC members backed a rise to 4%, while the Bank set a multi-year path to unwind £368 billion of gilts held for monetary policy purposes by the end of 2034.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy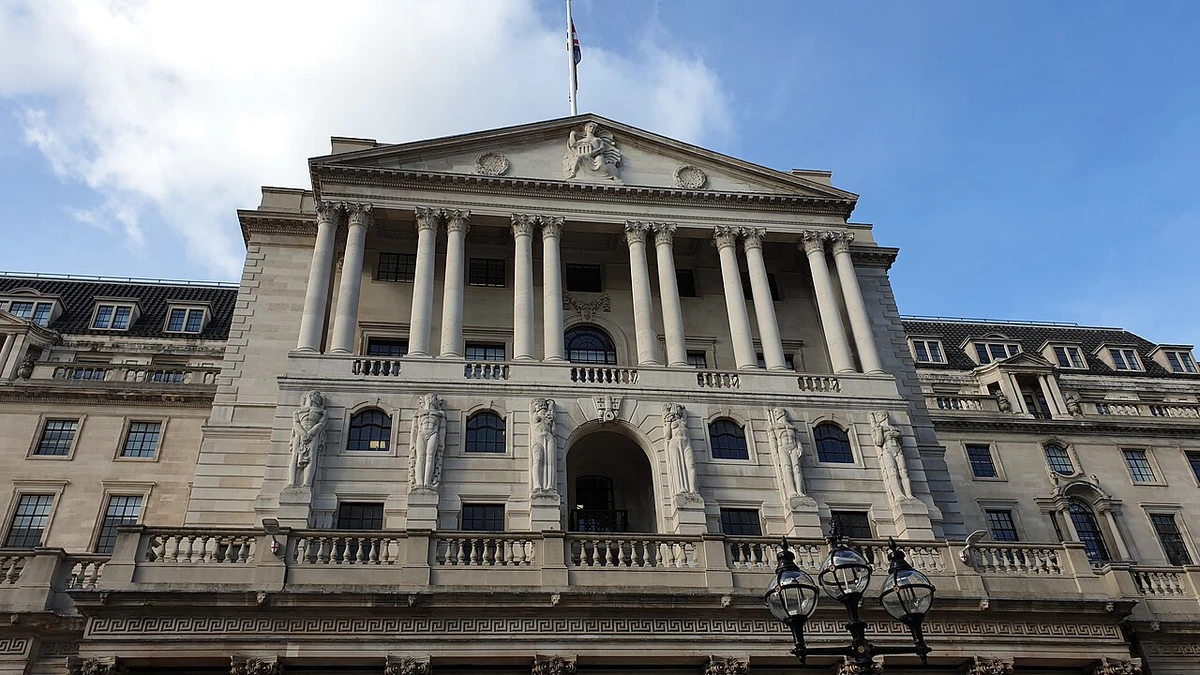
The Bank of England kept Bank Rate at 3.75% on Thursday, with six members of the Monetary Policy Committee voting to hold and three preferring a quarter-point increase to 4%. The decision left the benchmark rate unchanged and came as policymakers judged that risks to the inflation outlook had shifted further to the upside.
The hold was paired with a change in the Bank’s approach to quantitative tightening. The MPC unanimously agreed on a multi-year plan to unwind the remaining £368 billion of gilts held for monetary policy purposes, after setting aside £120 billion of long-dated bonds that will be retained to help back banknote issuance. The monetary-policy portfolio is expected to fall by an average of £46 billion a year and reach zero by the end of 2034.
Three MPC members wanted Bank Rate raised to 4%
According to the Bank’s September policy summary and meeting minutes, Andrew Bailey, Sarah Breeden, Swati Dhingra, Clare Lombardelli, Dave Ramsden and Alan Taylor voted to keep Bank Rate at 3.75%. Megan Greene, Catherine L. Mann and Huw Pill voted against the proposition and preferred an increase to 4%.
The split reflected growing concern about energy-driven inflation without a consensus that another rate increase was already necessary. The Bank said the prolonged conflict in the Middle East had pushed crude and refined energy prices higher and kept them volatile. Based on prices at the close on September 14, Brent crude was around $106 a barrel and UK wholesale gas around 207 pence per therm. The MPC said those moves had worsened the near-term inflation outlook and increased the risk that higher prices could feed into wage and price-setting.
UK consumer price inflation rose to 3.1% in August from 2.9% in July, according to the Office for National Statistics. Transport, particularly motor fuels, made the largest upward contribution to the change in the annual rate. The MPC said about 0.7 percentage points of the 1.1 percentage point overshoot above the 2% target reflected the direct effects of energy prices, mostly motor fuels.
There was still little evidence that the energy shock had generated material second-round effects in wages and prices. Services inflation was 3.4% in August, unchanged from July and down from 4.5% in March, while private-sector regular pay growth had continued to ease. The Bank also pointed to a softer labour market and tighter borrowing conditions as forces that should restrain inflation over time.
The three members seeking a rate increase put more weight on the risk that those restraints would prove insufficient. They argued that the longer-running energy shock, stronger-than-expected activity and the possibility of renewed pressure from food and other global supply factors raised the chance that inflation expectations could become less well anchored. The majority instead judged that the current level of Bank Rate, together with tighter financial conditions, was still providing enough restraint to hold while more evidence emerged.
Quantitative tightening moves to a multi-year timetable
The balance-sheet decision marked a shift from the Bank’s recent practice of setting the pace of quantitative tightening one year at a time. The MPC said a multi-year plan would make the remaining unwind more gradual and predictable. It also set a high bar for changing the plan, although the Bank retained scope to respond if Bank Rate alone proved insufficient to meet the inflation target or if financial markets became severely distressed.
The Asset Purchase Facility held about £488 billion of gilts when the MPC met. Of that total, £120 billion of the longest-dated securities will be retained by the Bank to help back current and future banknote issuance. That leaves £368 billion held for monetary policy purposes to be removed from the balance sheet.
The Bank plans to let about £222 billion of gilts mature naturally through 2034. The remaining roughly £146 billion will be sold at an annualised pace of £20 billion a year. Combining those active sales with maturities gives an average annual reduction of about £46 billion through September 2034, when the monetary-policy gilt stock is expected to reach zero.
The distinction matters because the Bank is not planning to eliminate every gilt in the Asset Purchase Facility. The £120 billion retained for banknote backing sits outside the £368 billion monetary-policy stock targeted for full unwind. The Bank’s September market notice said the retained securities consist of part of its holding of the 1.75% 2049 gilt and all of its gilts maturing after that point.
The new path follows a substantial reduction already completed since quantitative tightening began. The Bank said its gilt holdings had fallen from a peak of £895 billion in February 2022 to £488 billion in September 2026. Over the previous 12 months alone, the stock held for monetary policy purposes declined by £70 billion, including £21 billion through active gilt sales.
Bank explores a different route for future gilt sales
The operational side of the plan is not fully settled. The Bank has been discussing with HM Treasury and the Debt Management Office a model under which the remaining gilts designated for sale could be sold to the government rather than through the Bank’s existing auction process. Under that approach, the Treasury would instruct the DMO to buy gilts from the Asset Purchase Facility at market prices under a predefined schedule.
The Bank said it will review progress before April 2027. If the model is adopted, implementation could be incorporated into the DMO’s annual financing remit. The Bank plans to publish operational details by April 2027 regardless of the route chosen, and its own APF gilt auctions will pause in the meantime.
For monetary policy, the September decision leaves the immediate focus on whether higher energy costs broaden into more persistent domestic inflation. The MPC said activity had been slightly stronger than expected and judged the balance of inflation risks to be more tilted to the upside than in July. At the same time, it continued to see slack in the labour market and higher borrowing costs as forces working in the opposite direction.
The next scheduled MPC decision is due on November 5. By then, policymakers will have another inflation reading and more evidence on energy prices, wage-setting and the degree to which the latest rise in headline inflation is spreading beyond its direct energy components.
More News
Latest News
View all news- Google, Constellation Sign 3.59-GW PJM Power Deal, With $4.3 Billion-Plus Going to Nuclear Uprates
- RPM Posts Record $2.22 Billion Fiscal Q1 Sales, Narrows FY2027 Outlook
- Type One Energy Raises $200 Million Series B to Advance Tennessee Fusion Project
- MIAX Hits Record 17.1% YTD U.S. Options Share as ADV Rises 22%
- Japan’s 10-Year Government Bond Auction Clears Near 3.10% With a 3.1% Coupon
