
German Home Prices Rise 0.6% as Housing Recovery Remains Uneven
Apartment prices slipped in Germany's seven largest cities even as several regional and rural housing segments recorded gains in the second quarter.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy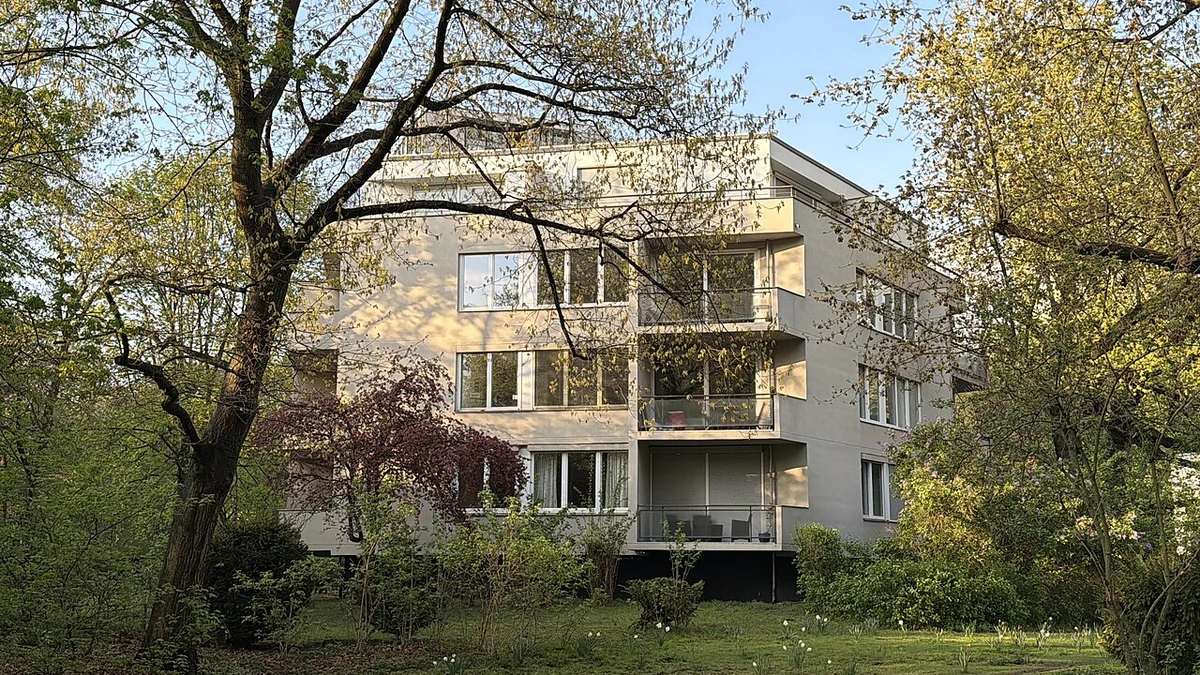
German residential property prices rose modestly in the second quarter, but the national increase concealed sharp differences between property types and locations. The Federal Statistical Office said its house price index was 0.6% higher than a year earlier and 0.3% above the first quarter, based on provisional data.
The figures point to a housing recovery that is still far from uniform. Apartment prices fell in Germany’s seven largest cities, while apartments in other large independent cities became more expensive. Detached and semi-detached houses also showed different patterns across metropolitan and rural areas, leaving the headline national gain as an average of markets moving in different directions.
In its September 24 residential property release, Destatis also revised its first-quarter estimate. The year-over-year increase for the first quarter was lowered to 1.2% from the previously reported 1.4%, a reminder that the latest readings remain subject to revision as additional reports are incorporated.
Big-city apartments lag the national increase
The clearest split appeared inside the largest urban markets. In Berlin, Hamburg, Munich, Cologne, Frankfurt, Stuttgart and Düsseldorf, prices for owner-occupied apartments were 0.4% lower than in the second quarter of 2025. They also fell 0.5% from the first quarter of 2026. Prices for one- and two-family houses in those same metropolitan areas rose 0.7% from a year earlier, but slipped 0.6% quarter over quarter.
Large independent cities outside the top-seven group were stronger. Apartment prices there rose 2.0% from a year earlier and 0.5% from the first quarter. Prices for one- and two-family houses increased 0.7% year over year and 0.9% from the prior quarter. That contrast is important because it shows that Germany’s national housing index is not being driven by a synchronized rebound in the country’s most expensive urban markets.
Rural districts were mixed as well. In densely populated rural districts, apartment prices fell 1.8% from a year earlier and 1.3% from the first quarter, while one- and two-family houses rose 1.0% year over year and 2.5% on the quarter. In sparsely populated rural districts, apartment prices declined 0.6% from a year earlier and 1.4% from the previous quarter. House prices there were 0.4% below the year-earlier level, even though they increased 1.9% from the first quarter.
The dispersion matters more than the small positive national number on its own. Buyers of apartments in the biggest cities faced a different price environment from buyers of houses in many regional markets, and even rural areas did not move in one direction. The data therefore support a picture of stabilization at the national level without showing a broad-based acceleration across Germany.
Financing conditions are still restraining demand
Credit conditions provide another reason to treat the recovery as uneven rather than broad. The Deutsche Bundesbank said in its July Bank Lending Survey that German banks tightened credit standards for household loans used to purchase homes during the second quarter. A net 7% of surveyed banks reported tighter standards, up from 4% in the previous quarter.
Banks also made the terms and conditions on home-purchase loans more restrictive. The Bundesbank said higher lending rates and wider margins on riskier loans contributed to that tightening, while banks pointed to higher funding costs and lower risk tolerance. The survey covered 33 banks and was conducted from June 15 through June 30, with a 100% response rate.
Demand moved in the opposite direction from prices. Banks reported that household demand for home-purchase loans fell to an extent not seen for three years. They cited weaker consumer confidence and the general level of interest rates, while the housing-market outlook weighed on mortgage demand for the first time in two years. The rejection rate for home-purchase loans was little changed, suggesting that the pullback in demand was not simply the result of a sudden jump in declined applications.
The Bundesbank’s August assessment of banking activity was consistent with that survey. It said the recovery in housing-loan inflows that began at the end of 2023 had lost momentum, and that housing loans did not gain further pace in the second quarter compared with the first. That financing backdrop does not establish the cause of any particular regional price move, but it does show that buyers were not operating in an environment of broadly easing credit.
Building permits improve, but the supply signal is still early
Construction approvals have strengthened even as financing demand remains soft. Destatis reported that 22,500 dwellings were approved in July, 1.9% more than a year earlier. From January through July, permits were issued for 148,800 dwellings in new and existing buildings, an increase of 12.9%, or 17,000 units, from the same period in 2025.
Within new residential buildings, 121,200 dwellings were approved during the first seven months, up 13.5% from a year earlier. Approvals for dwellings in single-family houses rose 9.7% to 27,900, while approvals in two-family houses increased 25.0% to 8,900. Multifamily buildings accounted for 79,700 approved dwellings, up 15.1%, making them the largest category in the new-build figures.
Those permit numbers point to a firmer development pipeline, but they should not be read as completed housing supply. Destatis notes that permit statistics can also be affected by delayed reporting from local building authorities, so monthly results can include approvals granted earlier. The housing-price data and permit data are measuring different stages of the market: one tracks prices paid for residential property, while the other records authorization for future construction or conversion work.
For now, Germany’s second-quarter price increase is best read as a modest national rise sitting on top of a highly fragmented market. The next official cross-country comparison comes on October 1, when Eurostat is scheduled to publish comparable second-quarter residential property results for European countries.
More News
Latest News
View all news- Google, Constellation Sign 3.59-GW PJM Power Deal, With $4.3 Billion-Plus Going to Nuclear Uprates
- RPM Posts Record $2.22 Billion Fiscal Q1 Sales, Narrows FY2027 Outlook
- Type One Energy Raises $200 Million Series B to Advance Tennessee Fusion Project
- MIAX Hits Record 17.1% YTD U.S. Options Share as ADV Rises 22%
- Japan’s 10-Year Government Bond Auction Clears Near 3.10% With a 3.1% Coupon
