Case-Shiller U.S. Home-Price Growth Reaccelerates to 1.9% in July
Chicago again led major metros while Seattle posted the largest decline, and national home-price growth remained below the 3.4% inflation rate.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy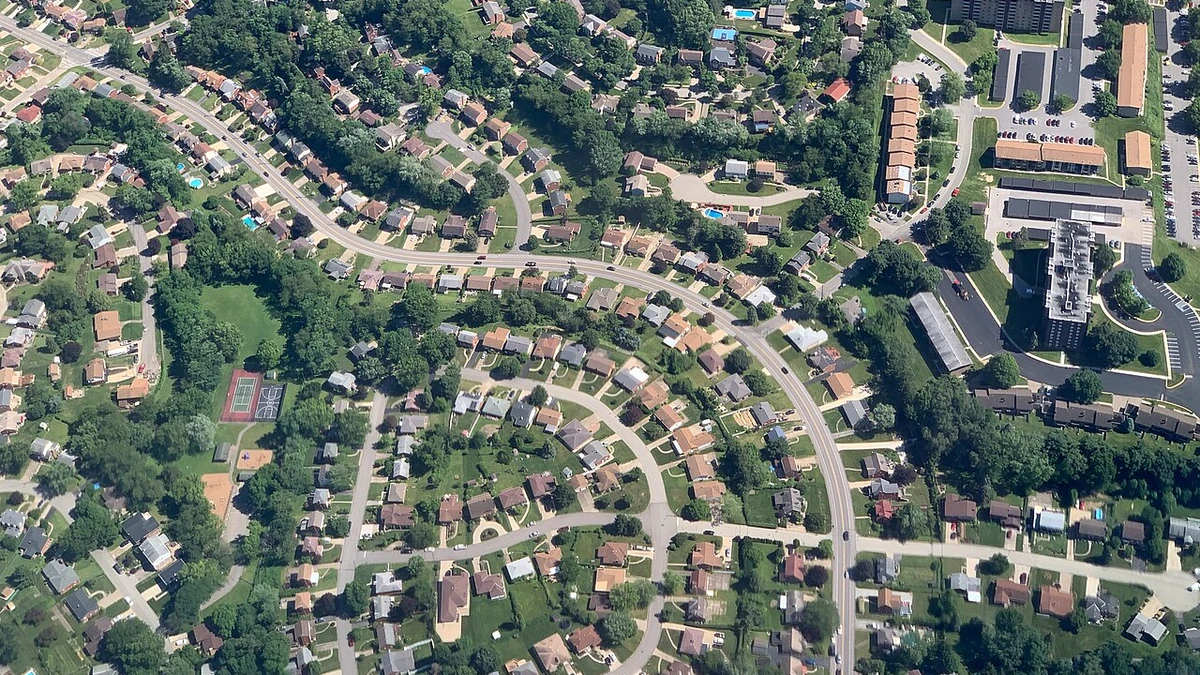
U.S. home-price growth picked up again in July, extending a recent reacceleration even as affordability remained under pressure. The S&P Cotality Case-Shiller U.S. National Home Price NSA Index rose 1.9% from a year earlier, up from a revised 1.6% annual increase in June.
The improvement was also visible in the major-city composites. The 10-City Composite increased 3.4% year over year, compared with 3.0% in June, while the 20-City Composite rose 2.5%, up from 2.2%. Those figures came from S&P Dow Jones Indices’ Case-Shiller home-price series, which tracks repeat sales of single-family homes and is designed to measure changes in home values while controlling for differences in the properties sold.
The national increase was stronger than in the spring, but it still lagged consumer inflation. That leaves the housing picture split between firmer nominal prices and continued erosion in inflation-adjusted terms.
Home prices strengthened, but inflation still ran faster
Consumer prices were 3.4% higher in July than a year earlier, according to the Bureau of Labor Statistics. With the Case-Shiller national index up 1.9%, S&P said home values declined in real terms for a 14th consecutive month. The gap narrowed from June, when inflation was 3.5% and the revised national home-price gain was 1.6%.
That distinction matters for homeowners and prospective buyers. A positive year-over-year Case-Shiller reading means nominal property values are still rising nationally, but a gain below the inflation rate does not represent an increase in purchasing power. The July data therefore show renewed price momentum without restoring the stronger real appreciation seen during earlier parts of the housing cycle.
The month-over-month figures were more restrained before seasonal adjustment. The national index rose 0.12% from June, the 10-City Composite increased 0.03%, and the 20-City Composite slipped 0.01%. After seasonal adjustment, the national index rose 0.29%, while the 10-City and 20-City measures gained 0.40% and 0.32%, respectively.
S&P noted that the unusually stronger seasonally adjusted readings suggest seasonal patterns weighed on the unadjusted July results. That is useful context because the headline Case-Shiller indexes are reported on a non-seasonally adjusted basis, while the adjusted series can help separate the underlying price trend from the normal rhythm of the homebuying calendar.
Chicago leads again as the regional divide persists
The national figure continued to mask wide differences among metropolitan markets. Chicago posted the strongest annual increase for a fifth consecutive month, with prices up 6.9% from July 2025. New York followed at 5.8%, while Cleveland rose 4.2%.
Several other markets recorded solid gains, including Miami at about 3.5% and San Francisco at about 3.5%. Washington was up 2.2%, while Boston rose 2.7%. The strongest results were concentrated more heavily in parts of the Midwest and Northeast than in the weaker Western and Sunbelt markets.
Seattle remained at the bottom of the 20-city group, with prices down 1.6% from a year earlier. Las Vegas fell 1.3% and Denver declined 1.1%. Tampa and Portland were also negative on an annual basis, while Dallas slipped 0.4% and Phoenix was essentially flat.
S&P described the East-West divide as persistent rather than temporary. Six of the eight Eastern metropolitan markets recorded stronger annual changes in July than in June, compared with only two of the eight Western markets. The pattern suggests that the national acceleration is being driven unevenly and does not amount to a broad-based return to rapid price growth across the country.
Detroit remained an exception in the July table for a technical reason. Cotality said delayed sales records from Wayne County prevented a valid July update for the Detroit Case-Shiller index. A June value was available, and S&P said the missing months will be updated as the delayed sales data are received.
Higher borrowing costs still constrain the market
The July price acceleration occurred even as mortgage rates stayed elevated. Freddie Mac’s weekly survey showed the average 30-year fixed mortgage rising from 6.43% on July 2 to 6.66% on July 30. Higher financing costs reduce the purchasing power of buyers and can limit sales volume, yet they can also keep existing owners from selling if they are reluctant to give up lower-rate mortgages obtained in earlier years.
Those conditions help explain why modest price increases can coexist with a market that still feels difficult for buyers. Home prices do not need to be rising rapidly for monthly payments to remain expensive when borrowing costs are high. At the same time, constrained resale inventory in some markets can support prices even when demand is weaker than it would be under lower mortgage rates.
The July Case-Shiller release therefore points to firmer nominal home values rather than a return to the broad housing surge seen earlier in the decade. The 1.9% national increase was an acceleration, but it remained below inflation, monthly unadjusted growth was close to flat, and several large metropolitan markets were still recording annual declines.
The next Case-Shiller release is scheduled for the last Tuesday of October and will cover August. That report will show whether the national reacceleration continued after July and whether the gap between the strongest Midwest and Northeast markets and the weaker Western and Sunbelt cities narrowed or widened.
More News
Latest News
View all news- Google, Constellation Sign 3.59-GW PJM Power Deal, With $4.3 Billion-Plus Going to Nuclear Uprates
- RPM Posts Record $2.22 Billion Fiscal Q1 Sales, Narrows FY2027 Outlook
- Type One Energy Raises $200 Million Series B to Advance Tennessee Fusion Project
- MIAX Hits Record 17.1% YTD U.S. Options Share as ADV Rises 22%
- Japan’s 10-Year Government Bond Auction Clears Near 3.10% With a 3.1% Coupon