
Fed Finalizes Bank Stress-Test Overhaul Aimed at Cutting Capital-Buffer Volatility in Half
The Federal Reserve will average two years of stress-test results when setting large banks’ stress capital buffers, a change it says should sharply reduce year-to-year swings without materially changing aggregate capital requirements.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy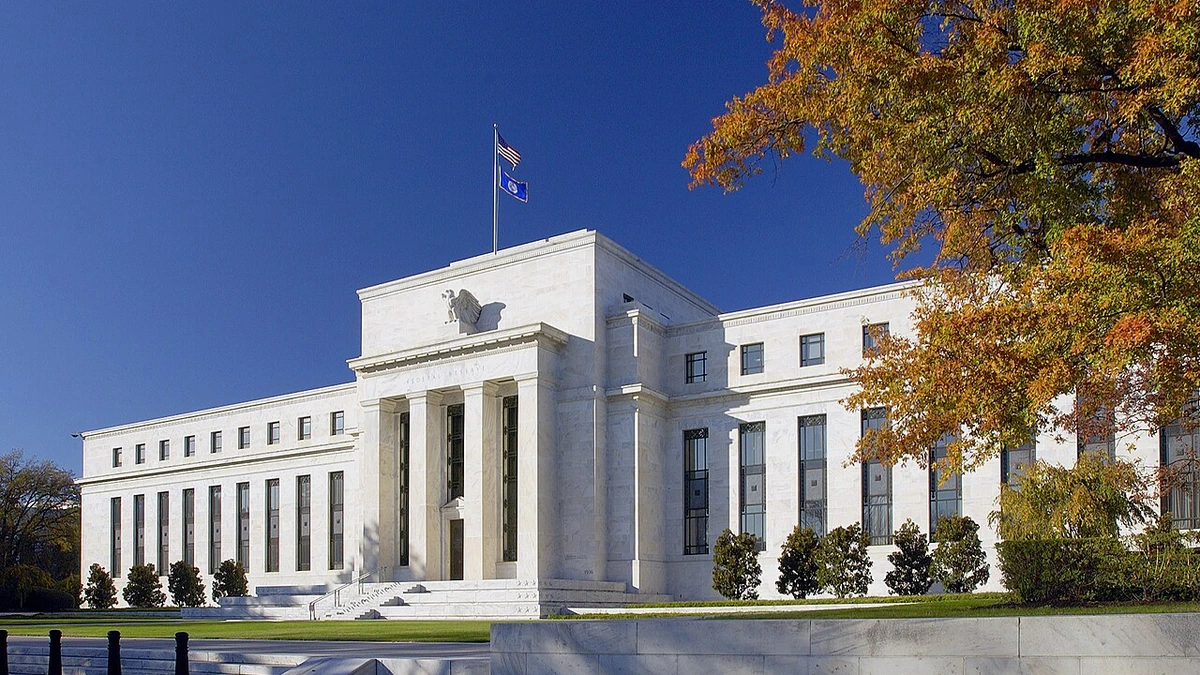
The Federal Reserve finalized an overhaul of its annual stress-testing framework for large banks on Wednesday, adopting a two-year averaging approach designed to make stress-related capital requirements less volatile and expanding the amount of information the central bank will disclose about its models and scenarios.
The most direct change for bank capital planning is the way the stress capital buffer, or SCB, is determined. Instead of relying only on the latest annual supervisory stress test, the Fed will average a bank’s two most recent test results. The central bank says the revised approach should reduce year-over-year SCB volatility by about 50% without materially changing aggregate required capital across the affected banks.
Two-year averaging is meant to smooth the stress capital buffer
The SCB is an additional layer of common equity capital applied to large banks based in part on how far their capital ratios fall under the Fed’s hypothetical severely adverse scenario. A bank whose modeled capital position deteriorates more sharply under stress generally receives a larger buffer, subject to the framework’s minimum requirements.
Because the annual stress test changes from year to year, a single test can produce a noticeably different capital decline from the previous cycle even when a bank’s underlying business has not changed to the same degree. The Fed has argued that some of that movement reflects changes in scenario design, test administration and recent data rather than a comparable change in a firm’s risk profile.
Vice Chair for Supervision Michelle Bowman described the final framework in a September 18 speech on stress testing. She said averaging results over two consecutive years would cut SCB volatility in half while leaving aggregate required capital materially unchanged. The rule also moves the annual effective date of the SCB requirement from October 1 to January 1 of the following year, giving banks more time to incorporate the result into their capital planning.
The change does not eliminate the annual stress test or make each bank’s buffer fixed. A weak current-year result can still raise the two-year average, while a stronger result can pull it lower. Averaging simply means one annual outcome will no longer determine the stress-test component of the buffer by itself.
The Fed is also opening more of the test to public scrutiny
A separate part of the overhaul increases disclosure around the models and hypothetical scenarios used in the supervisory test. The Fed plans to publish more detailed model documentation, including equations, variables, coefficients, assumptions, limitations and the reasoning behind modeling choices. Material changes to the models are also expected to go through a public-comment process before they are used.
Scenario design will become more transparent as well. The Fed has already moved toward seeking public feedback on the annual scenarios that specify the hypothetical recession, unemployment path, asset-price declines and other stresses applied to banks. The broader framework is intended to make the tests easier for banks, investors and other observers to evaluate without turning them into static exercises.
That tension has been central to the redesign. More disclosure can make capital requirements easier to anticipate, but the Fed still wants the tests to capture risks that may not appear in the same form every year. The central bank’s earlier proposals included measures intended to preserve the test’s ability to adapt as financial conditions and bank exposures change.
The global market shock used for firms with significant trading activity is one area where risk capture matters. That component subjects trading and counterparty positions to abrupt hypothetical moves in market prices, rates and spreads. The Fed has been reviewing how the shock is designed and disclosed alongside the broader transparency changes, but the core capital-smoothing mechanism is the two-year averaging of supervisory stress-test results.
The overhaul changes predictability more than the level of capital
The Fed’s stated objective is not a broad reduction in large-bank capital requirements. Its estimate is that averaging will reduce the volatility of the stress capital buffer while leaving the aggregate amount of required capital materially unchanged. Individual banks can still experience higher or lower requirements depending on their own results, balance sheets and risk exposures.
The distinction is important because stress testing sits inside a wider capital framework. Large banks must meet minimum risk-based capital requirements and other applicable buffers and surcharges in addition to the SCB. A smoother stress-test component can make year-ahead capital planning more predictable, but it does not remove those other requirements or guarantee that a particular bank’s overall capital requirement will fall.
The 2026 supervisory stress test itself showed why the framework remains consequential. The Fed said in June that the large banks tested could withstand a severe hypothetical recession and continue lending, but the exercise still generated bank-specific projected losses and capital declines that feed into regulatory capital decisions. The annual scenario is intentionally harsher than a baseline economic forecast and is designed to test resilience rather than predict the most likely path of the economy.
The transparency changes may also alter how banks prepare for future tests. More detailed model documentation should allow firms to understand more clearly how particular exposures affect projected losses, while public comment gives outside parties a formal route to challenge model changes or scenario design. The Fed’s position is that the added accountability can coexist with a stress test that remains sensitive to changes in risk.
For investors and bank management teams, the practical effect will be a capital requirement that is less dependent on a single annual stress-test outcome. The first test of the new framework will be whether the two-year averaging produces the intended reduction in year-to-year swings while preserving the Fed’s ability to raise buffers when a bank’s modeled losses genuinely increase.
More from Banking
Latest News
View all news- U.S. Private Employers Add 90,000 Jobs in September, ADP Says
- KKR’s Integer Acquisition Clears U.S. Antitrust Waiting Period Early
- U.S. Core PCE Inflation Holds at 3.0% as Consumer Spending Jumps 0.9%
- UK Economy Grew 0.5% in Second Quarter, Revised Up From 0.4%
- Skyworks Secures All Regulatory Clearances for Qorvo Merger, Targets Oct. 5 Close
