UK House-Price Growth Halves to 0.8% in September, Nationwide Says
Prices fell 0.2% on the month after seasonal adjustment, while mortgage approvals remained below their recent six-month average in August.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy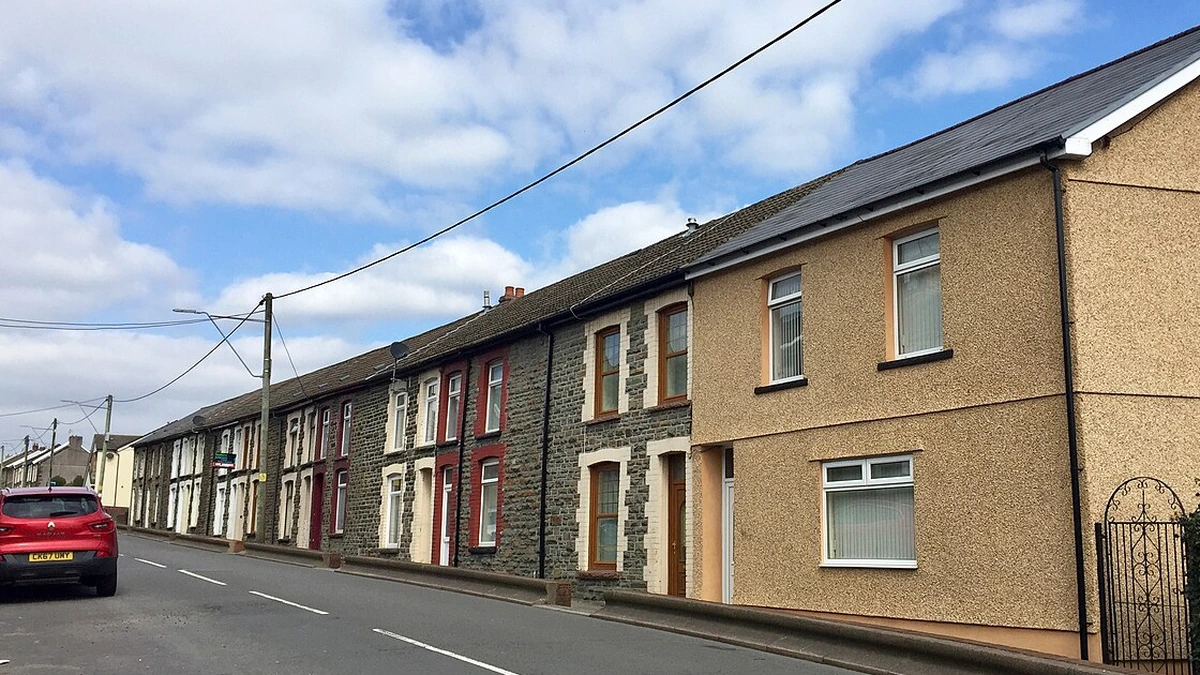
UK house-price growth slowed sharply in September, with Nationwide reporting an annual increase of 0.8%, half the 1.6% pace recorded in August. Prices also fell 0.2% from the previous month after seasonal adjustment, while the average UK price on Nationwide’s non-seasonally adjusted monthly measure declined to £274,251 from £275,465.
The September reading was the weakest annual growth rate since December 2025. It adds to evidence that the housing market has lost momentum after a period in which affordability had been gradually improving, with house-price growth running below earnings growth. That support is now being offset in part by firmer borrowing costs and a more uncertain economic backdrop.
Nationwide’s September House Price Index said activity and prices had remained subdued in recent months. Chief economist Robert Gardner pointed to higher energy prices and renewed inflation concerns as factors that have pushed up market expectations for interest rates and, in turn, the market rates that influence mortgage pricing.
Mortgage costs are weighing on demand
The latest lending data show why financing conditions matter for the housing outlook. The Bank of England reported that net mortgage approvals for house purchases fell to 54,900 in August from 55,900 in July. That was also below the roughly 60,100 monthly average recorded over the previous six months. Gross secured lending dropped to £23.6 billion from £25.3 billion, even as net mortgage borrowing increased to £4.4 billion from £4.1 billion.
Borrowing became more expensive at the same time. The effective rate actually paid on newly drawn mortgages rose to 4.60% in August from 4.45% in July, according to the Bank. The rate on the outstanding stock of mortgages increased to 4.00% from 3.97%. Those figures do not measure quoted mortgage offers directly, but they show the higher rates flowing through to new borrowing and existing mortgage balances.
The Bank of England left Bank Rate at 3.75% at its September meeting, although the vote was 6 to 3 and three policymakers preferred a quarter-point increase. The central bank said higher energy prices linked to the Middle East conflict had lifted the inflation outlook, with UK CPI inflation at 3.1% in August and expected to rise further over the coming quarters. That leaves housing activity exposed to both the level of official rates and the market rates lenders use when pricing fixed mortgages.
There is still an offset from household incomes. Office for National Statistics data showed regular earnings rising 3.5% year over year in the May-to-July period, with private-sector regular pay up 2.9%. Both rates were above Nationwide’s 0.8% annual house-price increase in September. In principle, that gap improves the ratio of home prices to earnings, but the benefit for buyers can be diluted when mortgage rates rise at the same time.
Regional gaps widened in the third quarter
Nationwide’s quarterly regional figures show a much less uniform market than the national monthly headline suggests. Northern Ireland remained the strongest-performing region, with prices up 5.9% from a year earlier in the third quarter, although that was down from 8.6% in the second quarter. The North West followed at 3.9%, while Scotland and the North each recorded growth of 3.3%.
At the other end of the table, East Anglia posted a 0.7% annual decline. The East Midlands fell 0.5%, the South West declined 0.3%, and the Outer Metropolitan region slipped 0.2%. London managed a 0.4% increase, making it the only southern region in Nationwide’s grouping to record annual growth. Across England as a whole, prices rose 0.5% year over year, while the average for southern England fell 0.1% and northern England increased 1.6%.
The regional figures should not be read as a contradiction of September’s 0.8% national annual rate. Nationwide’s quarterly regional data cover the three months to September and produce a separate UK average and annual change. On that basis, the quarterly average UK price was £276,157 and the annual increase was 1.2%, compared with the monthly September average of £274,251 and annual growth of 0.8%.
Terraced homes held up better than flats
Property type also mattered. Terraced homes were Nationwide’s strongest-performing category in the third quarter, with prices up 1.8% from a year earlier. Flats were the weakest, with prices essentially unchanged. The divergence fits a longer-running pattern in Nationwide’s data: since the start of 2020, the price of a typical flat has risen 14%, compared with a 31% increase for semi-detached homes.
Nationwide linked some of that difference to regional performance, particularly London’s relative weakness because the capital has a larger share of flats. The numbers also show that the slowdown is not confined to one segment. Annual growth eased across every property type in the third quarter, reinforcing the broader picture of a market where gains are becoming harder to sustain even before accounting for the renewed pressure from mortgage costs.
The near-term path now depends heavily on whether financing conditions ease or remain restrictive. Nationwide said affordability has improved because house prices have lagged earnings, but it also cautioned that higher mortgage rates have offset part of that gain. The next scheduled Bank of England interest-rate decision is on November 5, providing the next major policy marker for borrowers and lenders as the housing market moves into the final quarter of 2026.
More News
Latest News
View all news- PHINIA Completes stoba Group Acquisition, Broadening Semiconductor and Aerospace Reach
- National Fuel Completes $2.62 Billion Acquisition of CenterPoint’s Ohio Gas Utility
- McCormick Sales Jump 17% in Q3 as Company Reaffirms 2026 Outlook
- Italy’s Unemployment Rate Rises to 6.2% as Jobless Count Increases by 48,000
- Inseego Completes Acquisition of Nokia’s Fixed Wireless Access Business