
Bank of Canada Signals Sharply Higher Inflation Forecast as Oil Prices Surge
Governor Tiff Macklem warned that prolonged oil disruptions could push inflation beyond fuel prices ahead of the Bank of Canada’s October 28 policy decision.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy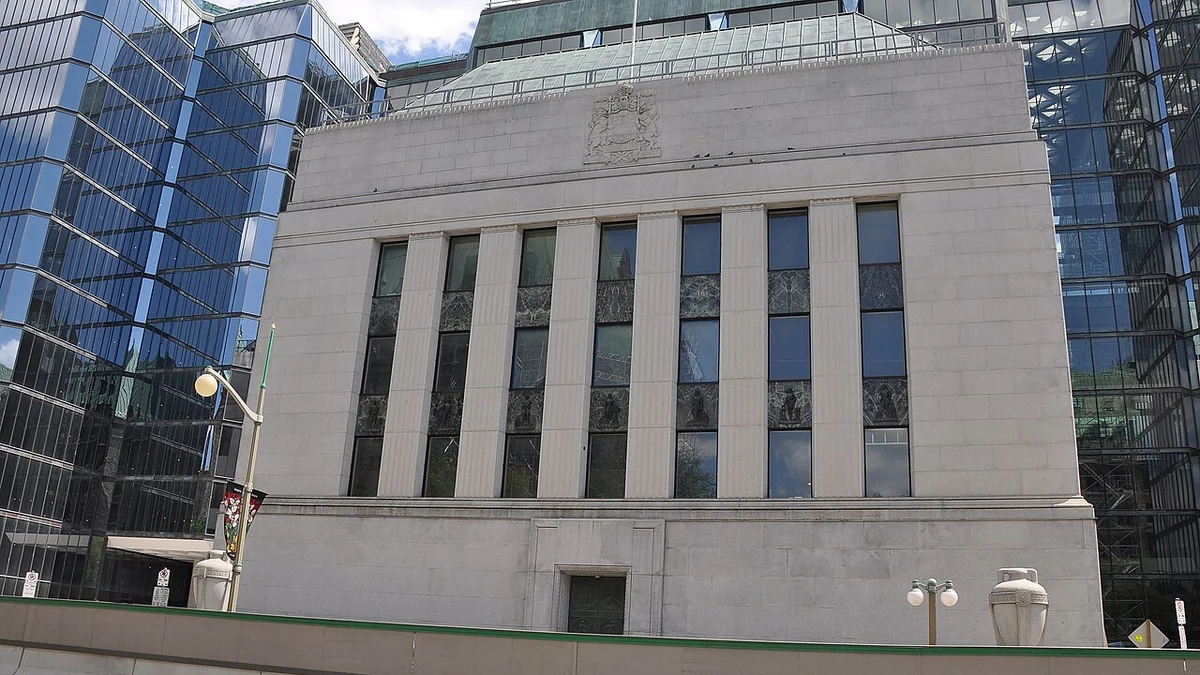
The Bank of Canada expects to raise its inflation forecast substantially this month as high crude oil and refined-fuel prices persist, Governor Tiff Macklem told journalists on Saturday, according to Reuters. The warning adds a new complication to the central bank’s October 28 policy decision, when it is due to publish updated projections for inflation and economic growth.
Macklem spoke from Bangkok during a virtual media roundtable held on the sidelines of International Monetary Fund meetings. Reuters reported that he pointed to the continuing Middle East conflict, restricted oil shipments and damaged refining capacity as reasons price pressures could become more widespread and persistent. The Bank of Canada confirmed that the roundtable took place, but the governor’s comments did not include a new numerical inflation forecast.
The concern marks a more pointed assessment of risks the Bank was already monitoring. In its September 2 policy announcement, it held the benchmark overnight rate at 2.25% and warned that prolonged energy disruptions could raise prices beyond gasoline. Macklem’s latest remarks signal a change to the inflation outlook, not a decision to raise interest rates. The Bank remains committed to its 2% inflation target.
July’s inflation outlook assumed relief from oil prices
The Bank’s July Monetary Policy Report had anticipated that the energy shock would gradually fade. It projected consumer price inflation averaging 2.5% in 2026 and 2.0% in 2027, with inflation returning to the 2% target by early next year. Those figures are the old baseline, not the revised forecasts the Bank plans to publish later this month.
That outlook depended heavily on assumptions about oil. The July forecast used an oil-futures curve dated July 9 and expected unusually high margins on gasoline refining to narrow. Policymakers also assumed shipping through the Strait of Hormuz would gradually recover, reducing pressure on crude prices. If oil remains expensive and refiners continue charging elevated margins, the expected decline in consumer energy costs becomes harder to achieve.
The disruption is not limited to the price of crude. Damage to refinery capacity, along with restrictions on shipments, can keep gasoline and diesel expensive even when crude prices do not rise by the same amount. This is particularly important for Canadian inflation because consumers pay for finished fuels, not crude oil itself. Diesel costs can also affect companies transporting goods, creating a possible route for energy inflation to reach other prices.
By September, the Bank’s Governing Council was already questioning how quickly those pressures might ease. Its published deliberations described refinery damage and maintenance, curtailed shipments through the Strait of Hormuz and little evidence that the conflict was nearing resolution. Officials concluded that high energy costs were likely to last longer than anticipated in July. Macklem’s Saturday comments suggest that persistence will now be reflected more forcefully in the October forecast.
Higher oil prices can have mixed effects on Canada’s economy. Energy producers and some exporters may benefit from stronger prices, but households and businesses face higher costs at the pump and in transportation. The Bank’s July projections already anticipated a contribution to export growth from energy-related activity. A stronger energy sector does not, by itself, prevent fuel costs from lifting the national consumer price index.
Gasoline remains the main source of inflation pressure
The latest published inflation figures show why the Bank is concerned, but also why the breadth of price increases remains an open question. According to Statistics Canada’s August Consumer Price Index report, consumer prices rose 3.0% from a year earlier, matching July’s annual inflation rate. Gasoline prices were 22.8% higher than a year earlier, although that was slower than their 25.7% annual increase in July.
Inflation excluding gasoline was 2.4% in August, up from 2.2% in July. Transportation costs overall increased 7.5% from a year earlier, while grocery prices rose 2.8%. The difference between headline inflation and inflation excluding gasoline underscores the large direct role of fuel prices. At the same time, the increase in the measure excluding gasoline is worth monitoring rather than assuming all other costs are stable.
The Bank’s September assessment was that the energy shock had not yet spread broadly through the economy. Measures of core inflation, which remove or reduce the influence of certain volatile price movements, remained near 2% in July. Inflation excluding gasoline is a different measure and should not be treated as interchangeable with those core indicators. What matters for policy is whether price increases outside energy become sustained rather than appearing in a few individual categories.
Continued expensive fuel raises that risk. Businesses pay more for freight and certain inputs, and some may eventually pass those costs to customers. Households may also come to expect faster price increases if high gasoline bills persist. These are potential channels of inflation, not proof that a broad second wave has already taken hold. The timing and strength of any pass-through depend partly on the ability of businesses to raise prices and on the state of consumer demand.
The rate decision turns on how persistent inflation becomes
Macklem’s warning does not mean a rate increase on October 28 is certain. Central banks can sometimes look through the initial effect of a supply-driven jump in energy prices, especially when higher fuel bills are already hurting household purchasing power. Raising interest rates cannot restore damaged refineries or reopen shipping routes. It can, however, restrain demand and help prevent higher inflation from becoming embedded in broader pricing decisions.
That distinction was central to the Bank’s September deliberations. Governing Council members considered the risk that persistently elevated gasoline and diesel costs could require a monetary policy response if they began to raise other prices more widely. They also judged the Canadian economy to be operating with excess supply, leaving room for weak demand to contain inflation pressure. Those competing considerations make the projected path of inflation more consequential than any one monthly reading.
Canada’s economy had shown signs of improvement before the latest warning. Statistics Canada reported a 0.8% increase in real gross domestic product in the second quarter of 2026, following a revised 0.1% gain in the first quarter. But the Bank’s July report still projected annual GDP growth of just 0.7% for 2026, with a recovery to 1.8% in 2027. New trade restrictions create uncertainty about whether that improvement can continue.
Cross-border tariffs could also make the policy choice harder. In September, the Bank warned that new U.S. tariffs and Canadian countermeasures could increase costs for some businesses, even as trade uncertainty weighed on investment and hiring. Its Governing Council saw both risks together: imported cost pressures could add to inflation, but weaker economic activity could limit how much companies can pass on. The October forecast will have to account for that tension as well as the oil shock.
Interest-rate markets were not pricing in an increase at either the October 28 meeting or the Bank’s December decision as of Saturday, Reuters reported. Its account said money markets were nevertheless pricing in roughly 100 basis points of increases over 2027. Those figures describe market expectations at a particular point in time, not a policy commitment from the Bank or a guarantee about future borrowing costs.
The next set of data arrives before the policy meeting. Statistics Canada is scheduled to release September consumer inflation figures on October 19. The Bank of Canada is also due that day to publish its latest business outlook and consumer expectations surveys, which can help indicate whether price pressures are changing companies’ plans or households’ views of future inflation. The Bank’s October 28 Monetary Policy Report will then put numbers on the revised forecast alongside its interest-rate decision.
More from Banking
Latest News
View all news- Anthropic Co-Founder Cites Scenario of $44 Trillion U.S. GDP by 2030 as AI Advances
- Worldpay Reports and Resolves U.S. Payment Authorization and Apple Pay Disruptions
- Japan Says Two-Year Food-Tax Cut Will Be Funded Without Deficit Bonds
- Australia Reports 41 Days of Petrol Supply and 33 Days of Diesel in October 17 Update
- Switzerland Commits CHF 40 Million to IMF Capacity-Building Work Through 2030
