
Pending U.S. Home Sales Drop 7.3% in September as All Four Regions Decline
Contract signings were down 11.3% from a year earlier, with the West recording the sharpest monthly decline as mortgage rates climbed.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy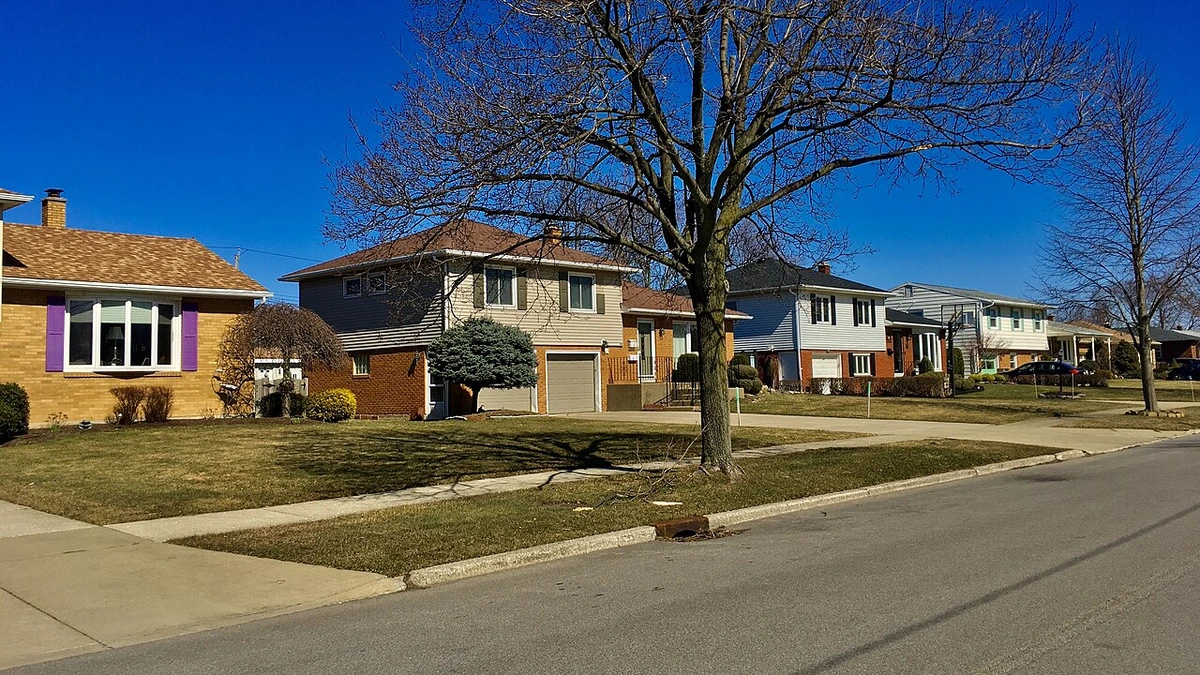
Pending U.S. home sales fell 7.3% in September as buyers signed fewer contracts in every major region of the country, a sharp deterioration in an already slow housing market. The National Association of Realtors reported Tuesday that contract activity was also 11.3% below September 2025, with the West recording the largest monthly and annual declines.
The figures measure agreements to buy existing homes, not completed purchases or changes in home prices. That makes them an early reading on demand rather than a tally of homes that actually changed hands in September. The pullback was broad enough to affect all four regions after a small national increase in August, when pending sales rose 0.3% from the previous month but remained 4.7% below their year-earlier level.
In its October 20 report, the Realtors association pointed to rising borrowing costs as the main obstacle to more home purchases. Chief economist Lawrence Yun said faster-rising mortgage rates had weakened September conditions even though improvements in jobs and incomes can help prospective buyers. The September figures offer a particularly clear indication of that pressure because contract signings declined simultaneously in markets with very different housing costs and local economies.
The West leads a nationwide retreat in contract signings
The West registered a 9.2% month-over-month drop in pending home sales, making it the weakest of the four regions in September. Its year-over-year decline was 15.0%, also the largest regional annual decrease. The South followed with an 8.2% monthly decline and a 12.0% fall from September 2025. Both regions had posted monthly gains in August, so their September readings represent a reversal rather than a continuation of the previous month’s direction.
Activity was weaker in the country’s other two regions as well. The Midwest posted a 6.5% monthly drop and an 8.7% annual decline, while the Northeast fell 4.2% from August and 9.4% from a year earlier. Although the Northeast had the smallest monthly reduction, it still had fewer contracts than at the same point last year. The Midwest’s annual decline was the least severe of the four, underscoring that the ranking changes depending on which comparison is used.
Those differences matter when assessing the reach of the downturn. A national figure can conceal situations in which stronger markets offset weakness elsewhere; September’s reading was not one of those cases. Every region contributed to the monthly drop, and none showed a year-over-year recovery. The biggest declines were concentrated in the West and South, but the problem was not limited to those parts of the country.
The local picture was more varied than the regional averages alone suggest. In metro-area figures compiled by Realtor.com Economics and included in the NAR release, Nashville recorded a 2.0% annual decline and Hartford a 2.1% decrease, among the smallest drops across the 50 largest metropolitan areas. Buffalo’s annual decline was 5.6%. These comparatively mild declines do not contradict the national report: they show that some local markets held up better even though the broader direction remained negative.
Mortgage rates climbed as buyers weighed monthly payments
The decline coincided with an increase in the cost of financing a home. Freddie Mac’s weekly mortgage survey shows the average 30-year fixed rate at 6.66% on August 27, 6.71% on September 3 and 7.03% by September 24. It reached 7.28% on October 1 and 7.40% by October 15. The October figures describe conditions after September ended, rather than the mortgage rate prevailing throughout that month’s contract-signing period.
For a buyer considering a fixed-rate mortgage, an increase in the interest rate means a larger monthly principal-and-interest payment for the same loan amount. That can limit the price a household can afford or make a purchase harder to qualify for under a lender’s income and debt tests. Some buyers can adjust their budgets or negotiate on price; others may postpone making an offer. The change in rates helps explain why the September pending-sales report can weaken even when homes remain available for purchase.
Yun said income gains and job growth could support housing demand, but changes in mortgage rates have an especially strong influence on affordability. He also suggested borrowing rates might be nearing a peak because they had already risen considerably, while cautioning that higher energy prices and inflation pressures made the outlook uncertain. That was an assessment of possible future conditions, not evidence that mortgage rates had already stopped rising.
August’s modest improvement provides context for the abrupt turn. NAR’s prior release showed gains of 2.3% in the South and 3.0% in the West, offsetting declines in the Northeast and Midwest. In September all four regions moved lower. The contrast suggests that the earlier national increase was fragile and that prospective buyers remained sensitive to a change in financing conditions, rather than indicating a sustained acceleration in housing demand.
Weak contracts may show up in later home-sales reports
Pending sales normally lead completed existing-home sales because buyers sign purchase agreements before closing. NAR says most of these agreements are finalized within one or two months, although financing difficulties, inspection findings and appraisal issues can delay or prevent a closing. Its pending-sales indicator is drawn from a sample covering about 40% of multiple-listing-service data each month. It is therefore useful as a directional gauge, not a guarantee that the same percentage change will appear in subsequent completed-sale figures.
The distinction also helps reconcile September’s weak contracts with figures already reported for completed purchases. NAR said existing-home sales increased 1.5% from August to September, reaching a seasonally adjusted annual rate of 3.99 million. Those closings typically reflect decisions and contracts made earlier, while the newly reported pending-sales decline captures more recent buying activity. A rise in closed sales in September does not cancel out the weakening signal from that month’s new purchase agreements.
Home prices follow a different measure again. In its September existing-home sales data, NAR put the national median sale price at $417,500, up 1.3% from a year earlier. A lower volume of pending contracts does not by itself establish that property values fell. Yun argued that the limited supply of distressed properties was helping keep prices relatively steady, while buyers and sellers might remain on the sidelines until mortgage financing became more favorable. His comments describe current market conditions and a possible reason for hesitation, not a firm forecast for prices.
For sellers, weaker contract activity can mean a longer marketing period or greater pressure to adjust an asking price, depending on local inventory and demand. Buyers who remain qualified may have more room to negotiate in some markets, but higher monthly financing costs can offset part of the benefit of a lower purchase price. The NAR data alone do not establish how much negotiating power changed in any particular neighborhood.
The next scheduled checkpoints are NAR’s October existing-home sales release on November 12 and its October pending-home sales report on November 18. The first will show whether weaker contracts are beginning to feed through to completed purchases; the second will offer a more direct look at whether buyers resumed signing agreements after September’s steep decline.
More News
Latest News
View all news- Five Tradr Leveraged ETFs Reach October 20 Trading Suspension Date on Cboe
- SEC and French Regulator Sign Oversight Agreement for Cross-Border Investment Advisers
- NCUA Proposes Easing Three Credit Union Rules, Including Investment Reserve Requirements
- GM Authorizes $20 Billion Share Buyback After Reporting $3.3 Billion Quarterly Profit
- GE Aerospace Raises 2026 Outlook as Third-Quarter Orders Jump 49%
