
Eurozone Inflation Expectations Rise to 3.1% as Consumers Turn More Pessimistic on Growth
The ECB survey showed a weaker 12-month growth outlook and higher unemployment expectations, even as longer-term inflation forecasts held steady.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy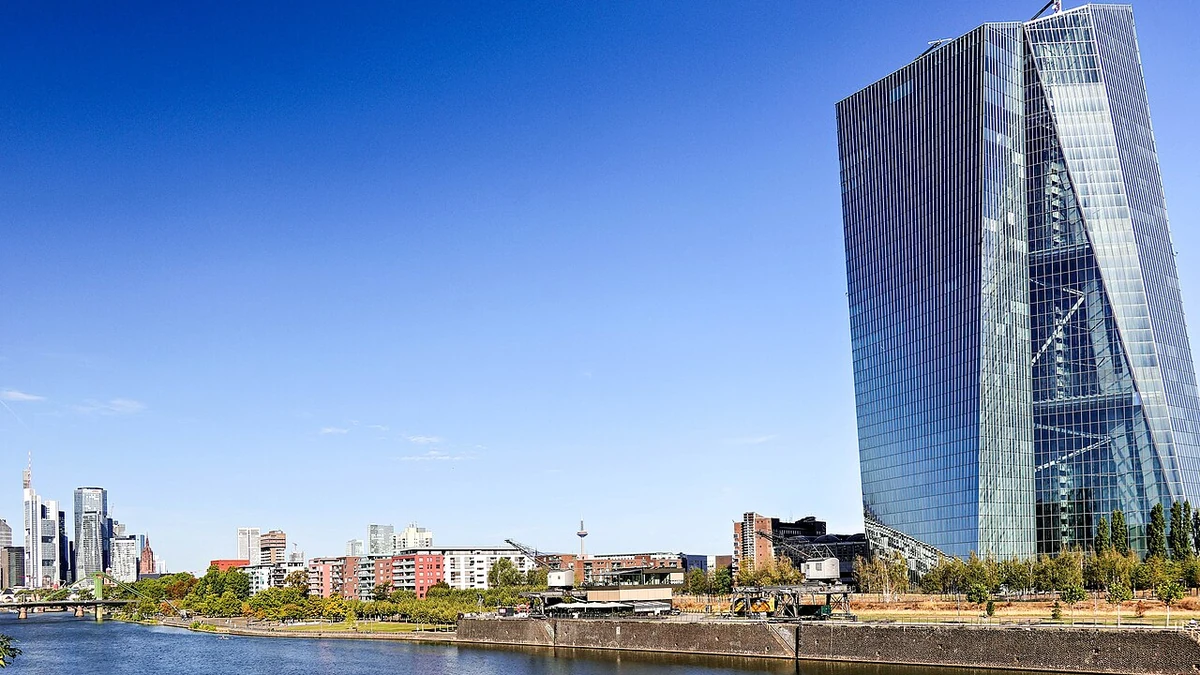
Euro-area households expect inflation to run slightly faster over the coming year and have become more pessimistic about economic growth, according to a European Central Bank survey released Friday. The median expectation for inflation over the next 12 months reached 3.1% in September, up from 3.0% in August.
Consumers also marked down their outlook for economic growth over the next year to -1.5% from -1.2%, while the unemployment rate they expect a year from now increased to 11.3% from 11.0%. Those are survey expectations, not official forecasts or evidence that the economy has already contracted by the reported amount.
The ECB’s September Consumer Expectations Survey, published on October 23, points to greater anxiety about the near-term economy without a comparable rise in longer-term inflation expectations. That distinction is important for a central bank assessing whether an inflation shock is changing household views beyond the coming year.
Inflation worries rise in the near term
Respondents’ median assessment of inflation over the previous 12 months increased to 3.6% from 3.5%. Their expectation of 3.1% for the year ahead was lower than that backward-looking perception, suggesting they still anticipate some moderation in the pace of price increases they have experienced. Both figures describe households’ judgments about different periods, rather than the measured consumer price index.
Further out, expectations showed no additional increase in September. The median three-year inflation expectation remained at 2.9%, and the five-year reading stayed at 2.5%. Both measures had risen in August, so September’s stability offers a narrower signal than saying longer-term inflation concerns have disappeared. They remain above the ECB’s 2% medium-term inflation target.
The central bank reported a slight increase in uncertainty surrounding inflation over the next year. That uncertainty remained above its level before the conflict in the Middle East, according to the survey. A higher central expectation and greater uncertainty measure different things: households can anticipate faster inflation while also becoming less certain about how prices will develop.
The results also varied by household circumstances. Lower-income respondents continued to report higher inflation perceptions and expectations than the highest-income group. People aged 18 to 34 generally reported lower readings than those in the two older age groups surveyed. The figures describe differences in reported views; the survey does not establish a single cause for those gaps.
Official price data help explain the backdrop without being interchangeable with the survey. Eurostat reported that annual euro-area inflation rose to 3.8% in September from 3.2% in August. Energy contributed 1.71 percentage points to the September annual rate, and services contributed 1.52 points. Those are observed price changes, whereas the ECB’s 3.1% figure is the median of consumers’ predictions about the next 12 months.
Growth expectations weaken as job concerns increase
Households’ average expectation for economic growth slipped by 0.3 percentage points to -1.5%. The weaker assessment followed an August reading that had been unchanged from July at -1.2%. It is a measure of public sentiment about the following 12 months, not a national-accounts estimate or a prediction endorsed by the ECB’s economic staff.
That distinction is especially relevant because the ECB’s September staff projections offered a different outlook. Its baseline forecast called for positive euro-area GDP growth of 0.9% in 2026 and 1.4% in 2027. The survey measures the views of consumers for a rolling year ahead, while staff projections use calendar-year forecasts and their own models and assumptions. The figures should not be treated as directly comparable forecasts.
The labour-market responses reinforced the gloomier growth view, although they did not suggest households expect a sudden employment collapse. The jobless rate anticipated 12 months ahead rose to 11.3%, versus 11.0% in August. Respondents put their perception of the current unemployment rate at 10.6%, leaving a relatively modest gap between perceived current conditions and expected future conditions.
Income groups again differed. The lowest-income fifth of households expected an unemployment rate of 13.6% in a year’s time, compared with 9.7% for the highest-income fifth. Neither number is a measured labour-market statistic. They reveal how unevenly households assess the risks ahead, even within the same currency area.
The change in September also reversed an improvement in the previous survey’s unemployment expectations. In August, the expected rate had fallen to 11.0% from 11.2% in July. Monthly shifts should not be read as proof that actual unemployment is about to rise, but the latest answers show a less reassuring outlook than households expressed one month earlier.
Spending plans and housing expectations paint a mixed picture
The consumer outlook was not uniformly weaker. Expected nominal income growth over the next 12 months edged up to 1.1% from 1.0%, and anticipated nominal spending growth rose to 3.7% from 3.6%. These are expectations for money amounts before adjusting for price increases, so they cannot by themselves establish whether real purchasing power will improve.
Respondents also said their nominal spending had grown by 5.3% over the preceding 12 months, compared with a 5.2% assessment in August. The lower 3.7% expectation for future spending growth points to slower anticipated growth in outlays than households say they recently experienced. It does not mean consumers are forecasting an outright fall in the amount they spend.
There was some variation in income expectations as well. The bottom income quintile expected nominal income to increase by 1.5%, compared with 1.2% for the top quintile. That sits alongside the higher inflation expectations reported among lower-income consumers. It is not enough to calculate the real-income outlook for a typical person in either group, but it shows why the survey’s headline measures cannot describe every household’s position.
Housing provided another contrast. Consumers expected their home’s price to increase 3.5% over the next year, up from 3.4% in August, even as their assessments of access to credit deteriorated. Those in the lowest income quintile anticipated 4.0% house-price growth, compared with 3.2% among the highest-income group. These are household expectations, not a forecast of the official property price index.
Expected mortgage interest rates 12 months ahead remained at 4.9%, unchanged since July. The average expected rate was 5.7% among the lowest-income households and 4.4% among the highest-income households. More respondents reported that credit had tightened rather than eased, and the balance expecting tighter future credit conditions also increased. The release did not supply a headline percentage for those net balances, so the movement is best described directionally.
The backdrop has direct relevance for monetary policy, although the survey alone cannot determine an interest-rate decision. In September, the ECB raised its three key rates by 25 basis points, citing inflation pressures linked to the Middle East conflict. Its deposit-facility rate became 2.50% on September 16. The ECB’s next scheduled monetary-policy decision is on October 29, giving policymakers another opportunity to weigh inflation data, activity indicators and household expectations together.
The survey is conducted online among roughly 19,000 adults in 11 euro-area countries. Fieldwork for the September round ran from August 27 to September 28. Its published inflation figures use medians, while the other cited expectations generally use averages adjusted to limit the influence of extreme responses. The next release, covering October consumer expectations, is scheduled for November 27, 2026.
More News
Latest News
View all news- University of Michigan Research Warns Long-Term Inflation Expectations Could Become Entrenched
- First Citizens Authorizes $1.2 Billion Share Buyback Alongside Third-Quarter Earnings
- American Express Raises 2026 Profit Outlook After Record $20.1 Billion Quarterly Revenue
- U.K. Retail Sales Fall 0.4% in September Despite Third-Quarter Growth
- Japan’s September Consumer Inflation Reaches 2.1%, With Underlying Prices Up 2.4%
