
U.K. Retail Sales Fall 0.4% in September Despite Third-Quarter Growth
Weakness in online clothing and supermarket sales offset stronger fuel volumes, while summer demand left the third quarter ahead.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy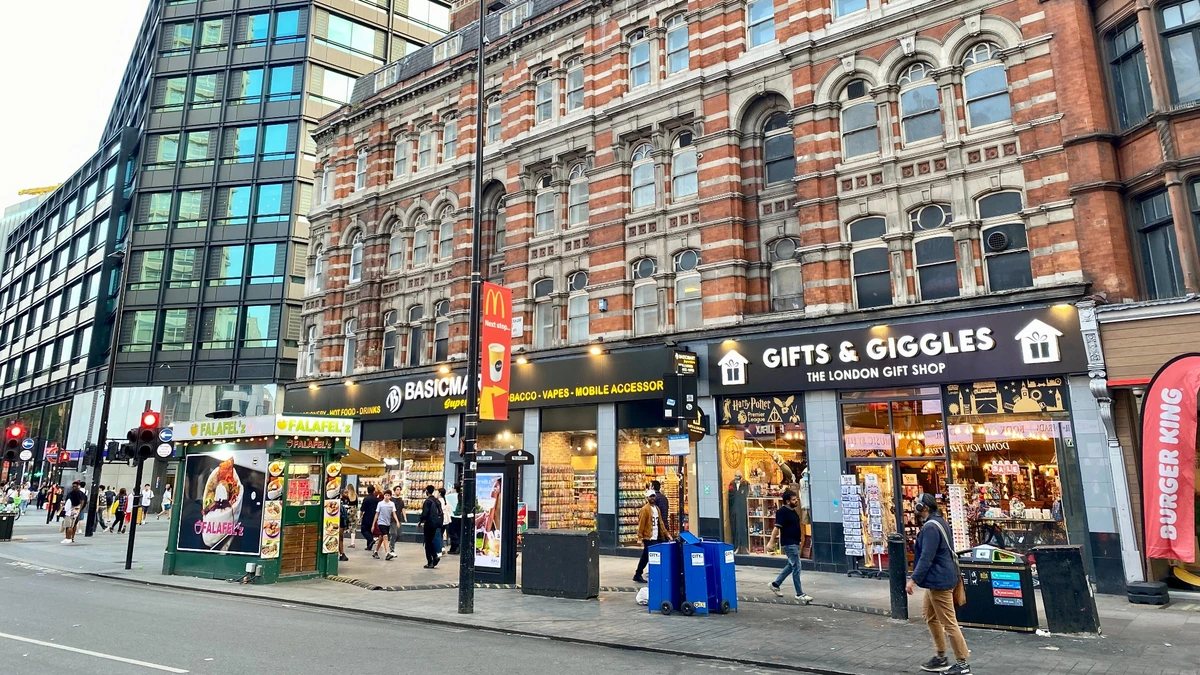
Retail sales volumes in Great Britain fell 0.4% in September from August, ending a stronger summer period on a weak note even as sales for the third quarter grew 0.7%. The figures released Friday, October 23, show a pullback in shopping outside fuel stations, particularly among online clothing sellers and supermarkets.
The monthly decline was sharper than the 0.1% drop economists had expected in a Reuters poll. It followed an upwardly revised 0.7% rise in August, making September’s reversal more noticeable, although the three-month total remained positive. The pattern leaves two different readings of household demand: shoppers bought more goods across July through September than in the preceding quarter, but fewer in its final month.
England, Scotland and Wales are covered by the Office for National Statistics’ September retail sales release, rather than Northern Ireland. Its headline volume measure tracks the quantity of goods sold after allowing for changes in prices. That distinction matters when higher fuel prices are affecting what households pay at the pump and how much money remains for other purchases.
Online Clothing Sales and Supermarkets Weaken
Non-store retailing, a category dominated by businesses selling online, recorded one of the sharpest September declines. Sales volumes fell 2.2% from August, with online clothing retailers reporting that unusually warm weather had reduced demand for their autumn and winter ranges. It was a seasonal explanation reported by retailers to the statistical agency, not proof that weather alone accounted for the broader fall in spending.
Clothing and footwear sellers operating from stores also struggled, with the wider textile, clothing and footwear category down 0.9% over the month. Supermarket volumes fell 0.4% after gains in both July and August. Some supermarkets sell clothing alongside groceries, so weaker interest in colder-weather ranges could affect more than specialist fashion chains.
Across non-food stores, sales volumes were down 0.4% in September. Department stores were a limited exception, posting a modest 0.2% rise. The small gain at department stores does not erase the wider decline, but it cautions against treating September as equally weak for every kind of shop.
Fuel retailers moved in the opposite direction. The volume of automotive fuel sold rose 2.2% from August despite higher pump prices, partially cushioning the weakness elsewhere. Excluding automotive fuel, total retail volumes fell 0.7% over the month. The gap between the two readings suggests that the headline drop understated the reduction in goods bought from retailers other than fuel stations.
Motor fuel also illustrates why sales volumes and spending in pounds should not be treated as interchangeable. A rise in prices can increase a retailer’s revenue without an equivalent rise in the quantity sold. The September release therefore says more about the amount of shopping being done than a simple measure of cash passing through tills would.
Summer Demand Keeps the Third Quarter Positive
The July-to-September quarter still produced a 0.7% increase in retail volumes compared with April through June. On a year-earlier basis, third-quarter volumes were 1.5% higher. The quarterly improvement is not inconsistent with September’s monthly fall: three-month figures capture sales across the entire period, including activity before the final month’s decline.
Fuel sales helped lift the quarterly result after weakness in the second quarter. Food and drink purchases provided support as well. Retailers cited the warm summer weather, promotions and interest around the football World Cup as contributors to demand for beverages and other goods. Those conditions supported sales earlier in the quarter, even though supermarket spending weakened toward its end.
Revisions to recent monthly estimates added strength to the summer period. The ONS narrowed July’s reported decline to 0.4% from 0.5% and raised August’s increase to 0.7% from 0.5%. Revisions are a regular feature of preliminary economic statistics as more returns and updated information become available. The changes improved the picture of late-summer trading without altering the latest month’s negative reading.
Measured against September 2025, retail sales volumes were still 0.8% higher. That annual increase was much smaller than August’s revised 2.7% year-over-year gain. Monthly and annual comparisons answer different questions, however, and neither alone establishes whether the decline will persist into the final quarter. These figures establish a weaker September, not yet a sustained retreat in retail activity.
Consumer Confidence Falls as Price Pressures Build
Households also reported growing anxiety about the economy in October. The GfK Consumer Confidence Barometer, published by NielsenIQ and powered by NIM, showed its overall index falling 11 points to minus 24 in October, from minus 13 in September. The survey was conducted from October 1 to October 14 among 2,003 people aged 16 and older.
The survey also found caution extending beyond general views of the economy. GfK’s index of willingness to make major purchases fell 14 points to minus 22, while expectations for the wider economy over the coming year dropped 14 points to minus 36. Expectations for respondents’ own finances also deteriorated, though by a smaller eight points. The breadth of those declines may concern retailers entering the year-end shopping season.
Consumer-confidence surveys measure attitudes rather than completed purchases, and October’s responses cannot establish why retail volumes fell during September. Together, the two releases nevertheless point to a challenge: retailers face weaker recent sales in several categories just as shoppers report greater caution about their finances and larger purchases.
Inflation adds to that pressure. Separate ONS figures published on October 21 put annual consumer price inflation at 3.5% in September, up from 3.1% in August, with transport and especially motor fuels the largest upward contributor to the annual rate’s change. Rising essential costs can limit room for other spending, although the retail figures do not establish how much of September’s drop was caused by household budget constraints rather than seasonal shopping patterns.
The Bank of England held its benchmark interest rate at 3.75% in September, with three of the nine Monetary Policy Committee members favoring a quarter-point increase. Its next scheduled decision is November 5. Policymakers must weigh the risk of sustained inflation against evidence that demand is losing momentum; a single weaker retail month does not determine the rate decision.
October retail-sales figures are scheduled for release by the ONS on November 20. They will help establish whether September reflected an isolated fall after a solid summer or the beginning of a more persistent slowdown in goods purchases.
More News
Latest News
View all news- University of Michigan Research Warns Long-Term Inflation Expectations Could Become Entrenched
- First Citizens Authorizes $1.2 Billion Share Buyback Alongside Third-Quarter Earnings
- American Express Raises 2026 Profit Outlook After Record $20.1 Billion Quarterly Revenue
- Japan’s September Consumer Inflation Reaches 2.1%, With Underlying Prices Up 2.4%
- German Business Growth Slows in October as Services Lose Momentum
