
SEC Sets 2027 Examination Priorities, With Private Credit and AI-Related Risks in Focus
SEC examiners will review illiquid investments, adviser conflicts, advanced technology risks and brokerage recommendations under a risk-based plan that creates no new rules.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy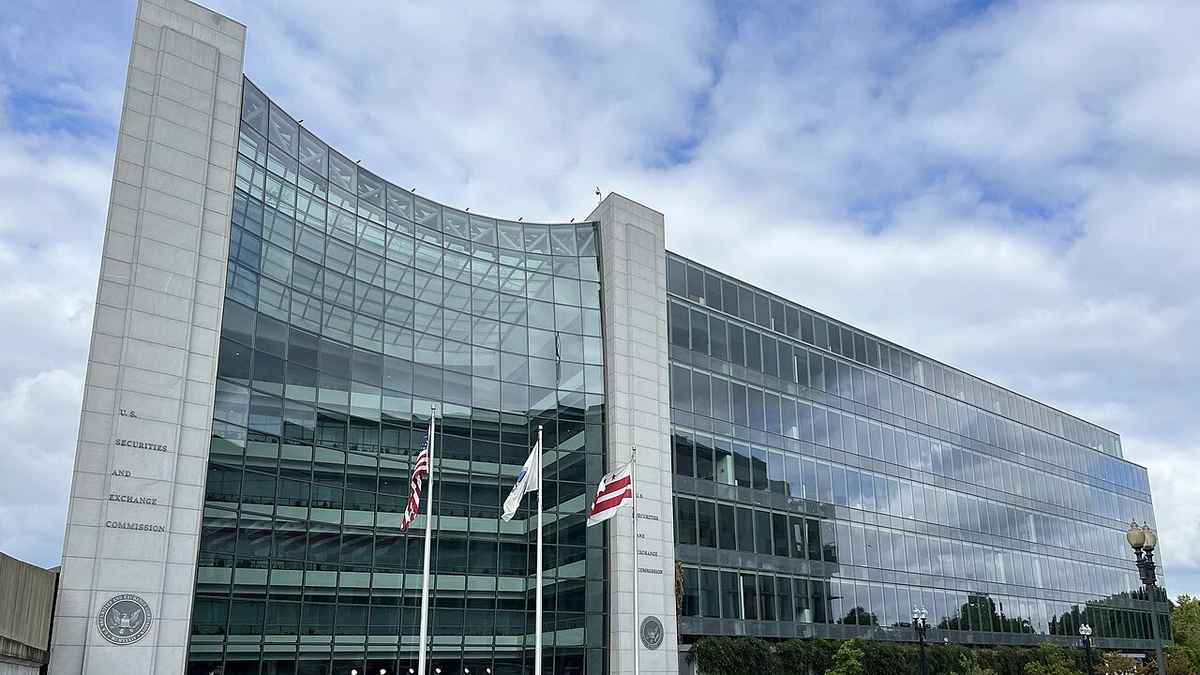
The U.S. Securities and Exchange Commission’s examination staff has outlined its fiscal 2027 priorities, placing private credit and other hard-to-sell investments alongside risks linked to advanced artificial intelligence tools, cybersecurity and changes in market infrastructure. The plan also keeps investment adviser conflicts and broker-dealer sales practices under scrutiny, showing that longstanding investor-protection questions remain central even as the technology used by financial firms changes.
Released on October 23, the priorities identify areas the SEC’s Division of Examinations expects to emphasize in its risk-based inspections of regulated firms. They do not constitute a new set of rules or an enforcement finding against any institution. The division says examiners may review subjects outside the published list and can adjust their focus as risks develop during the fiscal year.
The division’s fiscal 2027 examination priorities report goes beyond a broad warning about alternative assets or new software. It details the questions examiners may ask about pricing, liquidity, disclosure, customer safeguards and the consistency of investment recommendations with a client’s needs. Those distinctions matter because a product or technology appearing on the list is not itself a finding that a firm has violated securities law.
Private Credit Draws Scrutiny Across Investment Channels
Private credit appears in several parts of the examination program rather than as a single review category. Advisers recommending illiquid investments, including loans made through private funds or business development companies, can expect attention to the reasoning behind those recommendations. Staff will consider the risks of products that are difficult to trade, have unusual features or are less transparent than conventional publicly traded securities.
For advisers managing private funds, the SEC plans to examine whether disclosures accurately describe investment risks and whether controls operate at both the fund and underlying investment levels. The report specifically identifies the use of borrowing and fund-level credit lines, affiliated service providers, investment allocations and the calculation of fees and expenses. Those issues can affect what investors actually pay and how risks are shared, even when the headline strategy appears straightforward.
Registered investment companies, including mutual funds and exchange-traded funds, face related questions when portfolios contain private credit or other assets that are difficult to sell. Examiners will look at valuation practices, redemption arrangements and disclosures of conflicts and risks. They will also compare a fund’s actual portfolio management with the strategy described in its filings and marketing. The focus does not mean all private-credit holdings are impermissible; it means firms must be able to support their practices under existing obligations.
Broker-dealers are another point of contact for the same underlying risk. Their examinations may cover how illiquid private-credit and private-equity instruments are priced, as well as recommendations of funds that invest in such assets. This places attention on different stages of the investment process: how an asset is valued inside a portfolio, what an adviser says about it and whether a brokerage recommendation serves a retail customer’s interests.
AI-Related Cyber Threats and Automated Advice
The technology portion of the priorities reaches beyond whether financial firms use artificial intelligence. The document uses the term ‘super intelligence,’ or SI, in discussing advanced tools employed in investment analysis, customer management and software development. It also warns that malicious actors can use such tools to make cyberattacks more effective. Examiners will assess how firms prepare for threats that could disrupt operations or expose customer information.
Among the specific threats cited are computer-generated phishing messages and synthetic voice or video used to impersonate people during social-engineering attempts. Reviews will examine the surrounding safeguards, including access controls, account management, data-loss prevention and the ability to respond to ransomware or another security incident. The division also intends to assess risks tied to outside service providers and shared technology, recognizing that sensitive operations do not always sit entirely within a financial firm’s own systems.
Automated investment advice presents a different set of questions. When an adviser or platform uses algorithms to produce recommendations, SEC staff plan to consider whether public claims about those capabilities are accurate, whether operating controls match investor disclosures and whether the resulting advice fits customers’ investment profiles or stated strategies. The same principle applies to tools used for trading, monitoring compliance, detecting fraud or supporting anti-money-laundering work: deploying newer technology does not remove existing legal responsibilities.
Customer-information rules remain part of the review. Under Regulation S-P, the division will assess safeguards and incident-response arrangements, including customer notification and oversight of service providers. Regulation S-ID examinations will consider whether identity-theft programs have been updated for account takeovers, fraudulent transfers and risks involving stolen credentials. This gives the technology priorities a practical compliance emphasis rather than treating AI as a stand-alone regulatory category.
Brokerage Recommendations and Market Infrastructure
For broker-dealers, the SEC continues to prioritize Regulation Best Interest, the standard governing recommendations to retail customers. Reviews will cover the consideration of reasonably available alternatives, disclosure and management of conflicts, the costs of recommended products and the basis for account or rollover advice. The report singles out complex or higher-risk investments, such as certain annuities, single-stock exchange-traded funds, structured products and options that expire on the day they are traded.
Older investors and people saving for retirement or college remain a particular concern when firms recommend products or account changes. Examiners also plan to assess arrangements at firms registered as both broker-dealers and investment advisers, where compensation incentives can complicate decisions about which accounts or investments clients receive. On the advisory side, the priorities continue to emphasize economic conflicts involving fee calculations, account compensation and cash management.
Financial responsibility checks will examine brokers’ adherence to net-capital and customer-protection requirements, along with their ability to manage liquidity during stressful markets. Trading reviews will address order routing and execution, the operational demands of extended trading hours and the availability of liquidity providers. The program therefore includes core market-function questions that are distinct from the newer risks attracting attention in the headline.
Market infrastructure is also changing. Examinations of clearing agencies will consider default management, operational controls and tokenization, as well as compliance with rules related to expanded U.S. Treasury clearing. Under Regulation Systems Compliance and Integrity, staff will examine technology risks associated with tokenized securities, longer trading sessions, quantum computing and reliance on cloud vendors. These are areas for reviewing controls and compliance, not an announcement that the SEC is imposing a fresh tokenization regime through the priorities document.
The priorities also call for continued examinations of investment advisers that have never been inspected, particularly recently registered firms. A firm’s growth into new asset classes, changes in its business model or expansion through mergers and acquisitions can prompt questions about whether its compliance program has kept pace. Earlier in October, the division published a new examination handbook describing the inspection process and ways firms can engage with staff, part of a broader effort to make examinations more predictable without limiting their scope.
The report expressly states that it reflects the views of examination staff, has no legal force and creates no new obligations. Its practical significance is the insight it offers into where regulators expect to direct examination resources. For private-credit managers, firms using advanced technology and broker-dealers handling complex products, the relevant test remains compliance with the securities laws and rules already applicable to their activities.
More News
Latest News
View all news- First Citizens Authorizes $1.2 Billion Share Buyback Alongside Third-Quarter Earnings
- American Express Raises 2026 Profit Outlook After Record $20.1 Billion Quarterly Revenue
- U.K. Retail Sales Fall 0.4% in September Despite Third-Quarter Growth
- Japan’s September Consumer Inflation Reaches 2.1%, With Underlying Prices Up 2.4%
- German Business Growth Slows in October as Services Lose Momentum
