
Chicago Fed Index Turns Positive in September, Signaling a Pickup in U.S. Economic Activity
Production and income lifted the measure to +0.07 in September, while personal consumption and housing dragged on the improvement.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy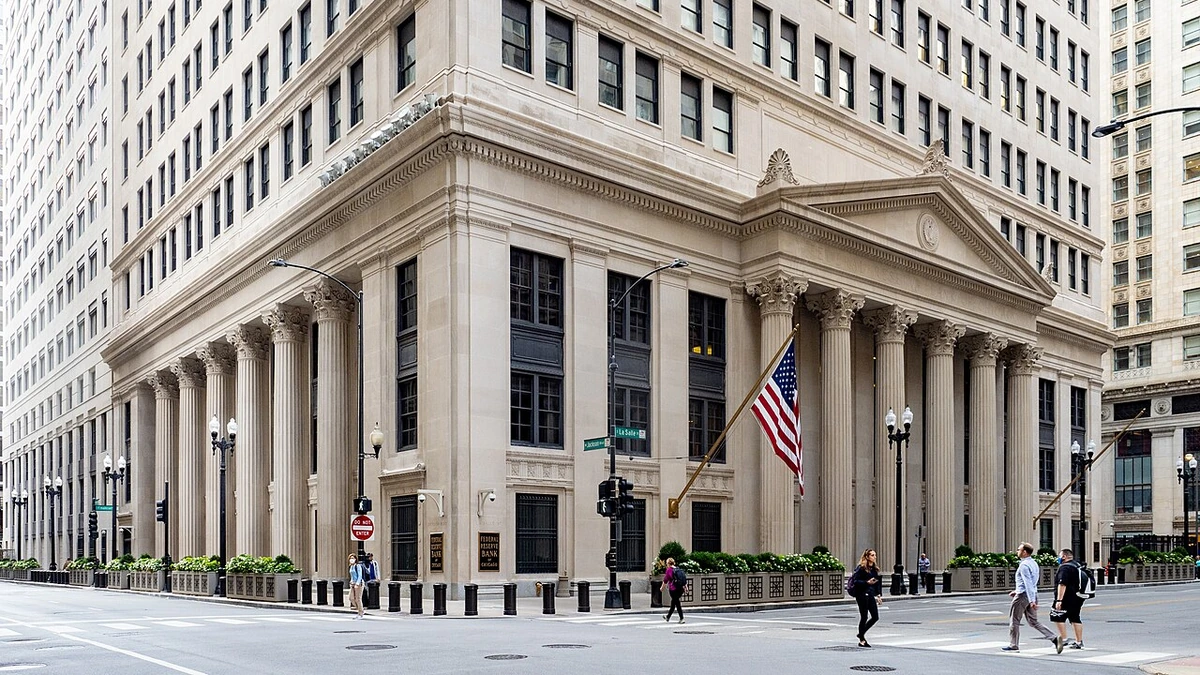
U.S. economic activity moved modestly above its historical trend in September, according to new figures from the Federal Reserve Bank of Chicago. Its Chicago Fed National Activity Index (CFNAI) rose to +0.07 from a revised −0.08 in August, reversing the previous month’s negative reading.
The 0.15-point increase was driven largely by stronger production-related indicators rather than an improvement across every part of the economy. Measures tied to personal consumption and housing weakened, while employment-related data made a neutral contribution. The index’s three-month moving average rose only slightly, to +0.03 from +0.01.
The Chicago Fed’s activity index compares the economy’s performance with its long-run rate of growth. Zero represents growth at that trend; positive readings mean above-trend growth and negative readings mean below-trend growth. September’s +0.07 therefore signals activity a little above normal, not a 0.07% increase in gross domestic product.
Production drove the improvement, but housing and spending lagged
Production and income contributed +0.13 to the September CFNAI, compared with −0.06 in August. The swing was larger than the improvement in the overall index and was the clearest source of September’s stronger reading. Those figures measure the category’s contribution to the composite index, not the percentage change in factory output.
Separate figures released earlier in October help put that improvement in context. The Federal Reserve Board reported that U.S. industrial production increased 0.7% in September after a revised 0.1% gain in August. Manufacturing output rose 0.3%, mining output advanced 0.2% and utilities production jumped 3.5%. The production category in the Chicago Fed measure draws on a wider set of indicators, so no single industrial production figure explains its entire contribution.
The Board’s report also showed that industrial production grew at a 2.8% annual rate in the third quarter. Factory activity was less uniform than the overall September gain might suggest: motor vehicle and parts production fell 3.0% for the month even as manufacturing output increased. Those differences matter when interpreting a composite index that brings together activity across industries.
Sales, orders and inventories added +0.02 to the Chicago Fed measure, up from a −0.03 contribution in August. Employment, unemployment and hours contributed 0.00, compared with −0.02 the prior month. A neutral employment contribution does not mean no workers were hired or no jobs were lost; it means that this group of labor indicators, taken together, made essentially no net contribution to the index.
The weakest category was personal consumption and housing. Its contribution dropped to −0.08 from +0.02 in August, offsetting part of the strength elsewhere. The negative reading should not be confused with a direct measure of household spending falling by 0.08%. It describes how indicators in that category affected the overall CFNAI relative to their normal patterns.
With two categories contributing positively, one contributing nothing and one pulling the total lower, the September rebound was uneven. Production alone added more than the final +0.07 reading, underscoring the difference between an improved headline measure and broad strength in every sector.
The three-month average points to near-trend growth
The less volatile three-month moving average, known as CFNAI-MA3, rose to +0.03 in September from +0.01 in August. That measure smooths monthly swings and is often more useful than a single reading for judging whether growth is running materially above or below its historical pace. A result so close to zero indicates an economy operating near trend over the latest three months.
The Chicago Fed builds the index from 85 existing monthly indicators covering production and income; employment, unemployment and hours; personal consumption and housing; and sales, orders and inventories. Because the series come from several parts of the economy and are published on different schedules, the composite gives a broad view but does not replace detailed releases on output, jobs or consumer demand.
The distinction also matters for reading recession and inflation signals. The Chicago Fed says a three-month average below −0.70 has historically been associated with an increasing likelihood of recession after an expansion. It separately identifies readings above +0.70, more than two years into an expansion, as associated with heightened inflation risks. September’s +0.03 is far from either threshold, although such historical guideposts cannot determine the economy’s future on their own.
The recent monthly pattern illustrates why smoothing is useful. The CFNAI stood at +0.01 in June and +0.12 in July, slipped to −0.08 in August and returned to +0.07 in September. Three of those four readings were positive, but none established a sustained period of growth far above the historical average. September improved the picture without eliminating the short-term variation.
One additional check comes from manufacturing capacity. The Federal Reserve Board put overall industrial capacity utilization at 76.9% in September, still 2.5 percentage points below its long-run average. Rising production alongside utilization below its historical norm is consistent with an industrial sector gaining output without operating close to its usual capacity benchmark.
Revisions leave room for a different reading of momentum
The month-to-month comparison is also affected by revisions. August was initially reported at −0.04 but is now shown at −0.08, while July was revised upward from +0.08 to +0.12. Those changes make September’s rebound look larger relative to August and alter the recent path of the index, even though the latest reading remains positive.
Revisions are part of the way this indicator is constructed. Its underlying economic series can be updated as statistical agencies publish more complete estimates or correct earlier data, and those adjustments can change past CFNAI values. For that reason, the latest number is best read alongside the updated history rather than compared only with figures published in previous headlines.
September’s result offers evidence that national activity was a little stronger than its long-run trend, supported by production and a modest improvement in orders and inventories. It offers less evidence of a synchronized pickup in household demand or labor-market activity. Those sector differences are important for anyone using the index to judge whether the economy’s resilience is broadening.
The Chicago Fed has scheduled its next CFNAI release, covering October data, for November 23, 2026. That report will show whether the production-led improvement persisted and whether the weaker consumption and housing contribution changed direction, with the usual possibility that September’s figures will be revised.
More News
Latest News
View all news- Verizon Raises 2026 Earnings Outlook as Postpaid Phone Adds Reach 406,000
- Strive Launches $1 Billion Preferred-Stock Sales Program With Bitcoin Among Planned Uses
- Treasury Updates Sanctions Reporting Guidance for Banks Handling Blocked and Rejected Payments
- Bank of Hawaii Expands Share Buyback Program by $200 Million as Quarterly Profit Rises
- Japan Announces ¥250 Billion Climate-Transition Bond Offering for November
