Sweden’s Riksbank Raises Interest Rate to 2% as Inflation Risks Intensify
The quarter-point increase takes effect November 11 as the central bank warns that stronger domestic activity and higher energy costs could lift inflation above target.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy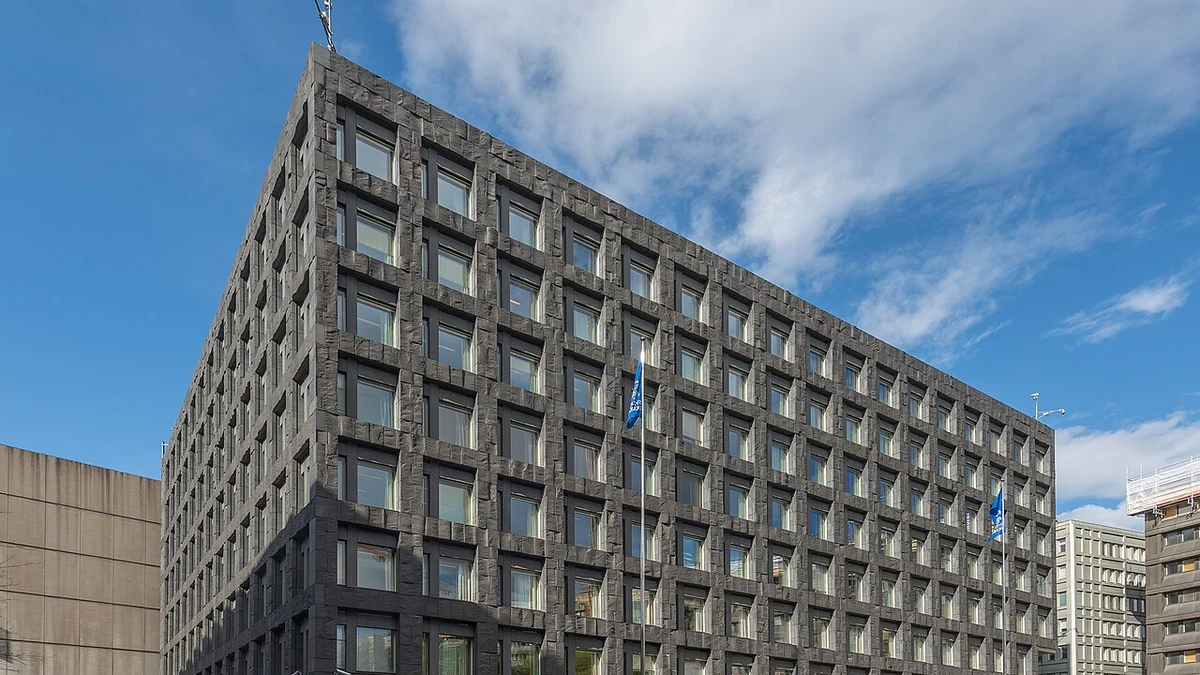
Sweden’s Riksbank raised its policy rate by a quarter of a percentage point to 2% on Wednesday, November 4, citing the risk that rising energy costs and a strengthening economy will push inflation above its target. The move takes the benchmark rate from 1.75% to 2% even though the country’s latest headline measure of inflation remains below the central bank’s 2% objective.
The new rate takes effect on November 11. Officials also indicated that further increases are likely over the coming year if the economy and inflation develop as they currently expect. That guidance is conditional, rather than a commitment to raise borrowing costs at any particular meeting.
In its November monetary policy announcement, the Riksbank pointed to supply disruptions tied to the war in the Middle East, higher energy prices and an improving Swedish economy. The decision reflects a judgment about where inflation is heading, not a claim that its preferred inflation measure has already exceeded target.
The increase follows a September decision to leave the rate at 1.75%. At that meeting, the central bank had already warned that rates would probably need to rise if its forecast held. The latest step turns that warning into an actual increase, with the effect on households and businesses due to feed through as lenders adjust their terms.
Why the low inflation figure did not prevent a rate increase
Sweden’s consumer price index with a fixed interest rate, known as CPIF, rose 1.5% in the year through September, compared with 0.7% in August. The CPIF is the measure the Riksbank uses for its inflation target. On the surface, a reading below 2% might appear to argue against tighter monetary policy, but the central bank says the published number is being held down by temporary government fiscal measures.
Adjusting for the direct effects of those measures, the Riksbank put September CPIF inflation at 3%. It also cited a separate measure that strips out energy prices and those temporary effects, which stood at 1.6% and was slightly lower than officials had expected. The 3% and 1.6% figures are not interchangeable versions of the same index: each adjusts for different influences on prices. Neither should be presented as the official headline CPIF reading.
Data published by Statistics Sweden show how much energy affected the September numbers. Electricity prices increased 11.7% from August to September, while fuel prices rose 13.3% during the month. Over the previous 12 months, electricity costs were 17% higher and fuel prices 20% higher. By contrast, food and nonalcoholic beverage prices were lower than a year earlier, helping restrain broader inflation.
Statistics Sweden also reported CPI inflation of 1.1% in September, compared with CPIF inflation of 1.5%. Those two measures differ partly because the CPIF holds the interest-rate component of mortgage costs fixed. This distinction matters when the central bank itself is changing interest rates: its inflation objective is framed around CPIF rather than the conventional CPI.
For policymakers, the concern is that higher imported energy and other supply costs could persist or pass into prices elsewhere in the economy. The Riksbank described global inflation pressure as elevated, with disruptions connected to the Middle East conflict still affecting supply. It did not say that a broad rise in underlying inflation had already occurred. Instead, the rate decision is intended to reduce the risk of price growth picking up as demand becomes stronger.
An improving economy changes the balance of risks
The Swedish economy is recovering, although the most recent figures are mixed. Statistics Sweden’s preliminary GDP indicator showed output expanding by 0.4% in the third quarter from the preceding three months. Compared with the same quarter a year earlier, GDP was up 2.8% on a calendar-adjusted basis. Those gains came despite a 0.7% month-on-month decline in September, showing that the recovery has not been uniformly strong.
The labour market has also shown improvement. Statistics Sweden reported 5.398 million people employed in the third quarter, an increase of 74,000 from a year earlier. Its seasonally adjusted and smoothed series indicated higher employment and a higher employment rate compared with adjacent quarters. Unemployment remained substantial, however, at 8.7% on that same adjusted basis.
The Riksbank said preliminary third-quarter growth and employment figures were broadly consistent with its assessment that economic conditions are moving toward normal levels next year. It also noted weaker household sentiment in October, even as business confidence improved. That split illustrates why the bank is not treating the recovery as complete.
Stronger activity can support household income and business demand, but it can also make it easier for businesses to pass higher costs on to customers. The bank’s concern is the overlap between demand recovering at home and cost shocks arriving from abroad. Acting before inflation becomes more widespread is the rationale behind a hike made when the most familiar inflation measure is still below target.
Interest-rate increases can work in the opposite direction by making credit more expensive and discouraging some borrowing and spending. For Swedish households with mortgages and companies relying on financing, the effect will depend on individual contracts and the rates set by lenders. The policy-rate change itself does not establish how much any particular borrower’s monthly payment will increase.
Further tightening is possible, but the December decision is open
The Riksbank said additional increases are likely in the coming year if its projections for inflation and economic activity remain valid, consistent with the rate path it published in September. That earlier assessment showed a gradually higher policy rate into 2027, but the forecasts represent expectations, not decisions that have already been made.
There are risks on both sides of the outlook. Supply disruptions could last longer than expected and put more pressure on prices, while stronger economic activity could add to inflation. Weaker household demand or a less convincing improvement in the labour market could instead limit the case for further tightening. The central bank also flagged international economic and geopolitical uncertainty as potential constraints on growth.
The Riksbank expects its policy stance to bring inflation back toward 2% after a period above target. Its November policy update did not introduce an entirely new set of economic forecasts. The next full Monetary Policy Report is due alongside the December decision, giving officials an opportunity to reassess inflation, growth and the expected path of interest rates with updated projections.
The minutes of the November monetary policy meeting are scheduled for November 10 and should provide more detail on the Executive Board’s discussion. The next meeting is set for December 15, with the rate decision and new forecasts scheduled for publication on December 16. Until then, the bank’s position is that another increase is plausible if the data continue to support its outlook, rather than inevitable.
More from Banking
Latest News
View all news- U.S. Private Employers Add 86,000 Jobs in October, ADP Reports
- U.S. Energy Department Awards Contracts for 300,000 Barrels of Heating Oil From Emergency Reserve
- Justice Department Update Puts Expanded Radiation-Exposure Compensation Awards at $925.5 Million
- U.S. Services Growth Slows as October ISM Index Falls to 54.5
- McDonald’s U.S. Comparable Sales Slip 0.2% Despite Higher Quarterly Profit