
Bank of England Publishes Next-Generation Retail Payments Infrastructure Consultation Response
The Bank received 121 submissions and outlined a modular payments core, while questions about fraud safeguards, shared services and migration remain open.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy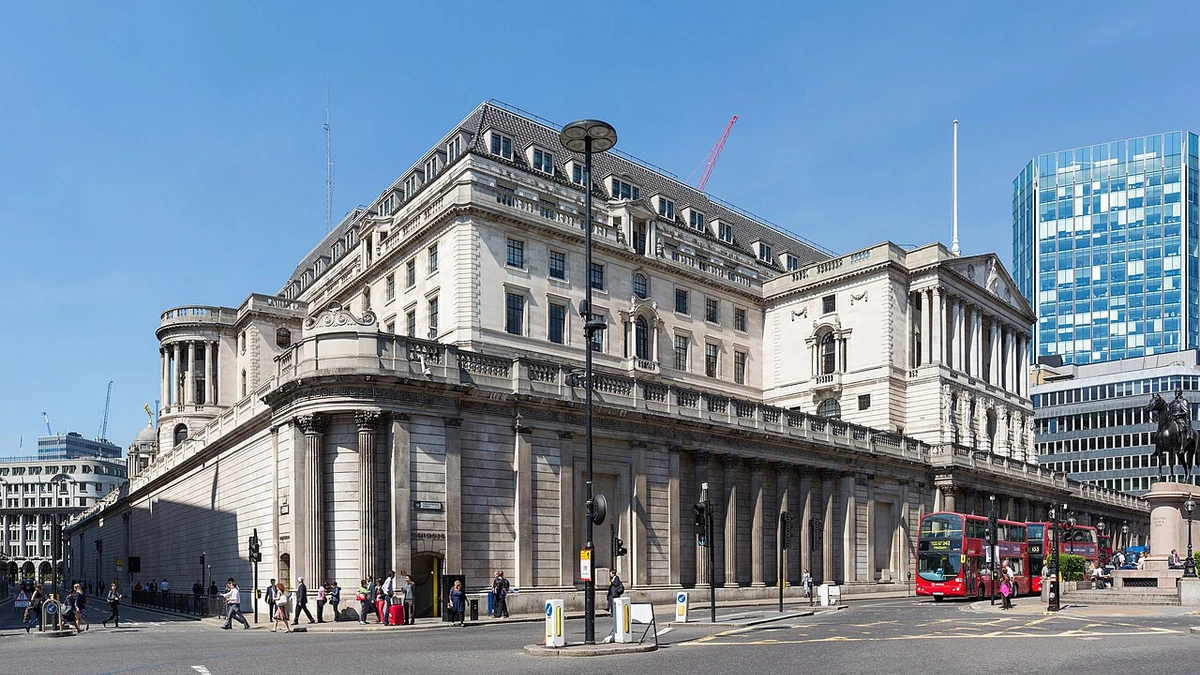
The Bank of England has published the response to a consultation on the next generation of UK retail payments infrastructure, outlining an approach built around a common, adaptable core for moving payment information between institutions. The proposals are intended to support existing services and new ways of paying, but they do not amount to a final technical design or a timetable for switching on a replacement system.
The bank-chaired Retail Payments Infrastructure Board (RPIB) received 121 written responses, including 110 from organizations and 11 from individuals. Participants broadly supported modernizing the infrastructure, according to the board, while identifying unresolved questions about the boundary between the shared core and other services, protection against fraud, and how a transition could be carried out safely.
The consultation response published November 4 sets out prospective design choices for a blueprint that the board intends to hand to an industry-led Delivery Company in spring 2027. Detailed design, procurement and construction would follow that handover. The document therefore signals a direction for the project, not an approved operating model with a committed launch date.
A common core with room for different payment services
The central proposal is a single modular architecture serving several payment products rather than separate infrastructure built around each individual service. A common core would handle messaging, clearing and other shared capabilities, leaving banks and payment providers room to offer different products to customers. Respondents generally favored a relatively narrow core, although they disagreed over how much functionality should be shared centrally.
That distinction matters for both cost and competition. Putting a capability inside the shared infrastructure could make it available consistently across the market, but it could also increase the size and complexity of the central system. Leaving it to payment providers may encourage different solutions, yet could create gaps when a service needs to work across multiple institutions. Fraud tools, directories, payment aliases and data sharing were among the functions on which respondents expressed different views.
The proposed design would provide common access arrangements for institutions connecting to the core. Connectivity options could vary to reflect different participants, subject to common security and resilience standards. The Bank also proposes using ISO 20022 as the baseline messaging approach, with common data definitions and implementation rules. Product-specific arrangements could add information where their services require it, while the detailed message formats remain to be decided.
A proposed orchestration layer would validate, route and sequence payments, including batches. It could also help with migration by supporting a temporary bridge from the existing Faster Payments and Bacs message formats to ISO 20022. The response does not propose permanently embedding those older standards in the new architecture; even the transitional role of the layer still needs further design work.
Final settlement would connect to the Bank of England’s Real-Time Gross Settlement service and take place in central bank money. For many payment arrangements, the Bank envisages that prefunded net settlement could remain suitable, with the shared core coordinating obligations and seeking settlement. How liquidity is pooled or reused across payment products, and precisely how often settlement occurs, would require additional analysis.
Fraud safeguards and new forms of money pose design choices
The consultation also considered interoperability between different forms of regulated money. Its proposed model would allow someone to pay using one form of money while the recipient receives another at par, with eventual settlement in central bank money. Respondents largely supported that objective, but some questioned whether every new payment type, including certain tokenized deposits, should necessarily pass through the future core.
Making that work will involve more than connecting systems. Participants pointed to consistent technical standards, richer payment data, rules for access and comparable protections for people using different services. They also asked for sufficient flexibility to accommodate payment arrangements that are still developing. Those are design goals rather than guarantees that all future forms of digital money will be supported at launch.
On fraud, respondents backed better information to check who is being paid, improved payment-status visibility and more useful data for detecting suspicious activity. Verified payee details, traceability and shared warning signals featured in the feedback. The Bank has not settled whether services such as directories and fraud checks belong inside the core or in shared arrangements elsewhere in the payments ecosystem.
Some customer safeguards cannot be created by a clearing system alone. Refunds, disputes, reimbursement and liability rules depend on the schemes and products built around it. That is particularly relevant to proposed account-to-account payments at the point of sale: merchants need reliable confirmation that payment has been made, while customers need workable arrangements when an order goes wrong or a payment is disputed. The response recognizes that infrastructure improvements alone would not make such a service commercially viable.
Accessibility also appeared in the consultation feedback. Respondents raised the needs of older and disabled users, assisted payment journeys and the continued availability of suitable non-digital options. The board will need to account for these concerns without treating every consumer-facing feature as a function of the core. The broader framework of schemes, provider obligations and customer services remains relevant to whether the new system improves payments in practice.
A phased migration comes before any system replacement
Industry feedback strongly favored moving in stages instead of replacing existing infrastructure in a single changeover. Respondents wanted the order of migration to reflect risk, cost, complexity and participants’ readiness, backed by substantial testing. They differed on whether transition should be organized by payment type, technical capability or groups of institutions, and on the role of fixed deadlines or mandates.
The existing Faster Payments and Bacs services must remain dependable during the project. Direct Debit mandates, large-scale payroll and government payments create dependencies that cannot simply be moved without planning. Respondents cautioned against retiring current systems before replacements have proved reliable, and the board has not published a detailed migration schedule. The timing of any eventual switch will depend in part on decisions that have yet to be made about the target system.
The redesign sits within the government-backed strategy for future retail payments infrastructure, which established public and private sector responsibilities for developing the next generation of UK payments. The RPIB leads the high-level design, while the industry-led Delivery Company is expected to take responsibility for the subsequent detailed design and build. Pay.UK retains its role operating the current interbank payment systems during that work.
The next stage begins with joint work by Bank staff, the Design Authority and industry participants to refine the proposed architecture. The board calls this process co-creation and plans to carry it through to spring 2027. Outstanding decisions include which shared services belong in the core, the precise messaging and settlement arrangements, and the controls needed for a safe transition. The next defined milestone is the handover of the high-level blueprint, rather than an operational go-live date.
More from Banking
Latest News
View all news- U.S. Private Employers Add 86,000 Jobs in October, ADP Reports
- U.S. Energy Department Awards Contracts for 300,000 Barrels of Heating Oil From Emergency Reserve
- Justice Department Update Puts Expanded Radiation-Exposure Compensation Awards at $925.5 Million
- U.S. Services Growth Slows as October ISM Index Falls to 54.5
- McDonald’s U.S. Comparable Sales Slip 0.2% Despite Higher Quarterly Profit
