
U.S. Treasury Announces $125 Billion Refunding, Including $28 Billion in New Cash
Treasury will hold its major note and bond auction sizes steady as it schedules next week’s refunding and prepares a new seven-year note format.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy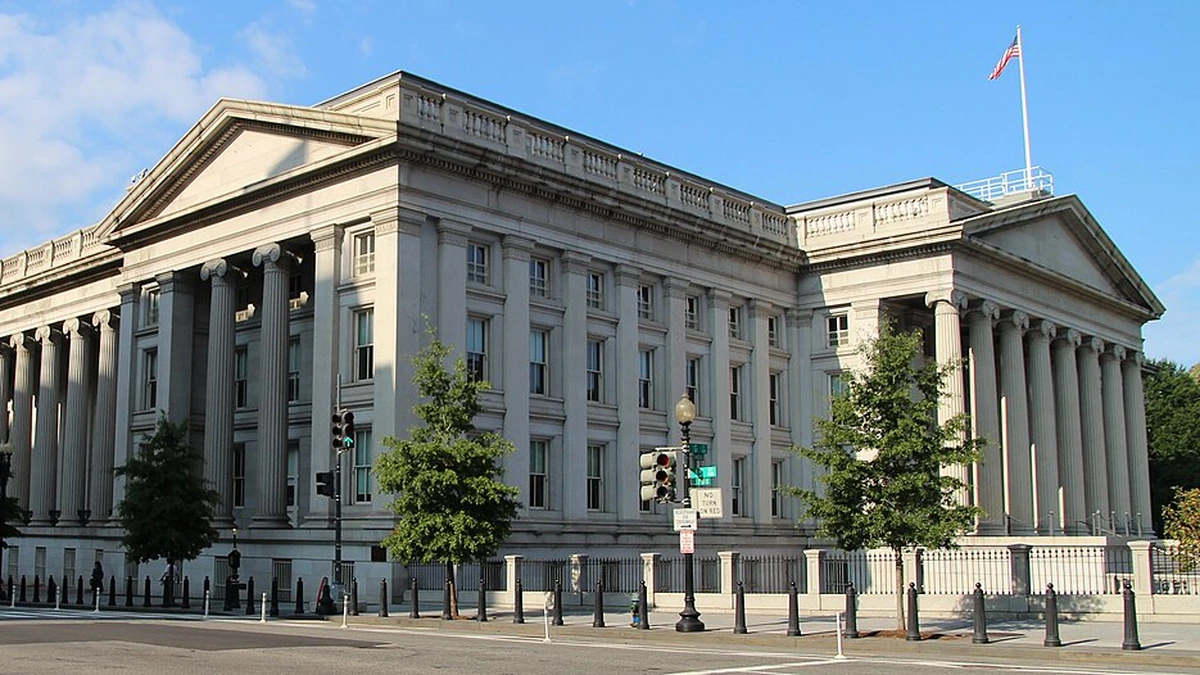
The U.S. Treasury said Wednesday it will sell $125 billion of notes and bonds next week, refinancing approximately $97 billion of privately held securities coming due in mid-November and raising about $28 billion in new cash. The size of the quarterly refunding is unchanged from August, even as the government faces considerable borrowing requirements through the end of the year.
The offering consists of $58 billion in three-year notes, $42 billion in 10-year notes and $25 billion in 30-year bonds. Most of the proceeds will replace maturing debt rather than provide additional funding. That distinction is central to the announcement: the $125 billion is the total face amount Treasury plans to sell, while $28 billion is its estimate of the cash raised beyond the amount needed for the specified maturities.
In its November 4 refunding statement, Treasury scheduled the three-year auction for Monday, November 9, the 10-year auction for Tuesday, November 10, and the 30-year auction for Thursday, November 12. Each sale is set for 1 p.m. Eastern and will be conducted on a yield basis. All three securities are scheduled to settle on November 16, following the November 15 maturities being refinanced.
Treasury holds coupon auction sizes steady
Beyond the three refunding auctions, Treasury indicated that it expects to maintain its current nominal coupon and floating-rate note auction sizes for the next several quarters. The department said existing sizes leave it positioned to manage changes in fiscal needs and the Federal Reserve’s securities portfolio. It did not announce a broad increase in scheduled note or bond sales.
The November-through-January financing table shows monthly two-year note auctions at $69 billion, five-year notes at $70 billion and seven-year notes at $44 billion. The three-year offering remains $58 billion each month. Ten-year and 30-year amounts vary between new issues and reopenings, but the planned pattern is the same as in the preceding quarter.
August’s quarterly refunding also totaled $125 billion, split into the same $58 billion, $42 billion and $25 billion offerings. The difference lies in the debt coming due: that announcement covered about $96.3 billion of maturities and projected $28.7 billion in new cash. November’s slightly smaller new-cash component therefore does not represent a reduction in the announced sizes of the three auctions.
Treasury is still assessing how its mix of borrowing might evolve. It pointed to purchases of Treasury bills by the Federal Reserve’s System Open Market Account, rising private-sector demand for bills and potential changes in the demand for longer-dated securities. The department said it would consult market participants and weigh financing costs against the risks of different issuance patterns.
There is a modest change in the wording of its guidance. In August, Treasury said it expected to maintain coupon and floating-rate note sizes for “at least the next several quarters.” The new statement says “for the next several quarters.” That narrower phrasing leaves future decisions open, but Treasury has not announced an effective date or amounts for any subsequent change in coupon auction sizes.
The overall borrowing picture is larger than this one refunding. In separate estimates published November 2, Treasury projected $618 billion in privately held net marketable borrowing for the October-to-December quarter, assuming an $850 billion cash balance at year-end. That forecast is $10 billion below its August estimate, mainly because the government started the quarter with more cash than expected, partly offset by weaker projected net cash flows.
Without the effect of that higher opening cash balance, Treasury said the fourth-quarter borrowing estimate would be $24 billion above the August projection. For January through March 2027, it expects $800 billion in privately held net marketable borrowing, assuming a $1 trillion cash balance at the end of March. These quarterly forecasts cover financing across the marketable debt program and should not be confused with the $28 billion new-cash figure attached to next week’s three auctions.
Seven-year notes will move to quarterly new issues
The most concrete change to the auction format involves the seven-year Treasury note. Beginning in March 2027, Treasury plans to issue a new seven-year security once per quarter and reopen that same security in each of the following two months. This brings the seven-year issuance pattern closer to the structure already used for 10-year notes.
New seven-year issues are scheduled for March, June, September and December, with reopenings in the intervening months. The first cycle will begin with a March 2027 new issue, followed by reopenings in April and May. A reopening sells additional amounts of an existing security instead of creating a separate new issue with its own maturity date.
Crucially, Treasury is not eliminating monthly seven-year auctions. It said those sales will continue toward the end of each month, with issuance and maturity at month-end. The announced November-to-January auction sizes are also unchanged. The move adjusts how successive monthly offerings are organized, rather than ending the supply of seven-year notes in two months out of every three.
Buyback plans expand as short-term issuance shifts seasonally
Treasury also outlined a tentative program of purchases of outstanding debt during the upcoming refunding quarter. It anticipates buying up to $70 billion of off-the-run securities to support market liquidity, plus up to $25 billion of securities in the one-month-to-two-year maturity range for cash management. These figures are prospective ceilings, not amounts that Treasury has committed to purchase.
The planned liquidity-support ceiling is higher than the $38 billion set out in the August quarterly refunding statement; the separate $25 billion cash-management ceiling is unchanged. Treasury had also increased the maximum size of some longer-dated liquidity-support operations in September. The department said it continues to evaluate the frequency, maximum size and eligible securities for future buybacks.
Buybacks serve a different purpose from the new debt sales. Purchases of older, less actively traded issues can provide liquidity to that part of the Treasury market, while shorter-maturity purchases can help manage cash flows. Treasury noted in its borrowing estimates that buybacks are not expected to materially change privately held net marketable borrowing, because the securities bought back are generally replaced by new issuance.
For Treasury bills, the department expects benchmark auction sizes to stay at current levels into late November and said it might issue a short-dated cash management bill around month-end. It anticipates reducing shorter-dated bill sizes in December, when corporate and non-withheld tax receipts are expected, before increasing bill offerings across maturities in January to meet seasonal cash outflows. Those adjustments provide room to respond to cash needs without immediately changing regular coupon auction sizes.
Inflation-protected securities are also part of the financing plan. Treasury intends to maintain a $19 billion reopening of 10-year TIPS in November, a $24 billion reopening of five-year TIPS in December and a $21 billion new 10-year issue in January. The announced amounts are unchanged from its current TIPS auction schedule.
Treasury assumes its cash balance will be $850 billion at the end of December, although it estimates the Treasury General Account could reach about $1.025 trillion, plus or minus $50 billion, in late November and again in late January as large outflows approach. The scheduled November refunding auctions are the immediate test of the announced supply, and the department’s next quarterly refunding announcement is set for February 3, 2027.
More from Investing
Latest News
View all news- U.S. Private Employers Add 86,000 Jobs in October, ADP Reports
- U.S. Energy Department Awards Contracts for 300,000 Barrels of Heating Oil From Emergency Reserve
- Justice Department Update Puts Expanded Radiation-Exposure Compensation Awards at $925.5 Million
- U.S. Services Growth Slows as October ISM Index Falls to 54.5
- U.S. Mortgage Applications Fall 1.2% Despite 30-Year Rate Easing to 7.30%
