
EIA Finds U.S. Refiners Shifting Production Toward Diesel and Jet Fuel
U.S. refiners have been trimming gasoline yields and pushing more output into diesel and jet fuel as stronger margins and tighter global supplies make middle distillates more attractive, according to EIA data.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy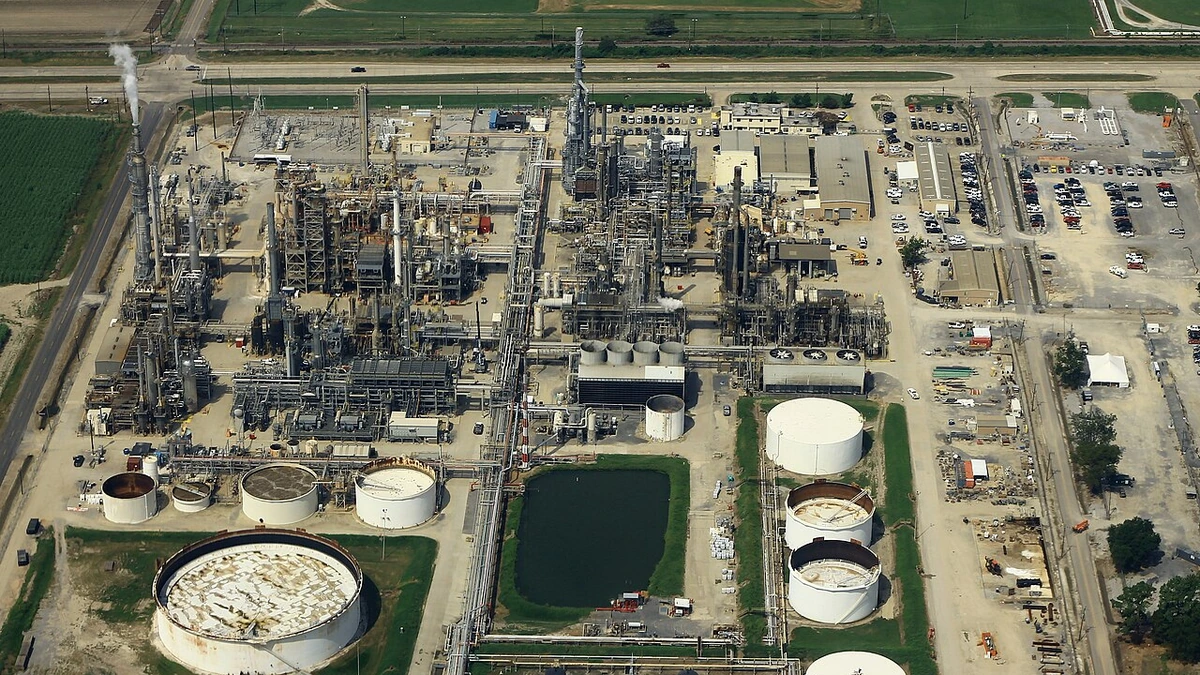
U.S. refiners are redirecting a larger share of their output away from gasoline and toward diesel and jet fuel, a shift the Energy Information Administration said reflects unusually strong margins for those middle distillates this year.
The change matters because the U.S. refining system is normally geared first toward gasoline. American drivers remain the core market for refiners, and a typical barrel of crude processed in the United States yields a larger share of motor gasoline than almost any other product. This year, however, diesel and jet fuel have been lucrative enough to pull refiners in a different direction.
In an analysis published Thursday, the EIA said data from its latest Today in Energy report, which uses figures through August from the Petroleum Supply Monthly, show gasoline yields have dropped materially in 2026 while distillate fuel oil and kerosene-type jet fuel yields have increased. Distillate fuel oil is the category that includes diesel, and together with jet fuel it sits in the middle range of products that come out of the refining process.
That is not a cosmetic adjustment. Refinery yields describe how much of each major product refiners can draw from every barrel of crude oil they run. A change of a percentage point or two across the national refining fleet can alter supplies available to motorists, trucking companies, industrial users, airlines, exporters, and the wholesalers that supply them.
Higher margins are pulling barrels into middle distillates
EIA said particularly high refining margins for distillate fuel oil and jet fuel have been a major driver behind the shift. Although gasoline prices have remained elevated, refiners have had stronger financial incentive to maximize production of diesel and jet fuel because global supplies of those products have been constrained for much of the year.
That pricing signal has been visible in several EIA releases. In a separate analysis published in October, the agency said U.S. refinery utilization averaged more than 95% of capacity between May and September, the highest for those months since 1998. Even with such strong run rates, the system did not simply flood the market with gasoline. Instead, refiners leaned harder into products that were generating better returns, especially diesel.
The agency’s July review of second-quarter petroleum markets helps explain why. EIA said distillate and jet fuel crack spreads, a common proxy for refinery margins, were more than double year-earlier levels in the second quarter, while the gasoline crack spread was up 60% from a year earlier. That gap created a sustained incentive to alter yields where refinery configuration and crude slates allowed.
Tightness in global refined-product markets has reinforced the move. During the second quarter, EIA estimated U.S. distillate exports averaged 1.56 million barrels a day, 30% above the five-year average, while jet fuel exports averaged 356,000 barrels a day, more than double the five-year average. Higher overseas demand gave U.S. refiners another reason to prioritize middle distillates even as domestic gasoline demand remained important.
What the yield data show
The EIA said the U.S. refining fleet typically produces gasoline yields in a 45% to 50% range. Put another way, every 100 barrels of crude processed usually generate about 45 to 50 barrels of gasoline. Motor gasoline, distillate fuel oil, and jet fuel together generally account for about 85% to 90% of total petroleum products produced by U.S. refiners, so movements among those three categories reveal a lot about how plants are responding to market signals.
This year, gasoline’s share has been notably weaker. From January through August, refinery gasoline yields averaged less than 45%, according to the EIA, and the monthly yield was below the five-year low in every month of 2026 so far. That is a striking pattern for a refining system that usually emphasizes gasoline so heavily.
Distillate fuel oil moved the other way. EIA said those yields were generally higher than last year and above the five-year average in every month of 2026 through August. The gains may look modest in percentage terms, but across a refining fleet that processes millions of barrels a day, even small shifts translate into meaningful additional diesel supply.
Jet fuel has shown an even clearer breakout. According to EIA, the U.S. refining fleet exceeded an average jet fuel yield of 12% for the first time in March 2026, and the fleetwide average remained at or above 12% through the latest August data. Jet fuel yields were already running near five-year highs for much of 2025, and stronger margins this year have kept refiners focused on preserving that output.
The production figures line up with those yield trends. In its July market review, EIA estimated second-quarter jet fuel production was 24% above the five-year average, while distillate production was 5% higher. Motor gasoline production, by contrast, was only 1% higher. Refiners were not cutting total throughput. They were extracting a different mix of fuels from the crude they processed.
Why the shift matters for fuel markets
For consumers, the most immediate implication is that refinery economics do not always point in the same direction as headline gasoline prices. Even when gasoline prices are high, refiners may still prefer to direct marginal barrels into diesel or jet fuel if those products offer better returns. Trucking, industrial demand, airline consumption, and export opportunities can all compete with the motor-fuel market for refinery attention.
For the industry, the latest EIA analysis shows how flexible the U.S. system can be within its physical limits. Refiners cannot fully redesign output overnight, but they can alter operating conditions, crude selection, and processing emphasis enough to change the national product slate. That flexibility has become especially valuable in a year marked by disrupted international petroleum flows, tight distillate availability, and strong export pull for products that other regions needed.
There are limits, though. EIA noted in its October analysis that total U.S. refining capacity is still about 4% below its 2019 level, even though plants have been running at very high utilization rates. That means the industry has had to squeeze more out of a smaller system. The result is a balancing act: keeping gasoline supply adequate for the domestic market while also meeting profitable demand for diesel and jet fuel at home and abroad.
The next few months will show whether this product mix holds. Distillate demand typically strengthens in the fall and winter, and jet fuel margins will remain important if export demand stays healthy. EIA’s August data suggest refiners were still favoring middle distillates late into the summer. Future Petroleum Supply Monthly releases will indicate whether that pattern persists or whether a softer margin environment allows gasoline yields to move back toward their more typical range.
More News
Latest News
View all news- ConocoPhillips Raises Quarterly Dividend 11% After Q3 Earnings Reach $4 Billion
- Southern Company Q3 Profit Rises to $2 Billion as Revenue Grows 13%
- U.S. Private Employers Add 86,000 Jobs in October, ADP Reports
- U.S. Energy Department Awards Contracts for 300,000 Barrels of Heating Oil From Emergency Reserve
- Justice Department Update Puts Expanded Radiation-Exposure Compensation Awards at $925.5 Million
