
Swiss Financial Regulator Finalizes Tougher Anti-Money-Laundering Rules for Banks
FINMA’s revised ordinance and updated bank and insurance due-diligence standards take effect January 1, with a four-month transition for the industry codes.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy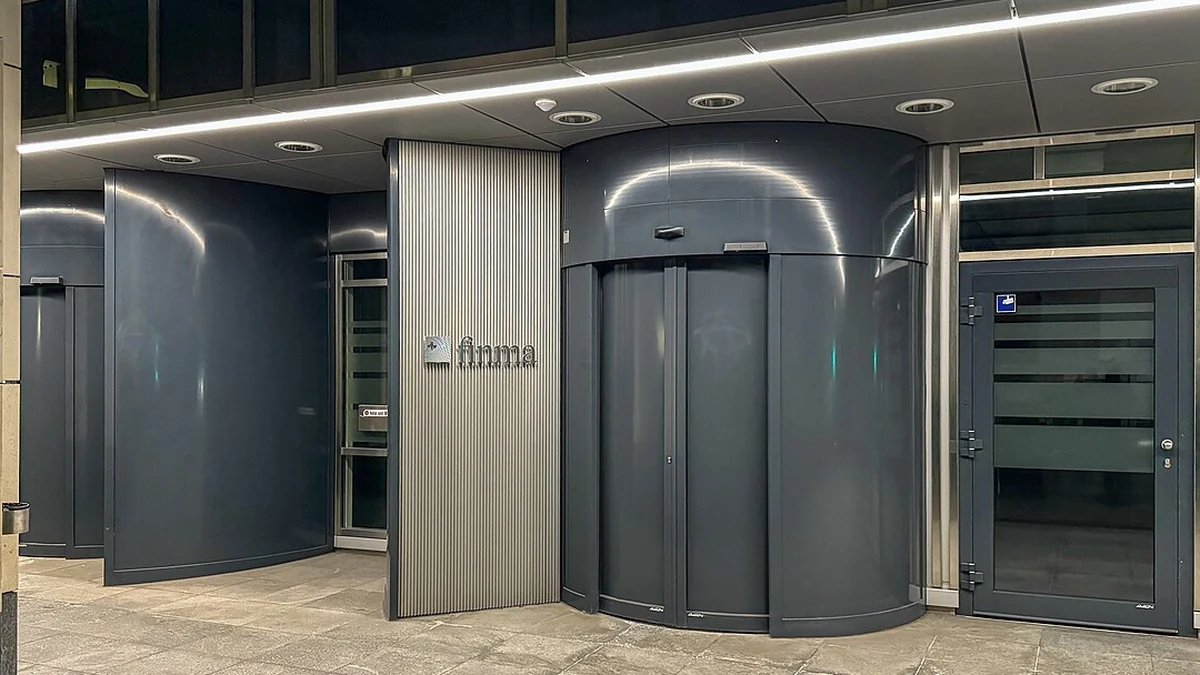
Switzerland’s financial regulator has finalized a revised set of anti-money-laundering requirements for banks and other financial institutions, with changes covering customer ownership checks, relationships with foreign banks and measures to prevent sanctions breaches. The new FINMA ordinance and updated industry due-diligence standards will take effect on January 1, 2027.
The Swiss Financial Market Supervisory Authority, known as FINMA, said Tuesday that it had completed a partial revision of its Anti-Money Laundering Ordinance after consulting on the proposed changes earlier this year. Its board also recognized revised due-diligence rules for banks and the Swiss insurance sector as minimum standards.
FINMA’s announcement of the final rules makes an important distinction about timing: the two sets of industry self-regulation each have a four-month transition period, but the regulator did not announce the same general grace period for its own ordinance. The package fits into a wider overhaul of Swiss money-laundering law that has already begun to take effect.
Foreign correspondent banking requirements clarified
One change made after the consultation addresses correspondent banking relationships with foreign institutions. Correspondent banking allows one bank to provide account and payment services to another, often enabling payments across borders without the two institutions having branches in the same country. Such arrangements require banks to understand whose funds are moving through their services and how account access is structured.
FINMA said the final version clarifies the reach of Article 37, paragraph 5, of its ordinance. The provision applies only to customers with direct access to accounts at the correspondent bank. That qualification is material because the existence of a foreign-bank relationship does not, by itself, establish that a customer can access the correspondent bank’s accounts directly.
During its consultation launched in May, the regulator had described proposed safeguards for payments made through transitory accounts on behalf of a customer bank’s clients. Those safeguards included ensuring that necessary client information could be supplied on request. The November announcement focuses on the narrower direct-access clarification made in the final text, rather than suggesting every correspondent relationship falls under the same provision.
For banks, the practical task is to distinguish the different ways clients use accounts, then apply the relevant controls to the actual arrangement. The revised wording also matters for compliance reviews because it identifies a condition that can be checked: whether a customer has direct access to the correspondent bank’s accounts. FINMA did not attach a sector-wide compliance cost estimate to its announcement.
Ownership transparency and sanctions controls receive closer attention
Another part of the revision concerns the ability of financial institutions to understand their customers’ ownership and control structures. FINMA amended the explanatory notes to clarify how that expectation works alongside existing requirements concerning complex structures and domiciliary companies. The notes also address the risk-based approach and the records institutions must keep.
The distinction is not that banks are being asked to identify beneficial owners for the first time. Identifying the person who ultimately owns or controls assets is already a core Swiss anti-money-laundering obligation. The new material provides more detail about how institutions should assess less straightforward ownership arrangements and document their understanding of the risks involved.
FINMA also expanded its explanations of measures intended to prevent breaches of compulsory restrictions under Switzerland’s Embargo Act. The guidance addresses how rules on monitoring business relationships and financial transactions apply by analogy to these sanctions-related controls. This extends the compliance discussion beyond spotting suspicious money flows to the processes institutions use when checking activity against applicable restrictions.
Those requirements sit within an existing supervisory system. Swiss financial intermediaries must identify contracting parties and beneficial owners, examine unusual activity and apply greater scrutiny to higher-risk relationships. Suspected money laundering can trigger reporting to the Money Laundering Reporting Office Switzerland. FINMA oversees compliance at banks and other directly supervised institutions, using audits and its own supervisory reviews where appropriate.
The regulator’s publication should therefore be read as a targeted set of amendments and clarifications, not as the creation of an entirely new banking compliance regime. Its final notice identifies specific changes and points to the associated explanatory documents; it does not say that every existing due-diligence obligation has been replaced.
January deadline follows a broader change to Swiss law
Alongside the FINMA ordinance, the regulator approved revised versions of the Swiss banks’ due-diligence code and the rules of the Swiss Insurance Association’s anti-money-laundering self-regulatory organization as minimum standards. All three take effect on January 1, 2027. Each industry rulebook provides a four-month transition period, a detail that institutions must distinguish from the ordinance’s effective date.
The new standards follow changes made at the federal level. Switzerland’s revised Anti-Money Laundering Act and a separate law on the transparency of legal entities came into force on October 1, 2026. The State Secretariat for International Finance explains that the broader reform establishes a federal register of beneficial owners and brings certain advisory services within the scope of anti-money-laundering law.
The transparency register is a separate part of that legislative overhaul, not a new database being created by FINMA’s November ordinance. Its purpose is to give specified authorities and covered parties access to information about who ultimately owns legal entities. That provides a broader policy backdrop for the regulator’s emphasis on understanding ownership and control structures at individual financial institutions.
Some advisers are now covered by the anti-money-laundering framework because of the work they perform, including certain activities involving real estate or the establishment and structuring of legal entities. FINMA said the expansion also makes it necessary to revise its existing circular on activity as a financial intermediary. For now, it has issued separate supervisory guidance explaining the circular’s scope and responsibilities for oversight of advisory work.
These changes are also being made ahead of Switzerland’s next evaluation by the Financial Action Task Force, the international standard-setter for anti-money-laundering and counter-terrorist-financing measures. The Swiss Federal Council has said that evaluation is scheduled for 2027–2028. The timing helps explain why the country’s legislative amendments and FINMA’s implementing rules are arriving in close succession, although they do not all have the same commencement dates.
For institutions preparing for the January start, the distinction between the revised FINMA ordinance and the two industry standards is central. Banks will need to assess the final correspondent-account provision, the ownership-documentation guidance and the sanctions-related explanations against their current procedures. Insurers have their own revised minimum standards to implement. The next fixed milestone is January 1, when the updated ordinance and both industry codes become effective.
More from Banking
Latest News
View all news- U.S. Consumer Prices Rise 0.4% in October as Inflation Remains Elevated
- India’s Unemployment Rate Falls to 5.1% as Rural Job Market Improves
- U.S. Real Hourly Earnings Stall in October as Inflation Offsets Wage Gains
- Fed Governor Waller Backs December Rate Increase Despite Stable U.S. Labor Market
- U.S. Small-Business Confidence Holds Near Long-Term Average as Tax Concerns Rise
