
Ace Hardware Reports Record $2.5 Billion Third-Quarter Revenue as Net Income Jumps 42.5%
A $32.2 million tariff refund helped boost reported profit, while larger average purchases and new locations supported sales despite fewer customer transactions.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy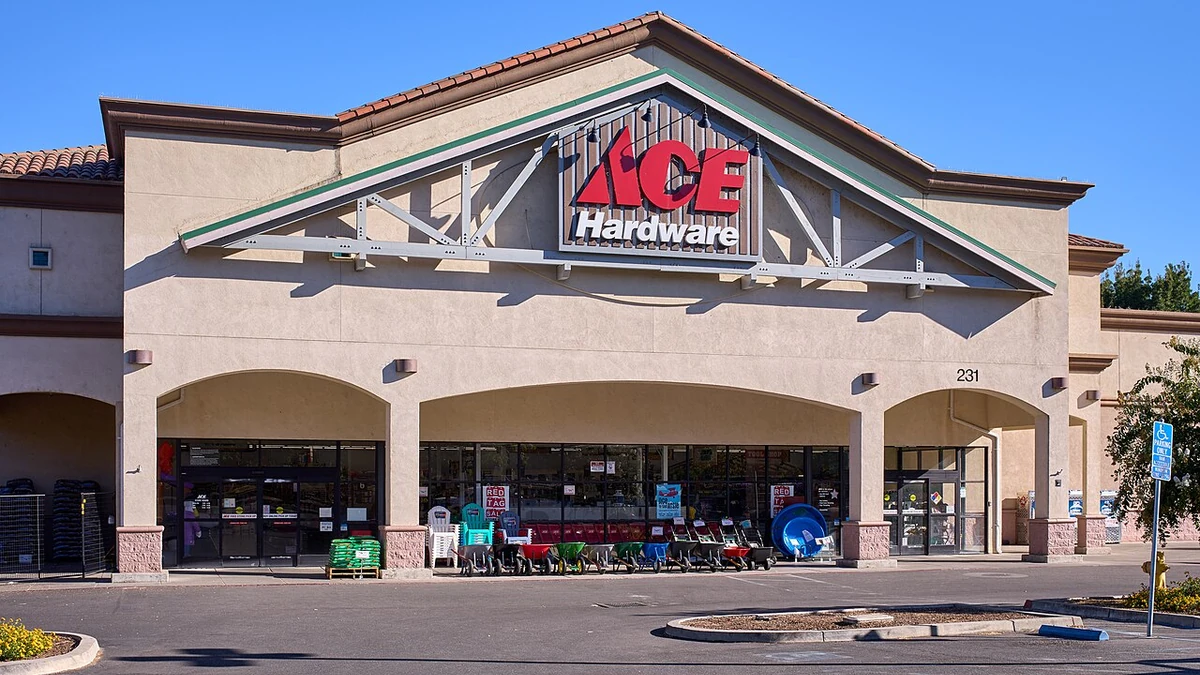
Ace Hardware reported record third-quarter revenue of $2.54 billion, up 2.1% from a year earlier, as net income surged 42.5% to $142.1 million. The earnings increase was far larger than the growth in sales, partly because the hardware cooperative received a $32.2 million refund of previously paid U.S. tariffs.
The results, released Wednesday, November 11, cover the 13 weeks ended October 3, 2026. Revenue rose by $53.3 million from $2.48 billion in the comparable quarter, while net income increased by $42.4 million from $99.7 million. Ace described both revenue and profit as third-quarter records, rather than records across every quarter of its business.
Sales at approximately 4,000 U.S. Ace stores that consistently report daily figures rose 2.0% on a same-store basis. The increase came from larger average purchases, not more visits: average ticket grew 4.5%, while the number of transactions fell 2.3%. Comparable digital sales advanced 12%, showing continued online growth alongside the store network.
A tariff refund accounts for a large part of the profit jump
The contrast between sales growth and reported earnings becomes clearer in Ace’s operating figures. Operating income increased to $114.1 million from $106.9 million a year earlier, or about 6.7%. The much larger increase in net income reflected items recorded below the operating line.
Ace said U.S. Customs and Border Protection refunded $32.2 million in duties previously paid under the International Emergency Economic Powers Act. The payment was included in other income rather than merchandise revenue. Other income, net, rose to $37.4 million from $6.9 million, accounting for most of the difference between the growth in operating income and the much larger increase in reported profit.
The refund was substantial relative to the $42.4 million year-over-year increase in net income. Simply subtracting $32.2 million from reported profit would not produce a company-reported adjusted earnings figure: tax effects and other items would also have to be considered. Ace did not disclose net income excluding the refund.
The comparison also reflects costs in the previous year. Ace’s third-quarter 2025 earnings release disclosed $17.8 million of nonrecurring asset impairment charges related to its international operations. That expense weighed on the earlier period, making the year-over-year comparison less straightforward than the headline percentage alone suggests.
Gross profit increased by $10.6 million to $456.4 million, while total operating expenses rose by $3.4 million to $342.3 million. Wholesale gross margin improved to 15.4% from 15.2%, although gross margin at the company-operated retail business slipped to 46.0% from 46.9%.
For the first nine months of 2026, Ace reported $367.8 million in net income, compared with $249.1 million a year earlier. The year-to-date figure also incorporates an $11.8 million tariff refund reported in the second quarter, so the influence of the refunds is not confined to the latest three months.
Larger purchases and new stores support the sales record
Most of Ace’s consolidated revenue comes from supplying merchandise to its network of independent retailers, rather than from sales booked directly at company-operated shops. Wholesale revenue increased 2.4% to $2.32 billion in the third quarter, while revenue from Ace Retail Group, the business that operates stores directly, edged down 0.2% to $212.6 million.
New stores provided a considerable lift to the wholesale business. Ace reported $48.5 million in additional merchandise revenue from domestic stores activated between January 2025 and September 2026. Canceled store memberships reduced revenue by $8.7 million, and wholesale merchandise revenue to comparable domestic stores fell $20.1 million. The different movements help explain why total wholesale sales grew even though comparable-store wholesale shipments declined.
Elsewhere in wholesale operations, Ace Wholesale Holdings reported a $16.4 million, or 10.8%, revenue increase, principally from hardware and professional lumber customers. International hardware operations added $5.2 million in wholesale revenue, while Ace Services Holdings recorded a $4.6 million decline. Ace identified outdoor power equipment, holiday décor, power tools, and fans and heaters among the stronger merchandise departments.
The 2.0% increase in U.S. retail same-store sales should not be confused with the performance of Ace Retail Group. The broader figure reflects the thousands of stores that consistently share daily sales data, many of them locally owned. Comparable sales at Ace Retail Group’s own stores declined 2.1%, even though the group’s store count rose to 267 from 263 a year earlier.
Nor does a higher average ticket necessarily establish that product prices alone drove the change. Customers can spend more per visit because of prices, the number of items purchased, or a shift toward higher-priced merchandise. What Ace’s disclosed figures establish is that higher spending per visit more than offset fewer transactions at the reporting U.S. stores.
Store expansion continues as inventories rise
Ace opened 46 domestic stores during the third quarter and canceled 22 memberships, for a net addition of 24 locations. Its U.S. store count reached 5,307 at quarter-end, up 87 from a year earlier. Earlier in September, the company said it had opened its 100th new U.S. store of 2026 and was targeting more than 170 openings for the full year.
Because Ace supplies merchandise to independent retailers, more stores can generate additional wholesale demand even when existing locations report uneven sales trends. Ace says its wider system serves more than 9,050 locally owned and operated stores worldwide, while the U.S. count represents a smaller group of domestic retail locations.
Ace also held more merchandise at quarter-end. Inventories totaled $1.40 billion at October 3, up $104.1 million from a year earlier. Ace attributed the increase to higher sales volumes, remodeling work at Ace Retail Group stores, and inventory for new locations. A larger inventory position ties up capital until products are sold, making cash generation an important companion measure to the earnings reported in the quarter.
Through the first nine months of 2026, net cash provided by operating activities reached $220.3 million, compared with $197.3 million in the same period of 2025. Long-term debt, including amounts due within a year, increased by $5.2 million year over year. At quarter-end, Ace listed $443.1 million outstanding on its revolving credit facility, $108.2 million on the retail group’s credit facility, and $50.3 million owed to former retailers.
Ace also accrued $153.6 million in patronage distributions to shareholders for the quarter, a 25.8% increase from $122.1 million a year earlier. As an accrual, that amount should not be confused with a cash payment made during the quarter. It is an additional measure of the cooperative’s results, distinct from the net-income figure that received the tariff-refund benefit.
More from Investing
Latest News
View all news- U.S. Crude Oil Rebounds Above $87 as Strait of Hormuz Supply Risks Persist
- USDA Awards $4 Million to Expand Conventional Crop-Breeding Research Across Five States
- Italy Forecasts 2027 Economic Growth of 0.6% as Inflation Slows Consumption
- UK Government-Backed Investors Join Fractile’s £500 Million-Plus AI Chip Round
- Dutch House Prices Rise 3.4%, but Regional Data Reveal Local Divides
