
U.S. Crude Oil Rebounds Above $87 as Strait of Hormuz Supply Risks Persist
Oil recovered from two-month lows as fresh tanker-security warnings kept Middle East supply disruptions in focus, even as some regional production resumed.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy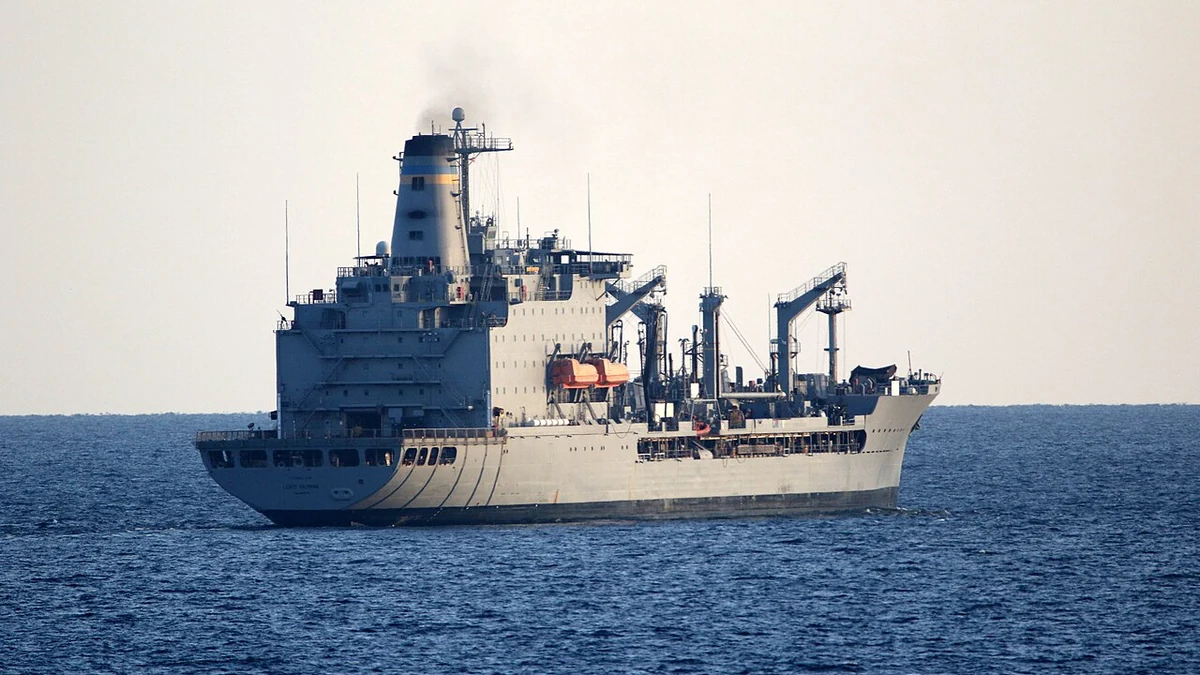
U.S. crude oil futures rose back above $87 a barrel in Wednesday trading, recovering from two-month lows as renewed concerns about shipping through the Strait of Hormuz complicated hopes for a quick easing of Middle East supply disruptions. The move followed a steep selloff in oil prices, leaving traders to weigh signs of recovering regional output against the continuing danger faced by vessels moving through the Persian Gulf.
West Texas Intermediate (WTI), the main U.S. crude benchmark, traded above the $87 level on November 11, according to Reuters market reporting. That was an intraday price, not a closing settlement. Brent crude also rose during the session. The rebound came after two days of losses as optimism about a possible reduction in U.S.-Iran hostilities had helped drive prices lower.
The recovery did not establish a new upward trend by itself. Oil remains sensitive to changes in diplomatic expectations, shipping conditions and the amount of crude reaching buyers. What has become harder for the market to dismiss is the gap between increased production capacity in the region and the practical ability to transport those barrels safely.
New tanker warnings keep the Strait of Hormuz in focus
Maritime security reports show why the route remains a concern. In its latest incident notices, the United Kingdom Maritime Trade Operations agency, or UKMTO, recorded a November 11 report involving a tanker in the Strait of Hormuz. It classified the event as suspicious activity and said the crew’s status, damage and environmental consequences were not yet known. The notice did not establish that the vessel had been hit or identify who was responsible.
A separate UKMTO report on November 10 described a tanker struck by an unknown projectile about 19 nautical miles northeast of Lima, Oman. The master reported that the crew was safe and no environmental impact had been observed, with a damage assessment planned. Earlier notices this month described other reported strikes and explosions near the shipping route, some involving vessels that remained underway and others requiring emergency action.
These warnings matter to the oil market even when the immediate damage to a particular ship is limited. Shipowners, charterers and insurers must consider the risk of a voyage before committing vessels to the route. The resulting changes in vessel availability, freight costs and transit arrangements can restrict how quickly crude gets to refineries, even where wells and export terminals are capable of producing more.
The Strait of Hormuz connects the Persian Gulf with the Gulf of Oman and is a critical outlet for oil exporters in the region. U.S. Energy Information Administration data show that about 20.9 million barrels a day of petroleum and other liquids passed through it during the first half of 2025. A disruption does not have to shut the strait completely to affect trade: slower movements, higher insurance premiums and limited alternative routes can all raise the cost of delivery.
More Middle East barrels are returning, but supply remains constrained
The broader supply picture is less one-sided than the latest security headlines might suggest. The EIA’s November Short-Term Energy Outlook, released on November 10, said exports from the Middle East increased slightly in October. The restart of Saudi Arabia’s East-West Pipeline helped shipments, while ship-to-ship transfers along Oman’s coast supported continued flows through the Hormuz area.
Production outages have also eased materially from their earlier peak. EIA estimated that Middle Eastern crude production shut-ins averaged 2.5 million barrels a day in October, compared with 10.9 million barrels a day at their peak in May. That change helps explain why crude prices can retreat even while incidents at sea continue: more oil is available than during the worst point of the disruption.
Availability at the wellhead, however, is not the same as uninterrupted delivery to customers. EIA expects oil flows from the Middle East to remain somewhat constrained through the rest of 2026, and it projected roughly unchanged regional shut-in volumes over that period. Tanker attacks have reduced shipping availability and pushed freight rates higher, creating another cost that can persist after production has restarted.
The agency also reported that global oil inventories fell by an estimated 1.2 million barrels a day during the third quarter. It expects inventories to begin rising in the fourth quarter as world production exceeds consumption, but cautioned that disruption risks and longer shipping routes could delay the effect of those additional supplies on near-term prices.
That distinction is important for interpreting Wednesday’s rebound. A market expecting larger stockpiles and restored regional production has a reason to sell oil after a period of high prices. At the same time, a fresh attack or credible warning can quickly force traders to reassess whether barrels already produced will reach their destination on schedule.
Diplomacy and inventories could determine the next move
Another source of volatility is the uncertain diplomatic outlook. Hopes for progress toward reducing the U.S.-Iran conflict helped push crude toward two-month lows earlier in the week. Those expectations faced a setback Wednesday after Iranian officials rejected the idea that enriched nuclear material would leave the country, according to Reuters reporting. Such statements do not establish whether negotiations will succeed or fail, but they can alter the market’s assessment of how long shipping risks may last.
There is a difference between a political breakthrough and a return to normal shipping. Even if tensions ease, vessel operators may need assurances about security before restoring regular routes. Insurers would also have to reassess coverage and premiums. That means the risk premium embedded in oil prices could decline more gradually than diplomatic headlines suggest.
For the U.S. market, inventory figures provide another test of the underlying balance. EIA said commercial crude stocks ended October at about 410 million barrels, the lowest end-of-October level since 2014. Market participants will be comparing subsequent official stock reports with signs of easing global supply shortages, particularly after private-industry estimates suggested a recent weekly build in U.S. crude inventories. Those private estimates are not a substitute for confirmed government data.
In its latest forecast, EIA expects Brent spot crude to average around $100 a barrel in November and December, reflecting continuing supply constraints. That projection refers to the agency’s monthly average spot-price outlook, not the level of Brent futures at any particular moment during Wednesday’s trading. The agency sees conditions improving further into 2027 as regional production recovers and inventories rebuild, but its forecast was finalized before the most recent tanker warning.
For now, the $87 move in WTI is best read as a recovery within a volatile market rather than proof that the pressure on oil prices has been resolved. The immediate questions are whether more vessels can move through the Strait of Hormuz without incident, how quickly oil shipments normalize and whether incoming U.S. inventory data support expectations of a looser supply balance.
More News
Latest News
View all news- U.S. Dollar Strengthens as Inflation Data Lift Expectations for Another Fed Rate Increase
- Silver Rebounds Above $52 as U.S. Rate-Hike Fears Keep Precious Metals Volatile
- Gold Futures Recover Above $4,050 After Inflation-Driven Selloff
- Ace Hardware Reports Record $2.5 Billion Third-Quarter Revenue as Net Income Jumps 42.5%
- UK Government-Backed Investors Join Fractile’s £500 Million-Plus AI Chip Round
