
Australian Home Lending Records Its Largest Quarterly Fall as Investor Borrowing Plunges
Investor home-loan values sank 32.3% in the September quarter, driving a record drop in Australian housing finance as owner-occupier borrowing also weakened.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy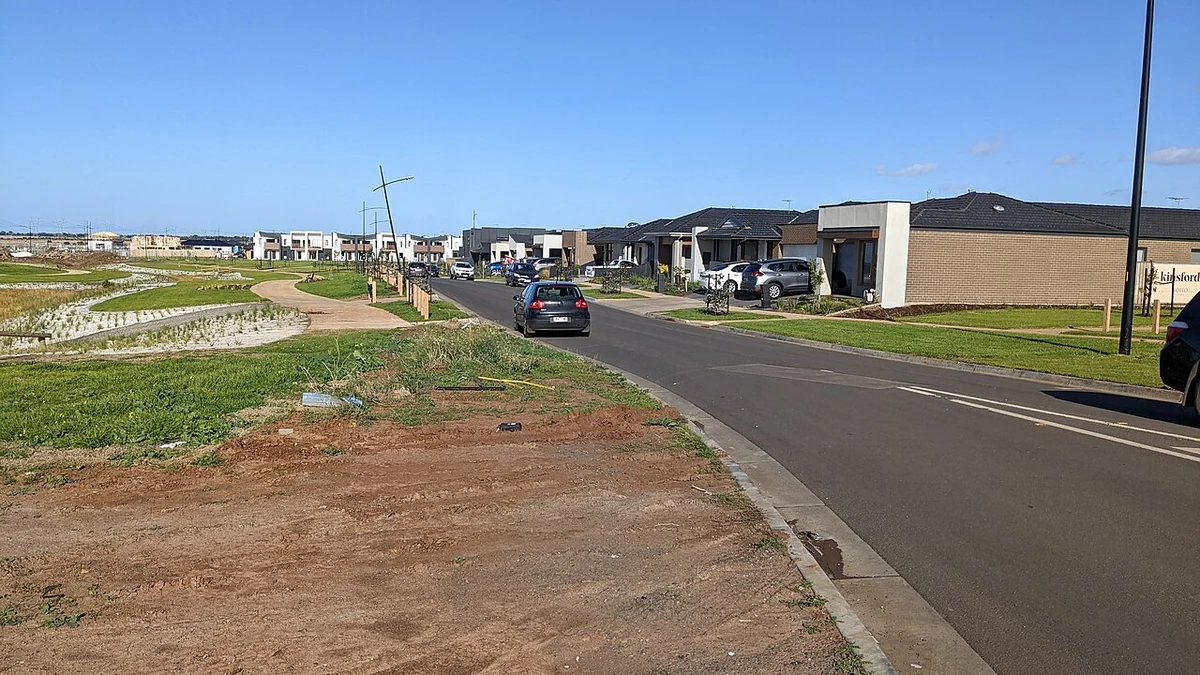
Australian home lending recorded its largest quarterly decline by value in the September quarter, with a retreat by property investors accounting for much of the drop. The value of new housing loan commitments fell 15.5% to A$81.16 billion, the steepest quarterly fall since the Australian Bureau of Statistics (ABS) series began in 2002.
Lenders recorded 111,878 new home-loan commitments, 15.0% fewer than in the previous quarter. Those totals are seasonally adjusted. Compared with a year earlier, the number of commitments was down 21.4% and their value was 18.1% lower, a reminder that the pullback had been under way for some time. These figures track newly accepted loans, not the mortgage debt already held by Australian households.
In its November 11 release, the ABS separated borrowing for investment properties from loans taken out by people buying homes to live in. Activity weakened in both categories, but the fall among investors was several times larger. That difference explains much of the unusually severe national result.
Investor borrowing drives the record decline
New loans to property investors fell 30.6% in number to 35,301 during the quarter. Their total value dropped an even larger 32.3% to A$24.71 billion. Both were record quarterly declines for their respective investor series, with the latest falls marking a third consecutive quarter of contraction in investor borrowing by both measures.
Investor borrowing fell sharply across every Australian state and territory, according to the ABS. It was not a downturn confined to one large city. Compared with the September quarter a year earlier, investor loan numbers were 38.5% lower and their combined value was down 38.1%.
In the December quarter of 2025, the annual growth rate in new investor-loan numbers was still positive at 24.9%. Nine months later, the same annual measure had turned sharply negative. Such a rapid reversal says much about the flow of new investor finance, although it cannot establish on its own how far home prices have moved or might move.
At A$24.71 billion, investment finance still accounted for roughly 30% of all new housing-lending value during the quarter. Its steep contraction consequently had a large effect on the national total, despite a smaller fall in owner-occupier borrowing. With investor loan counts dropping almost as fast as the money committed, the change points to far fewer new loans rather than simply smaller mortgages.
Mish Tan, the ABS head of finance statistics, said borrowing costs were not the only possible influence on investors. The agency also identified potential effects from tax changes and expectations of lower home prices. Those are explanations consistent with the data, rather than a measured breakdown of precisely how much of the record decline came from each factor.
Owner-occupiers and first-home buyers also pull back
Borrowing for owner-occupied homes was more resilient than investment lending, but it was still falling. The number of new owner-occupier commitments declined 5.3% to 76,578, following a 4.0% fall in the previous quarter. Their value also fell 5.3%, to A$56.5 billion, showing that the weakness was not limited to investors.
Queensland registered a 10.4% fall in new owner-occupier loan numbers, against declines of 6.6% in Victoria and 4.1% in New South Wales. Those differences show that the slowdown has not been uniform across major markets. Nationally, owner-occupier commitments were down 9.8% by number and 4.6% by value compared with a year earlier.
First-home buyers were among those reducing new borrowing. Their owner-occupier loan numbers fell 8.6% to 26,415 in the September quarter, after a 4.4% decline in June. The value of loans to this group decreased 8.0% to A$16.2 billion, while the number of commitments was 12.3% lower than a year earlier.
Even after those falls, first-home buyers accounted for more than one-third of all owner-occupier commitments. That share provides a useful qualification: the figures point to fewer first-home purchases being financed, but not to first-home buyers disappearing from the market or losing all their relative presence among people purchasing a principal residence.
The scope of the ABS figures also matters. They count new borrower-accepted commitments for purchasing existing or new dwellings and for building homes, but exclude refinancing from the main dwelling-loan totals. A decrease in new finance is not a corresponding reduction in outstanding mortgage debt, nor is it a direct measure of falling property prices.
Higher interest rates and tax reforms weigh on demand
Borrowing costs had already risen markedly when the September quarter ended. The Reserve Bank of Australia (RBA) cash-rate target had climbed from 3.60% at the start of the year to 4.60% by late September. A further increase took it to 4.85% effective November 4, after the period covered by the latest lending figures. Higher rates increase mortgage servicing costs and can constrain the amount prospective buyers can borrow.
In its November assessment of financial conditions, the RBA said housing lending had weakened sharply, particularly for investment properties. The bank found the reduction in investor finance had been concentrated in purchases of established dwellings, a pattern consistent with both tighter monetary policy and changes to the tax treatment of property investment. It also noted that home prices had declined more than it previously expected.
Property-tax reforms announced in the May federal budget also changed the prospective economics of investing in established homes. From July 1, 2027, those who acquired such properties after the May 12 budget announcement will generally no longer be able to deduct associated rental losses against non-property income such as wages. Eligible losses can still offset income from residential properties or be carried forward. Properties held before the budget announcement remain exempt from the change.
Eligible new-build investment properties remain treated differently, reflecting the government’s aim of encouraging additional housing supply rather than investor purchases of existing homes. The capital-gains-tax overhaul also replaces the current 50% discount for affected gains with an inflation-adjusted approach and a minimum 30% tax rate, with provisions allowing eligible new builds to retain a choice of treatments. The rules change potential after-tax returns, but the ABS lending figures cannot isolate the effect of tax policy from borrowing costs or expectations about house prices.
Outstanding housing credit is following a different path from new finance. The RBA reported housing credit growth of 6.3% on a six-month-ended annualised basis in its November review, even though that pace had slowed with investor borrowing. Existing mortgages remain on lenders’ books for years, so a sudden reduction in new commitments can coexist with a growing total stock of housing loans.
Further moderation in housing-credit growth is expected by the RBA as earlier declines in property prices and turnover feed through to settlements. The ABS has scheduled its next quarterly lending release for February 10, 2027. The December-quarter figures will provide an initial reading covering the period after the November rate increase, which was not reflected in these September-quarter numbers.
More from Banking
Latest News
View all news- USDA Awards $4 Million to Expand Conventional Crop-Breeding Research Across Five States
- Silver Rebounds Above $52 as U.S. Rate-Hike Fears Keep Precious Metals Volatile
- Gold Futures Recover Above $4,050 After Inflation-Driven Selloff
- Italy Forecasts 2027 Economic Growth of 0.6% as Inflation Slows Consumption
- Ace Hardware Reports Record $2.5 Billion Third-Quarter Revenue as Net Income Jumps 42.5%
