Bank of Japan Raises Policy Rate to 1.25%, Highest in 31 Years
The BOJ lifted its overnight call-rate target by 25 basis points, extending its exit from ultra-low rates even as August core inflation remained below 2%.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy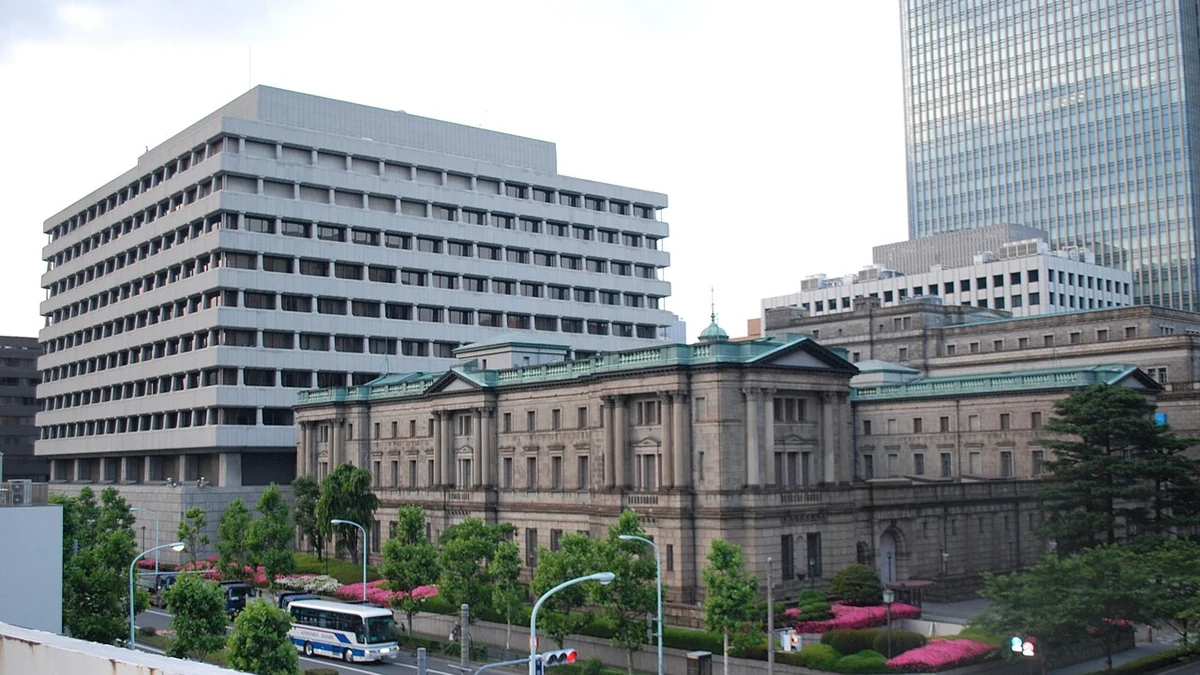
The Bank of Japan raised its short-term policy rate by 25 basis points to around 1.25% on Friday, taking its main rate setting to its highest level in roughly 31 years and extending a gradual retreat from the ultra-low-rate policies that defined Japanese monetary policy for decades.
The increase followed the BOJ’s June move to 1.0% and was approved by a 7-2 vote at the end of a two-day Monetary Policy Meeting. The new operating guideline calls for the uncollateralized overnight call rate to remain around 1.25%. The BOJ also raised the interest rate applied to its complementary deposit facility to 1.25% and the basic loan rate to 1.5%, with the new settings effective September 24.
The central bank’s 2026 monetary-policy release index lists the September 18 change in its guideline for money market operations, alongside the related reference material and changes to the complementary deposit facility. The decision adds another step to a tightening path that has moved Japanese short-term rates sharply higher from the levels in place only a few years ago.
A quarter-point move pushes rates back toward 1995 levels
The historical comparison is unusually stark. BOJ monthly market data show the uncollateralized overnight call rate at 1.27% at the end of June 1995 and 0.84% at the end of July 1995. The new 1.25% policy guideline therefore returns the short-rate setting to territory Japan has not occupied since around the middle of 1995. The historical series records realized market rates rather than today’s policy guideline, so the measures are not perfectly identical, but the data still show why the 31-year comparison is meaningful.
Japan’s policy framework looked very different as recently as March 2024. At that meeting, the BOJ ended its negative interest rate policy and adopted an overnight call-rate guideline of around 0% to 0.1%, saying its earlier framework of quantitative and qualitative easing with yield curve control and negative rates had fulfilled its role. By December 2025, the overnight rate guideline had reached 0.75%. The June 2026 meeting lifted it again to 1.0%, before Friday’s latest quarter-point increase.
The BOJ’s June policy statement said financial conditions remained accommodative even after the move to 1.0%, noting that real interest rates were negative mainly in the short- to medium-term zone. Raising the nominal policy rate to 1.25% tightens those conditions further, but it does not by itself establish that Japanese monetary policy has become restrictive. That judgment depends on inflation, inflation expectations, growth and the level of real rates, all of which the BOJ continues to assess.
Inflation has eased below 2%, but the BOJ is looking beyond one month
The rate increase came on the same day Japan released fresh inflation data. The Statistics Bureau of Japan said the national consumer price index rose 1.9% from a year earlier in August. The index excluding fresh food, the measure commonly used as Japan’s core CPI, rose 1.7%, while the index excluding both fresh food and energy increased 1.9%. The figures are reported under the new 2025-base CPI series introduced in August.
Those readings are below the BOJ’s 2% price-stability target, but the central bank has been emphasizing the path of underlying inflation rather than treating one monthly CPI release as decisive. In its July outlook, the BOJ said headline inflation was likely to move clearly above 2% from the second half of fiscal 2026 before easing back toward around 2% through fiscal 2028. It pointed to higher crude oil prices, semiconductor and other price pressures tied to stronger AI-related demand, and the depreciation of the yen as important influences.
The same outlook expected underlying CPI inflation, which strips out temporary fluctuations more broadly than the standard core measure, to increase gradually toward a level consistent with the 2% target. BOJ officials have also highlighted the interaction between wages, selling prices and medium- to long-term inflation expectations. That forward-looking framework helps explain why a sub-2% August core reading did not prevent another increase in the policy rate.
Growth risks remain part of the calculation. The BOJ’s July assessment said Japan’s economy was likely to continue growing moderately, though at a slower pace, with higher crude oil prices weighing on activity. Government measures and strong global AI-related demand were expected to provide support. The central bank has repeatedly identified the Middle East situation, AI demand and foreign exchange developments as factors that could alter both growth and the inflation outlook.
The next policy test comes in late October
For households and businesses, a 1.25% policy rate changes the financial backdrop more than the number alone suggests. Japanese banks have operated for years in an environment of exceptionally low short-term rates. Higher administered and market rates can support returns on deposits and other short-duration savings products, while also feeding into funding costs and borrowing rates as contracts reset. The timing and size of those pass-through effects vary across products and institutions.
For investors, the decision also reinforces that Japan is following a different monetary path from the one that prevailed through most of the past two decades. The BOJ has not committed to a fixed schedule of further increases. Its recent policy language has tied future adjustments to economic activity, prices and financial conditions, leaving the pace of normalization dependent on incoming data rather than on a preset rate path.
The next scheduled BOJ Monetary Policy Meeting is October 29 and 30. Before then, the Statistics Bureau is due to release September national CPI data on October 23, giving policymakers another full inflation reading before they meet. With the overnight rate guideline now at 1.25%, that late-October meeting will provide the next formal test of whether the central bank sees enough persistence in wages and underlying inflation to keep reducing monetary accommodation, or whether it prefers to hold the new 31-year-high setting for longer.
More News
Latest News
View all news- Google, Constellation Sign 3.59-GW PJM Power Deal, With $4.3 Billion-Plus Going to Nuclear Uprates
- RPM Posts Record $2.22 Billion Fiscal Q1 Sales, Narrows FY2027 Outlook
- Type One Energy Raises $200 Million Series B to Advance Tennessee Fusion Project
- MIAX Hits Record 17.1% YTD U.S. Options Share as ADV Rises 22%
- Japan’s 10-Year Government Bond Auction Clears Near 3.10% With a 3.1% Coupon