
Berkshire Puts More Cash to Work With $4.5 Billion Buyback and Heavy Stock Buying
Berkshire ended a 14-quarter run as a net stock seller as Greg Abel accelerated share repurchases and deployed more of the company's cash pile.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy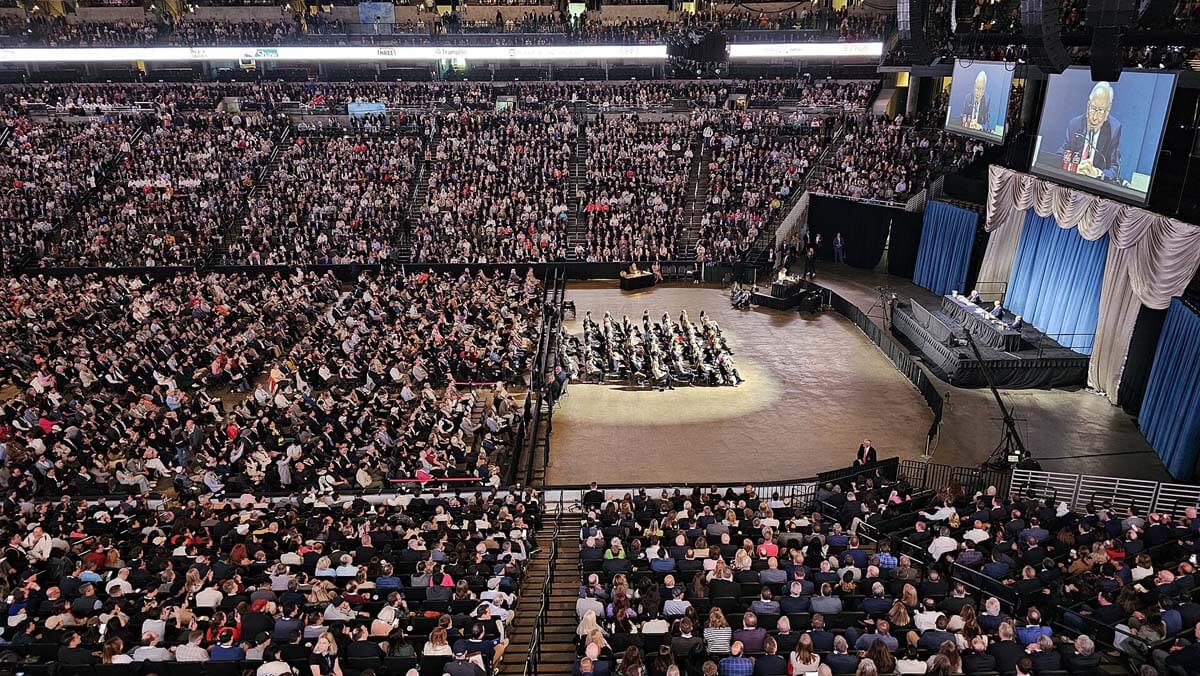
Berkshire Hathaway stepped up its use of cash in the second quarter, buying $23.5 billion of stocks, repurchasing $4.5 billion of its own shares and ending a 14-quarter stretch in which it had been a net seller of equities. The change came during Greg Abel’s second quarter as chief executive and alongside stronger operating results across several of the conglomerate’s businesses.
Operating earnings rose 16% from a year earlier to $12.98 billion, while revenue increased 10% to $101.81 billion. Berkshire’s cash, cash equivalents and U.S. Treasury bill holdings fell to $364.7 billion at June 30 from a record $380.2 billion three months earlier. The company still holds one of the world’s largest corporate cash reserves, but the decline is notable after years in which its liquidity kept expanding as Warren Buffett found relatively few opportunities large enough and attractive enough to materially affect Berkshire’s results.
The company bought nearly $20 billion more publicly traded stocks than it sold during the quarter. Those purchases included another $10 billion invested in Alphabet, Google’s parent company, taking the position into the ranks of Berkshire’s largest equity holdings. Total purchases of other stocks reached $23.5 billion.
Berkshire also spent $4.5 billion repurchasing its Class A and Class B shares between April and June, a sharp acceleration from the relatively small amount bought in the first quarter and from 2025, when no shares were repurchased at all. The activity continued after the quarter ended, with more than $3.3 billion of additional buybacks in July.
Taken together, the equity purchases, repurchases and recent acquisitions show Berkshire using cash at a faster pace than during Buffett’s final stretch as chief executive. One quarter is not enough to establish that Abel has adopted a fundamentally different investment philosophy, especially because Buffett remains chairman and continues to participate in major decisions, but the change in the flow of capital is already visible in the numbers.
The buyback sends a valuation signal
Berkshire’s repurchase program carries more information than a conventional corporate buyback because management is not working from a fixed authorization that requires a certain amount of stock to be purchased over a set period. The company’s policy permits repurchases only when the chief executive, after consulting with the chairman, believes Berkshire’s shares are trading below a conservatively determined estimate of intrinsic value. There is no specified maximum amount, although Berkshire will not buy stock if doing so would reduce cash, cash equivalents and Treasury bills below $30 billion.
That policy was amended ahead of the leadership transition so that responsibility for the valuation decision would pass from Buffett to Abel. Berkshire’s annual report says major investment and capital-allocation decisions are now Abel’s responsibility, with Buffett remaining chairman.
The $4.5 billion second-quarter buyback therefore indicates more than a decision to reduce the share count. Under Berkshire’s own rules, it means Abel, after consultation with Buffett, concluded that the stock was available at prices below a conservative estimate of intrinsic value.
Berkshire had gone nearly two years without making substantial repurchases before disclosing in March that it had resumed buying its own shares. An SEC filing showed that repurchases restarted on March 4, although only modest purchases were completed before the first quarter ended. The much larger amount spent from April through June marks the first major use of the program under Abel.
The scale is also notable by Berkshire’s recent standards. Reuters reported that the current pace is comparable with some of the more aggressive repurchase periods under Buffett. Berkshire’s biggest full year for buybacks was 2021, when it spent about $27 billion purchasing its own shares. Including July, the company repurchased more than $7.8 billion from the beginning of April through the end of that month.
The renewed buying followed a period in which Berkshire shares had lagged the broader market after Buffett’s succession announcement. Through the end of last week, Berkshire’s Class A stock was up about 3% for 2026, compared with roughly 13% for the S&P 500. Since Buffett announced in May 2025 that he would step down as chief executive, Berkshire had trailed the index by about 40 percentage points through Friday.
Investors responded positively on Monday. Class A shares rose as much as 3.3% to $806,102.81, while Class B shares climbed as much as 3.1% to $537.74. Both reached their highest levels since May 2, 2025, the day before Buffett announced that Abel would succeed him.
Public-stock buying also accelerated sharply
The buybacks were only one part of Berkshire’s shift in the quarter. For more than three years, the company had sold more publicly traded equities than it purchased, a pattern that helped push its cash holdings progressively higher. The second quarter broke that run, with $23.5 billion of stock purchases and nearly $20 billion more equities bought than sold.
Alphabet accounted for a large portion of the increase. Berkshire added $10 billion to its investment in the Google and YouTube parent, moving the holding into the upper tier of its stock portfolio.
The investment is notable because Berkshire has historically been selective about large technology companies. Apple became its biggest equity holding under Buffett, although Buffett frequently described Apple in terms of the strength of its consumer franchise rather than simply as a technology company. Alphabet adds another large technology platform to a portfolio long associated with businesses such as Apple, American Express, Coca-Cola and major financial and energy companies.
The second-quarter activity should not automatically be attributed to Abel alone. Buffett remains chairman, and Reuters reported that he said last month that he was still involved in Berkshire’s decision-making and that neither he nor Abel was taking major actions without the other’s approval. What can be said from the filings is that Berkshire was putting money to work much more aggressively than it had been.
The activity also extends beyond publicly traded stocks. Berkshire completed its acquisition of Taylor Morrison on July 24, paying $72.50 a share in cash. The purchase valued the homebuilder’s equity at approximately $6.8 billion and the business at about $8.5 billion including debt and other enterprise-value adjustments. Taylor Morrison is being combined with Berkshire’s existing site-built homebuilding operations.
July therefore included at least $3.3 billion of additional share repurchases and $6.8 billion for Taylor Morrison, more than $10 billion across those two uses of cash alone. The homebuilder acquisition followed Berkshire’s roughly $9.5 billion purchase of Occidental Petroleum’s OxyChem business in January.
Even deals of that size make only a modest dent in a cash reserve of $364.7 billion. Berkshire’s scale has long created a difficult investment problem because small acquisitions cannot materially improve overall returns. To make a meaningful difference, the company needs very large acquisitions, sustained purchases of public equities, major buybacks or some combination of those approaches. The second quarter was unusual because Berkshire was pursuing several of them at once.
Operating businesses gave Berkshire more room to spend
The increase in investing activity arrived alongside stronger results from the operating businesses, so the decline in cash was not simply the result of spending down accumulated liquidity. Second-quarter operating earnings rose to $12.98 billion from $11.16 billion a year earlier. Berkshire emphasizes that measure because GAAP net income can move sharply from one quarter to the next as the market value of its large stock portfolio changes.
Net income more than doubled to $25.67 billion from $12.37 billion, but the figure included investment gains and losses on securities the company continued to own. Berkshire has repeatedly cautioned shareholders against using those short-term market movements as a measure of underlying operating performance.
BNSF reported a 6% increase in profit to $1.56 billion, helped by higher shipments of consumer, agricultural and energy products as well as fuel-related revenue. Berkshire Hathaway Energy posted a 27% increase in profit to $891 million, supported by stronger utility margins and tax credits. Service businesses including private-aircraft operator NetJets and electronic-components distributor TTI also contributed to the improvement.
Not every major operation strengthened. Geico’s pre-tax underwriting profit fell 45% as accident claims increased and the auto insurer spent more on advertising. Berkshire has been working to rebuild Geico’s customer base after several years of emphasizing underwriting discipline and cost reductions, and overall insurance and reinsurance profit declined 11% in the quarter.
The company also warned that some consumer-facing businesses were seeing weaker demand. Its auto dealerships, Fruit of the Loom and recreational-vehicle maker Forest River were among the operations where changes in consumer confidence were affecting sales. Berkshire also cited continued uncertainty around tariffs, wars and other macroeconomic and geopolitical developments.
Those pressures help explain why the size of the cash reserve still matters even as the company spends more aggressively. Holding $364.7 billion of cash and Treasury bills gives Berkshire substantial capacity to absorb insurance losses, finance existing operations and move quickly if a very large opportunity appears.
The more significant change is that the cash balance is no longer simply accumulating while Berkshire waits. Abel inherited a company whose ability to generate money had increasingly outpaced its ability to reinvest it. During the second quarter, Berkshire simultaneously bought public stocks, repurchased its own shares and moved toward completing a multibillion-dollar acquisition while its operating businesses generated higher profits.
It is still too early to call this a durable change in Berkshire’s long-term behavior. The buyback policy remains explicitly dependent on valuation, and management is under no obligation to continue repurchasing shares if Abel and Buffett decide the stock is no longer attractive. The buying that continued into July, however, makes the second-quarter shift harder to dismiss as a one-off adjustment.
For a company that still holds more than $360 billion in cash and Treasury bills, the central question is not whether Berkshire can find occasional investments. The early Abel period is beginning to show how much money the company is prepared to commit when management believes both the price and the opportunity are sufficiently attractive.
Sources
Reuters: Berkshire Q2 results, cash holdings, investments, buybacks and operating-company performance.
More from Investing
Latest News
View all news- United Community Banks Sells $2.6 Billion of Securities, Expects $300 Million Pretax Hit
- John Marshall Bancorp and Eagle Financial Services Announce $253 Million All-Stock Merger
- GameStop Posts Record Q2 Operating Income as Collectibles Reach 45% of Sales
- U.S. Treasury Sanctions 36 Iran Aviation Targets and Issues Alert to Financial Institutions
- Group 1 Automotive Launches $1.25 Billion Senior Notes Offering to Help Fund Hennessy Acquisition
