Brightline Florida Reaches Restructuring Deal With $490 Million in New Financing
The package combines $140 million of additional senior debt with $350 million of new junior debt, while the train operator remains outside Chapter 11.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy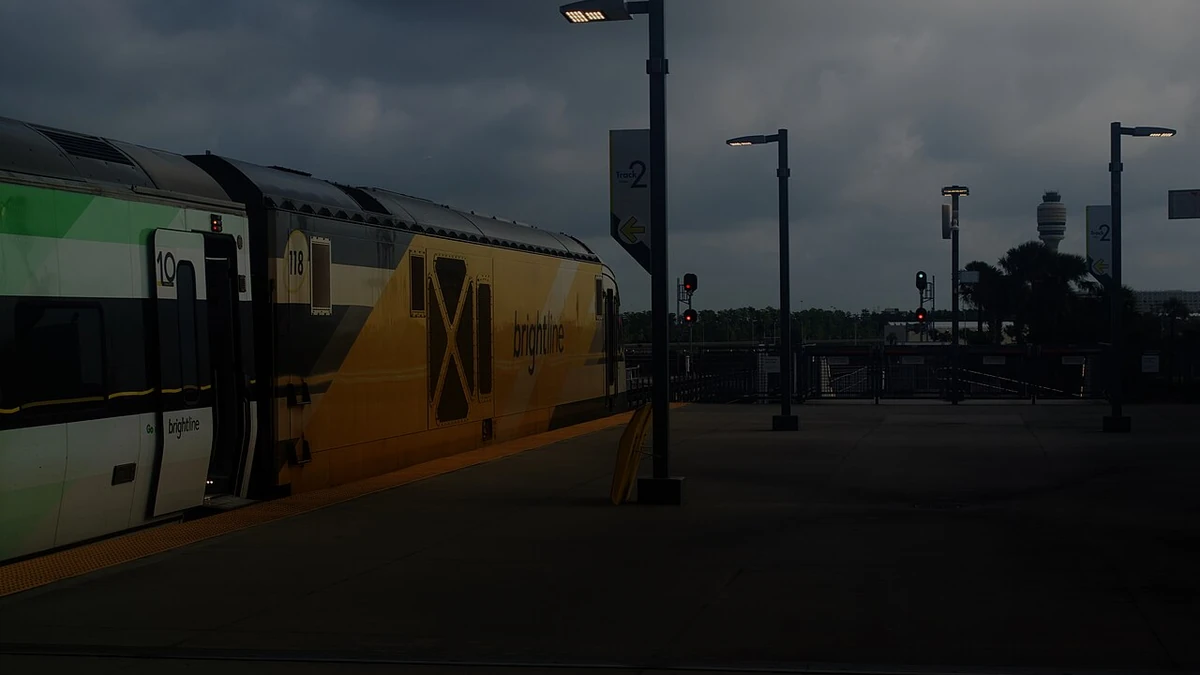
Brightline Florida has reached a restructuring support agreement with financial stakeholders that includes commitments for $490 million of new long-term financing for its Miami-to-Orlando passenger rail business, while certain parent entities move through a prearranged Chapter 11 process.
The financing is intended to strengthen liquidity and reduce debt at the broader Brightline Florida structure without putting the train operating company itself into bankruptcy. Supporting stakeholders include Assured Guaranty Inc. and an ad hoc group of mutual fund bondholders. The $490 million package is divided between $140 million of additional senior debt and $350 million of new junior debt for Brightline Trains Florida LLC.
Brightline said in its company press room that its Miami-to-Orlando service is not affected by the restructuring. Brightline Trains Florida LLC, which operates the service, will remain outside Chapter 11 and continue operating under its existing management team.
The $490 million package adds senior and junior debt
The restructuring agreement sets out how creditors plan to finance Brightline through and beyond the court process. The $140 million of additional senior debt will sit alongside the operating company’s existing senior debt, while the $350 million junior portion will rank below that senior layer. Assured Guaranty, which insures a large portion of Brightline’s senior tax-exempt bonds, is among the stakeholders supporting the restructuring.
The long-term financing should be distinguished from separate liquidity available while the affected parent entities are in Chapter 11. Assured Guaranty said participating stakeholders have agreed to provide Brightline Trains Florida LLC with $258 million of post-petition funding during the bankruptcy process. The interim funding is intended to support operations during the court case and is expected to be repaid when the affected Brightline entities exit bankruptcy.
That distinction matters because the two figures serve different purposes. The $258 million is court-period liquidity, while the $490 million is the new long-term financing package contemplated for the operating company under the restructuring. Treating the two amounts as one permanent capital raise would overstate the long-term financing described in the agreement.
Several large bond issues are also expected to remain outstanding. Brightline said the $2.2 billion Brightline Trains Florida LLC Series 2024 tax-exempt bonds and Assured Guaranty’s related bond insurance policy will stay in place. It also said other identified Brightline Florida and AAF Operations Holdings tax-exempt bonds will remain outstanding without reductions in their aggregate principal amounts.
That means Brightline’s statement that the restructuring will significantly reduce debt does not imply a write-down of every bond issue in the capital structure. The precise post-restructuring balance sheet will depend on the treatment of obligations at the parent entities, the court-approved plan and completion of the new financing.
The operating railroad stays outside the Chapter 11 cases
The legal structure is central to understanding what the filing means for passengers. Brightline Trains Florida LLC is not entering Chapter 11. Brightline Florida Holdings LLC, which indirectly holds rights tied to planned commuter service in Miami-Dade, Broward and Palm Beach counties, is also outside the filing group. AAF Operations Holdings LLC, which indirectly holds development rights connected with a proposed Tampa extension, likewise is not part of the Chapter 11 process.
Certain non-operating parent entities are using prearranged Chapter 11 cases to implement the restructuring. Brightline has said the process is designed to reorganize debt at those entities while preserving normal service and keeping the operating railroad funded. The court still must approve key elements of the restructuring and financing associated with the bankruptcy cases.
The separation between the operating railroad and the filing entities is intended to keep day-to-day train service insulated from the parent-level balance-sheet process. It also helps explain why existing senior operating-company bonds can remain in place even as Brightline seeks broader debt relief higher in the corporate structure.
Assured Guaranty’s exposure provides additional context for the negotiations. In its second-quarter regulatory filing, the insurer identified Brightline Trains Florida LLC as a below-investment-grade exposure and said Brightline’s revenues and ridership had grown but lagged initial projections. The filing also showed that Assured Guaranty continued to insure a substantial portion of Brightline’s senior revenue bonds.
Growth in ridership has not removed the financing pressure
Brightline is entering the restructuring while reporting higher passenger volumes and revenue. Through August, the company said 2026 year-to-date ridership increased 14% from the same period in 2025 and revenue rose 17%. Management is using that operating growth to support the case that the rail service has momentum even though its capital structure needs to be reset.
Higher ridership alone does not resolve the debt burden. The rail system was financed with large tax-exempt bond issues and other borrowings, leaving cash generation, debt service and liquidity closely linked to passenger growth. Assured Guaranty’s filing said Brightline’s credit performance depends on ridership, fare revenue and available liquidity, making the new financing commitments central to the restructuring plan.
Brightline also continues to point to development plans beyond its existing Miami-to-Orlando route, including a planned Cocoa station, commuter-access projects in South Florida and a proposed extension toward Tampa. Those projects remain development objectives rather than outcomes guaranteed by the restructuring, and future capital needs could depend on how the reorganized balance sheet performs.
The immediate next steps are legal and financial rather than operational. The bankruptcy court must consider the prearranged cases and related financing arrangements, and the parties must complete the conditions required for the restructuring to take effect. For passengers, the narrower point is that Brightline Trains Florida LLC remains outside Chapter 11 and service is continuing while the parent-level debt structure is reorganized.
More from Investing
Latest News
View all news- German Export Expectations Fall as Auto Industry Turns Negative Again
- Nasdaq Begins Trading Three New Portfolio Building Block ETFs
- Addex Regains Global GABAB Drug Portfolio Rights From Indivior
- Bank of England Market Minutes Show Rate-Hike Expectations in UK Curve
- Japan’s 3-Month Bill Auction Clears at 1.2555% Average Yield