
Chevron Posts $9.9 Billion Quarterly Profit as U.S. Refinery Throughput Hits Record
U.S. downstream earnings climbed to $3.6 billion as stronger refining margins lifted profits despite little change in refined-product sales.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy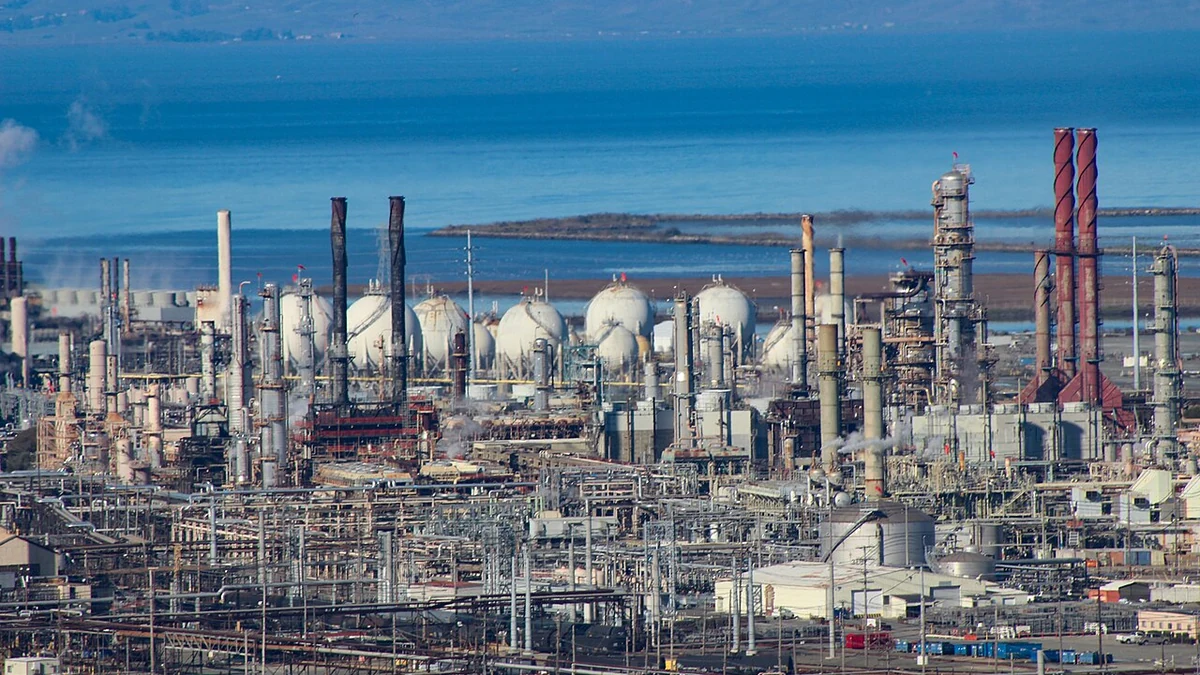
Chevron reported $9.924 billion in third-quarter profit on October 30, 2026, nearly three times its earnings a year earlier, as stronger refining margins and higher crude oil prices lifted results. The company also recorded its highest U.S. refinery crude throughput, processing 1.093 million barrels a day with crude units running at nearly 98% of capacity.
The year-over-year increase was substantial, but the sequential comparison was less favorable. Net earnings rose from $3.539 billion in the third quarter of 2025, yet declined from $12.072 billion in the second quarter of 2026. Reported earnings per diluted share were $5.06, compared with $1.82 a year earlier and $6.11 in the preceding quarter.
Chevron’s third-quarter earnings release put adjusted profit at $10.361 billion, or $5.28 a diluted share, up from $3.627 billion, or $1.85 a share, in the year-earlier period. Adjusted earnings exclude specified nonoperating items and foreign currency effects; they are not the same as the $9.924 billion reported under the company’s regular earnings measure.
Higher refining margins turn steady fuel sales into much larger profits
The U.S. downstream business, which includes refining and fuel marketing, earned $3.585 billion, compared with $638 million a year earlier. Chevron attributed the increase primarily to higher margins on refined-product sales. That earnings jump was far larger than the change in volumes, showing how much the price environment mattered to the quarter.
U.S. refinery crude inputs averaged 1.093 million barrels a day, up from 1.064 million in the third quarter of 2025 and 1.070 million in the second quarter of this year. The roughly 3% annual increase established a new company record. Nearly 98% utilization indicates that crude-processing units were operating close to their stated capacity, although it does not mean every part of a refinery ran without interruption.
Refined-product sales tell a different volume story. Chevron sold an average of 1.304 million barrels a day of refined products in the United States, almost unchanged from 1.303 million a year earlier. Crude throughput and marketed fuel sales measure different activities, so the two figures should not be treated as interchangeable. Still, the near-flat sales number reinforces Chevron’s explanation that margins, rather than a surge in fuel sales, drove the improvement in domestic downstream earnings.
The rebound extended beyond the United States. International downstream profit increased to $1.346 billion from $499 million, bringing worldwide downstream earnings to $4.931 billion versus $1.137 billion in the prior-year quarter. International refineries processed about 665,000 barrels a day, little changed from 663,000 a year earlier. Refined-product sales outside the United States fell 9% to 1.388 million barrels a day, a decline Chevron linked to supply disruptions from the Middle East conflict. Stronger product margins nonetheless lifted earnings in that business.
Oil prices support upstream earnings despite lower worldwide production
Chevron’s oil and gas production businesses also contributed more profit. Worldwide upstream earnings were $5.698 billion, up from $3.302 billion a year earlier, although below the second quarter’s $8.182 billion. U.S. upstream profit increased to $3.293 billion from $1.282 billion. International upstream earnings rose to $2.405 billion from $2.020 billion.
Higher prices help explain that result. Chevron reported an average realized price of $62.72 a barrel for U.S. liquids, compared with $48.12 in the third quarter of 2025. The average international liquids realization rose to $86.09 from $63.16. Its earnings release listed average Brent crude at $97 a barrel for the quarter, versus $69 a year earlier. Those higher realizations supported earnings even though production did not rise across the entire portfolio.
Worldwide net oil-equivalent production averaged 3.980 million barrels a day, down from 4.086 million a year earlier and 4.070 million in the second quarter. Chevron said higher prices reduced its production entitlements in some operations, while the Middle East conflict also affected volumes. Record output at operated assets in Australia, increased production in the Gulf of America and an accounting change affecting Venezuela partly offset those pressures.
U.S. production was comparatively steady at 2.043 million barrels of oil equivalent a day, against 2.040 million in the prior-year quarter. It was the fifth consecutive quarter above 2 million, according to Chevron. Production increases associated with the Ballymore, Whale and Anchor projects in the Gulf of America were partly offset by a decline in the Bakken. International production slipped to 1.937 million barrels of oil equivalent a day from 2.046 million.
Not every change in reported profit reflects a change in the physical amount of oil produced or fuel refined. Chevron disclosed unfavorable earnings timing effects of $1.58 billion for the third quarter, compared with a favorable $1.54 billion in the second quarter. Its definition covers, among other things, the timing of derivative gains or losses before physical delivery and certain inventory-accounting effects. The swing makes the quarter-to-quarter earnings comparison more complicated than the headline profit figures alone suggest.
Cash flow strengthens as Chevron reduces debt and outlines new investment
Operating cash flow reached $16.0 billion, up from $9.4 billion a year earlier, although it was below the $22.6 billion recorded in the second quarter. Free cash flow rose to $12.0 billion from $4.9 billion in the third quarter of 2025. Chevron’s adjusted free cash flow was $14.2 billion, compared with $7.0 billion a year earlier. The adjusted measure benefited from a $1 billion loan repayment by its Tengizchevroil affiliate and asset-sale proceeds, items investors should distinguish from routine operating receipts.
Capital spending came to $4.0 billion, down from $4.4 billion in the year-earlier quarter, largely because of lower expenditures in the Permian Basin. Chevron said it reduced total debt by another $3.5 billion during the quarter and lowered net debt by $7.8 billion. Return on capital employed increased to 17.7% from 7.6% a year earlier, consistent with higher earnings relative to the capital invested in the business.
Management also described where it intends to direct future investment. Chevron said its joint ventures in Venezuela plan to invest $7 billion over five years, with the goal of more than doubling production there. Separately, agreements involving its Bakken operations are expected to cut midstream costs by approximately 50%. Those are forward-looking plans and expected savings, not gains that have already been fully realized in third-quarter earnings.
For shareholders, the board declared a quarterly dividend of $1.78 a share. The payment is scheduled for December 10, 2026, for investors of record at the close of business on November 18. Those dates are the next specific shareholder milestones disclosed alongside the earnings results.
More from Investing
Latest News
View all news- New York Fed Researchers Find LinkedIn Hiring Data Can Improve Inflation Forecasts
- India’s Fiscal Deficit Reaches 42.1% of Annual Target in First Half of FY27
- Energy Department Opens $237 Million Funding Opportunity for U.S. Power Grid Supply Chain
- Chicago Business Barometer Falls to 55.3 in October but Signals Continued Expansion
- Federal Radiation Compensation Approvals Reach $909 Million, With More Than 50,000 Claims Pending
