
Chicago Fed Releases New Reading on U.S. Financial Conditions
The Chicago Fed’s latest weekly index stayed below its historical average, even as a risk subindex moved slightly closer to zero.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy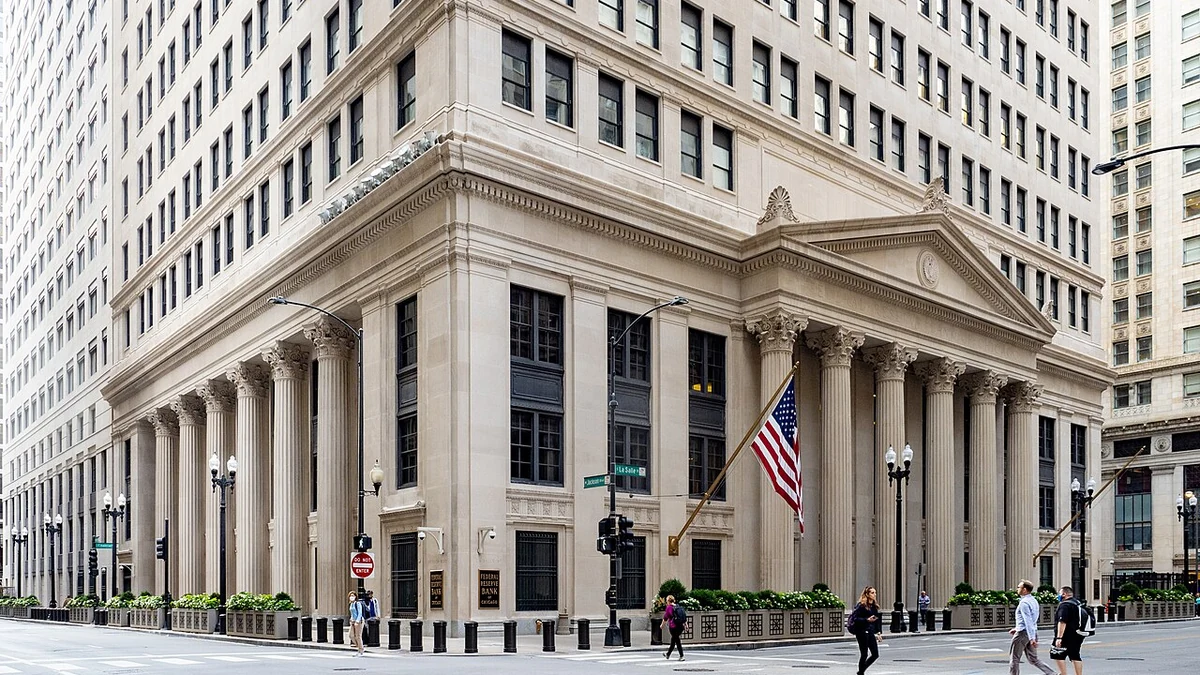
The Federal Reserve Bank of Chicago issued a new reading of its National Financial Conditions Index on Thursday, with the gauge at about minus 0.46 for the week ended November 6. The figure remained below zero, indicating that conditions across U.S. financial markets were looser than the index’s historical average despite some evidence of firmer risk conditions.
Because of a federal holiday, this update arrived Thursday rather than on the usual Wednesday schedule. The Chicago Fed’s calendar identifies November 12 as the release date for data through November 6. The reading covers the previous Friday, not market conditions at the moment investors read the report.
A week earlier, the published NFCI reading was minus 0.459 for the week ended October 30. The new figure rounds to roughly the same level, but that alone cannot establish that nothing changed: the Chicago Fed revises historical observations as fresh information becomes available. The key point in the latest release is that the broad index was still negative, rather than indicating unusually restrictive financial conditions.
The index remains below its historical benchmark
Unlike a market interest rate, the NFCI is a standardized measure combining many different signals. The Chicago Fed uses 105 indicators drawn from money markets, bond and stock markets, and traditional and nonbank financial institutions. A reading of zero represents the historical average for the index. Positive values are associated with tighter-than-average conditions, and negative values with looser-than-average conditions.
That makes minus 0.46 an index reading, not a borrowing rate, a percentage change or an estimate of how much credit costs have fallen. It describes where the overall financial environment sits relative to the index’s own history. Even a negative reading can move upward toward zero as funding becomes less accommodating, without crossing into conditions that are tighter than average.
The Chicago Fed’s current-data explanation sets out the distinction. The index aggregates signals that do not necessarily move together: borrowing conditions may change in one market even if another market remains stable. A single composite figure is useful for identifying the broad direction, but the individual measures matter when interpreting what that direction means.
For households and businesses, the distinction is practical. A relatively loose aggregate reading does not mean mortgage rates, credit-card rates or small-business borrowing costs are low for every borrower. Those rates also depend on the specific loan, the lender, prevailing benchmarks and a customer’s credit profile. The NFCI provides context about the financial system rather than a quote that borrowers can obtain.
Risk indicators show a modest shift toward tighter conditions
One piece of the weekly report did move closer to its historical average. The NFCI risk subindex was approximately minus 0.516 for the week ended November 6, compared with minus 0.528 for October 30, according to the Chicago Fed series published through the St. Louis Fed’s FRED database. The rise was small, and the risk measure remained below zero.
That subindex tracks volatility and funding risk in the financial sector. Movement toward zero can indicate a less favorable risk environment than the previous reading, but it does not by itself demonstrate a disruption in funding markets. Nor can the movement in one subindex be treated as an exact change in the overall NFCI, which reflects several groups of indicators with different weights.
The other major groups cover credit and leverage. Credit indicators help capture lending and financing conditions, including developments affecting households and businesses. Leverage indicators reflect relationships between debt and equity. An overall measure can therefore look fairly stable even when the conditions facing lenders, borrowers and investors diverge.
Readers can examine the NFCI data history published by the Federal Reserve Bank of St. Louis alongside the Chicago Fed’s component measures. The historical series also makes clear why the date attached to an observation matters: the report released on November 12 describes the week ending November 6, whereas newer daily market prices may already be reflecting different developments.
The adjusted index offers a different comparison
Chicago Fed economists also publish an adjusted National Financial Conditions Index, or ANFCI. It is not a second name for the headline NFCI. The adjusted series removes the part of the movements in its underlying financial indicators that is associated with prevailing economic activity and inflation. This is intended to show how financial conditions compare with what would typically be expected given the economy’s performance.
That distinction can be particularly relevant when economic growth and inflation are changing at the same time as market interest rates. A rise in bond yields, for example, might reflect shifting expectations about inflation or the economy as well as changes in investors’ willingness to accept risk. The adjusted measure provides another way to examine financial conditions without treating every market movement as an independent deterioration in access to finance.
Neither the NFCI nor the adjusted version is a Federal Reserve interest-rate decision. The indicators can help analysts assess the environment in which monetary policy operates, but the Chicago Fed does not set the central bank’s policy rate through this index. The readings also are not forecasts of a recession, a stock-market move or a particular lending rate.
Both indexes use information arriving at different frequencies, including weekly, monthly and quarterly observations. When those inputs are revised, the statistical model can change estimates for prior weeks. The Chicago Fed notes that revisions are usually small but can be more noticeable around the start of a month, when regularly revised data feed into the calculations.
The next scheduled NFCI release is November 18, covering the week ended November 13. It will provide another look at whether the broad financial environment remains below its historical benchmark and whether changes in risk are being matched by developments in credit and leverage.
More News
Latest News
View all news- National Vision More Than Doubles Adjusted Earnings Per Share but Cuts Sales Outlook
- U.S. Existing-Home Sales Plunge 5.5% to Lowest Level Since 2010
- Fed Governor Barr Warns AI Could Widen Wealth Inequality
- Canadian Building Permits Fall 4.1% as Residential Construction Intentions Weaken
- Dutch Business Bankruptcies Surge 27% in October, Official Data Shows
