
Fifth Third Reports $1.13 Adjusted Third-Quarter EPS Following Comerica Conversion
Reported EPS was $0.90 as merger-related charges continued, while net interest income and average deposits rose from the second quarter.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy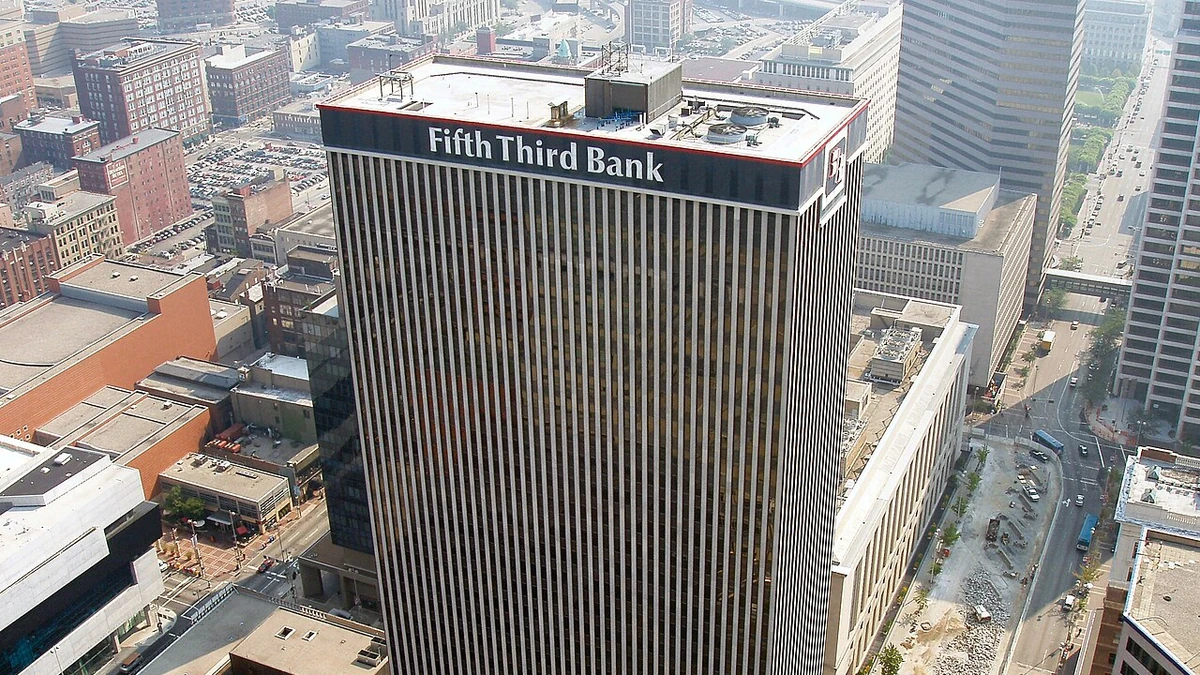
Fifth Third Bancorp reported adjusted earnings of $1.13 per diluted share for the third quarter of 2026 on Monday, after completing a major conversion of former Comerica customers and banking centers onto its systems. Reported earnings were $0.90 per diluted share, reflecting costs that continued to weigh on results following the banks’ merger earlier this year.
Net income available to common shareholders reached $828 million, up from $763 million in the second quarter and $608 million a year earlier. The reported per-share result improved from $0.83 in the preceding quarter but was slightly below the $0.91 recorded in the third quarter of 2025. Fifth Third’s average diluted share count was 37% higher than a year earlier, reflecting the much larger company following its all-stock merger.
The gap between reported and adjusted earnings deserves attention. In its third-quarter earnings release, Fifth Third identified a combined $211 million after-tax impact from certain items, equivalent to $0.23 per diluted share. That included $171 million of merger-related charges, $26 million associated with interchange litigation matters and $14 million of technology-related asset impairments. Adjusted EPS excludes those items and is a non-GAAP measure, not a substitute for the reported result.
Interest income grows despite higher deposit costs
Fully taxable-equivalent net interest income rose 3% from the second quarter to $2.276 billion, compared with $2.220 billion in the previous three months. The bank attributed the increase to higher market rates, the repricing of fixed-rate assets, management of its investment portfolio and loan growth. Year over year, the measure was up 49%, although much of that comparison reflects the addition of Comerica rather than growth from businesses Fifth Third already owned.
The increase in interest income did not translate into a wider net interest margin. That measure slipped to 3.34% from 3.36% in the second quarter, as higher interest-bearing deposit costs offset some of the benefit from earning assets. Fifth Third also cited the movement of former Comerica investment sweep balances from off-balance-sheet arrangements into interest-bearing deposits. The shift supports a larger funding base but carries an interest expense.
Fee income painted a more mixed picture. Reported noninterest income declined 5% from the prior quarter to $1.008 billion. The bank recorded lower capital markets and consumer banking revenue, though mortgage banking, commercial banking and wealth-management revenue improved. Excluding specified items, noninterest income edged up 1% to $1.052 billion, showing why the adjusted and reported comparisons point in different directions.
Costs also moved unevenly depending on the measure. Reported noninterest expense fell 3% from the second quarter to $2.049 billion, while expense excluding specified items and non-qualified deferred compensation declined 2% to $1.816 billion. Adjusted pre-provision net revenue, which measures earnings before setting aside money for credit losses, rose 8% to $1.512 billion. Fifth Third’s adjusted efficiency ratio improved to 54.6% from 57.1%, indicating lower adjusted operating costs relative to revenue.
The bank reported an adjusted return on average tangible common equity of 20.6%, up from 19.0% in the second quarter. Those measures help describe the operating trend but require the same qualification as adjusted EPS: they remove costs that shareholders still experience through the reported results. The merger has enlarged the earnings base, while expenses from completing it remain material.
Comerica systems conversion brings a bigger customer base
Fifth Third and Comerica completed their merger on February 1. The next operational test arrived over Labor Day weekend, when Fifth Third transferred approximately 600,000 customer accounts and converted 293 banking centers across Arizona, California, Florida, Michigan and Texas. The bank announced completion on September 8, putting the former Comerica operations under Fifth Third’s technology and branding during the final weeks of the quarter.
That timing matters for the earnings story. The full third quarter included most of the work leading up to the switch, but only a few weeks of operations after the systems conversion. Fifth Third said it retained clients and bankers through the process. Former Comerica customers also gained access to a broader set of Fifth Third banking, payments and wealth-management services, giving the company additional opportunities to deepen existing relationships rather than relying solely on acquiring new ones.
The footprint has become more important to Fifth Third’s growth plans. Management reported consumer household growth of 7% in the Southeast and 8% in the Southwest. The bank also said its deposits gained market share in Texas and California and cited strong deposit growth in several Texas metropolitan areas. These are company-reported operating indicators; the extent to which they translate into sustained earnings growth will depend on customer retention, lending demand and competition for deposits.
Fifth Third had outlined a target in a September investor presentation filed with the SEC of reaching $850 million in annualized pre-tax merger-related expense savings during the fourth quarter of 2026. It described itself as on track at that time, but the figure was a forward-looking run-rate target, not savings already realized in the third-quarter results. The company reported roughly $1.04 billion in merger-related charges within noninterest expense for the first nine months of 2026.
Those costs help explain the emphasis on adjusted profit, but they also make the next stage of execution consequential. Completing the technical switch removes a major operational milestone. It does not automatically guarantee the planned cost reductions or additional revenue from selling more services to former Comerica customers. Management’s ability to deliver those benefits without losing deposits or relationships will be a more meaningful test than completion of the conversion alone.
Deposit growth strengthens funding as credit stays mixed
Average deposits increased 3% from the previous quarter to $238.3 billion, compared with $231.5 billion in the second quarter. Fifth Third attributed the rise to ordinary deposit gathering, a retail campaign in the Southwest and the transfer of former Comerica sweep balances onto its balance sheet. Period-end deposits reached about $239 billion, with growth in interest checking partly offset by declines in money-market accounts and certificates of deposit.
Average portfolio loans and leases rose 1% to $179.2 billion, led by approximately $1.5 billion of growth in commercial lending. Because deposits grew faster than loans, the period-end portfolio loan-to-core deposit ratio eased to 76% from 77%. Average wholesale funding declined 10% to $23.3 billion, reducing the bank’s reliance on funding sources such as long-term debt and Federal Home Loan Bank advances.
Credit costs remained controlled but did not improve on every measure. Net charge-offs were $139 million, or an annualized 0.31% of average portfolio loans, compared with $135 million and 0.30% in the second quarter. The provision for credit losses fell to $122 million from $129 million. Nonperforming assets, meanwhile, represented 0.64% of the relevant portfolio at quarter-end, up from 0.60% three months earlier.
Fifth Third also noted that part of the increase in other real estate owned related to branch properties it no longer planned to use after the Comerica merger. That matters when interpreting the higher nonperforming-asset balance because those properties do not necessarily signal the same kind of deterioration as an increase in troubled borrower loans. Even so, the reported figures warrant monitoring rather than treating the bank’s credit position as uniformly improving.
The common equity tier 1 capital ratio stood at an estimated 10.02%, compared with 9.93% in June, supported by earnings generation and partly offset by higher risk-weighted assets. Fifth Third said it made no common-stock repurchases during the quarter. The final weeks of September offered an initial look at the business after the Comerica conversion; the fourth-quarter results will provide a fuller test of deposit retention, expense savings and performance on the unified platform.
More from Banking
Latest News
View all news- USPS Introduces New Rules for International Mailers Facing Customs Charges
- U.S. Treasury Sanctions Chinese Venture-Capital Funds Under Intellectual-Property Law
- IRS Finalizes Framework for Direct Credit- and Debit-Card Tax Payments
- DOJ Reports $849 Million in Approved Claims Under Expanded Radiation Compensation Program
- Cleveland-Cliffs Returns to Profit With $165 Million in Third-Quarter Net Income
