French Property Developers Report Further Deterioration in Housing Construction Outlook
An INSEE survey shows weaker plans for new housing starts, with demand for new homes and buyer-financing assessments also deteriorating in October.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy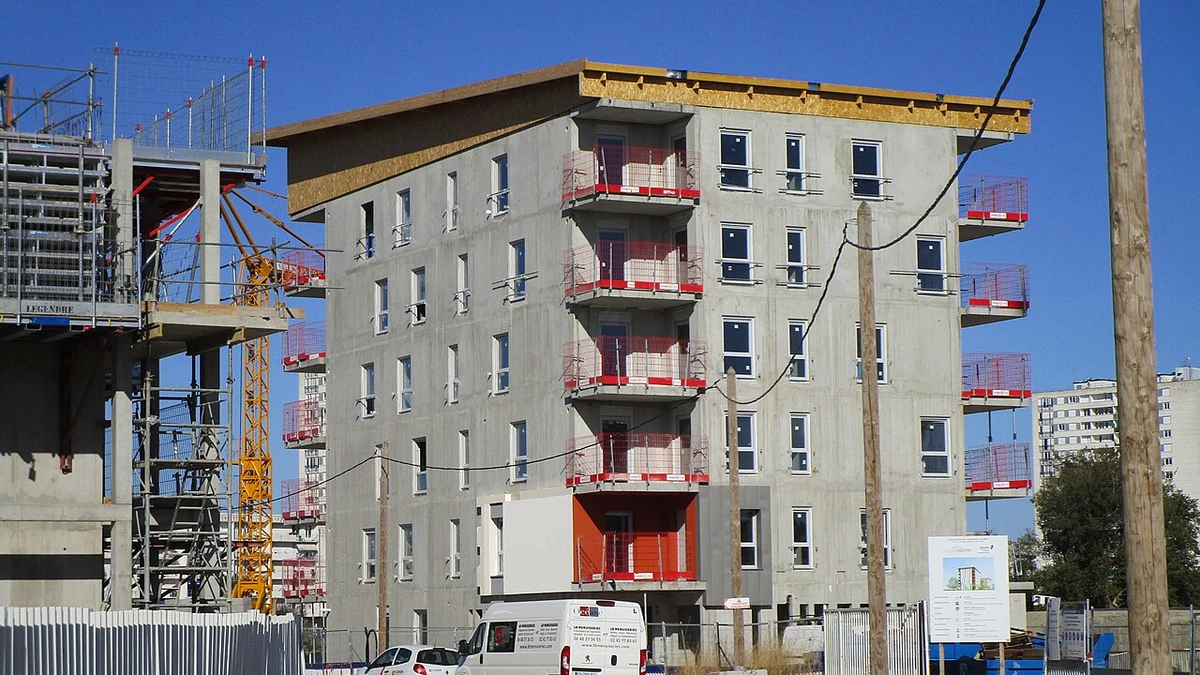
French property developers have grown more pessimistic about starting new housing projects, with the outlook worsening in October for both homes intended for sale and rental housing built mainly for social use. In a quarterly survey published Friday, France’s national statistics agency reported that the overall balance of housing-start expectations fell to -27 from -20 in July.
The assessment came alongside another drop in developers’ views of demand for newly built homes. New-home demand sentiment slipped to -43 from -37, its weakest reading in two years. Developers also assessed customers’ financing prospects and buyers’ own contributions more negatively.
These figures measure business sentiment rather than homes actually under construction. They indicate that more developers expect conditions to worsen than improve, but they do not mean that housing starts or sales have fallen by the percentages shown in the survey.
Housing Starts Outlook Weakens Across Project Types
INSEE’s October survey shows that the weakness extends across the two principal types of development it tracks. Expectations for starting homes intended for sale fell to a balance of -41 from -35 in July. That reading was well below the category’s long-term average of -18, pointing to a much more negative assessment than developers have typically reported over the survey’s history.
Developers were less downbeat earlier in the year. For homes intended for sale, the balance stood at -27 in January and improved to -20 in April before falling sharply over the following two quarters. Developers’ reluctance to start work has implications for the pipeline because projects need sufficient demand and must move through preparatory stages before construction begins.
The outlook for rental housing, a category consisting primarily of social housing, also turned negative. Its balance declined to -8 in October from +1 in July, moving below a long-run average of +1. Weakness was therefore not confined to projects marketed directly to private homebuyers.
Signs of caution appeared earlier in the project pipeline as well. Only 52% of developers said they were considering putting new programs under study with architects or design offices, down from 53% after three quarters of stability. The long-term average for that share is 62%. Studying a program is an early step, not the same thing as obtaining approval or beginning construction, but the measure gives another indication of firms’ willingness to prepare future developments.
Demand sentiment, at -43, was substantially below its long-term average of -13. INSEE said it had not been this low for two years. Unsold-housing inventory sentiment, meanwhile, was unchanged at -10, still above its historical average of -25. Demand worries have therefore deepened even though the inventory balance held steady this quarter; the survey does not provide an actual count of unsold properties.
Financing and Price Assessments Deteriorate
Prospective buyers’ financial position is another source of concern in the responses. Developers’ expectations for changes in customer financing registered a balance of -39, down from -35 in July. It was also more negative than its long-run average of -21, suggesting that financing conditions, as developers perceive them, remain an obstacle to improving confidence in new-home demand.
Developers’ assessment of how purchasers’ personal contributions had changed over the previous three months deteriorated to -26 from -21. INSEE said that was the weakest reading since January 2015. This question concerns the direction of change in buyers’ own funds, not the average amount of a deposit or the share of a purchase price that buyers contribute.
Pricing expectations were weaker too. At -24, down from -15, the balance concerning changes in the average prices of homes being offered for sale reached its lowest level since April 2015. That is a statement about developers’ assessment of price movements, not evidence that the actual selling price of a new home declined by 24%.
Taken together, the results describe a market in which developers see weaker demand and less supportive buyer finances at the same time as pressure on the prices of new homes. Those conditions could make it harder to judge when a project is commercially viable. INSEE’s survey does not establish a single cause for the deterioration, however, or measure how many planned developments have been canceled or postponed.
INSEE gathered the responses between September 25 and October 20. Response rates for this survey are also usually lower than for most of INSEE’s other business surveys, another reason to treat the balances as indicators of sentiment rather than a census of the entire French development industry. A balance of -39, for example, is not a finding that 39% of buyers have been denied credit.
Construction Data Show Why the Distinction Matters
Separate government data on actual building activity, most recently available for August, show a more mixed picture. France issued an estimated 29,749 housing permits that month, down 1.1% from July on a seasonally adjusted, working-day-adjusted basis. Over the 12 months through August, permits totaled 369,723, or 9.7% below the average annual level of the preceding five years.
Estimated housing starts, by contrast, rose 4.1% from July to 27,663 units in August. Over the 12 months through August, housing starts totaled 300,244, still 9.5% below the five-year average. Both observations are relevant: a monthly improvement in work getting under way does not eliminate the longer-running shortfall, and an October survey of intentions does not establish that activity was already declining in August.
Construction statistics cover a wider range of homes than those represented by the property-developer sentiment survey. August estimates included 16,983 starts in collective housing, including residences, and 10,680 individual-home starts. The collective category was up 4.9% from July, while individual starts rose 2.8%. Those figures describe building activity across the country, not solely projects sold by surveyed developers.
For the first eight months of 2026, the government estimated that the average monthly number of housing starts was 21.2% higher than the average for 2025 as a whole. That points to some recovery in recorded activity compared with last year, even as developers’ more recent assessment of the pipeline has weakened. Because the statistics measure different populations and periods, neither provides a direct numerical forecast of the other.
There is also substantial uncertainty around the newest starts estimates. SDES, the government’s statistical service, warned that August figures were especially vulnerable to revision because of limited initial reporting. Its estimate of August starts was based on reported information covering only 27.1% of the units, with the rest requiring statistical estimation. Such extensive estimation leaves room for the latest movement to be revised as more reports come in.
A separate INSEE survey released on October 22 put the wider building industry’s business-climate index at 95, down from roughly 96 in September and below its long-term average of 100. Construction firms’ assessment of past activity weakened, although their expectations for future activity improved. Those respondents are not identical to the property developers in the quarterly survey, and the different signals underline the need to distinguish sentiment about future housing projects from current building work.
INSEE’s next quarterly survey of property developers is scheduled for January 26, 2027. Its results will show whether October’s worsening outlook has persisted into the new year, while subsequent building-permit and starts releases will provide a separate measure of what has actually reached construction sites.
More News
Latest News
View all news- University of Michigan Research Warns Long-Term Inflation Expectations Could Become Entrenched
- First Citizens Authorizes $1.2 Billion Share Buyback Alongside Third-Quarter Earnings
- American Express Raises 2026 Profit Outlook After Record $20.1 Billion Quarterly Revenue
- U.K. Retail Sales Fall 0.4% in September Despite Third-Quarter Growth
- Japan’s September Consumer Inflation Reaches 2.1%, With Underlying Prices Up 2.4%