
German Companies Plan Fewer Job Cuts, but Auto Industry Remains Under Pressure
Germany’s ifo Employment Barometer edged up to 95.5 in October, but manufacturers still plan to reduce headcount, particularly in the automotive industry.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy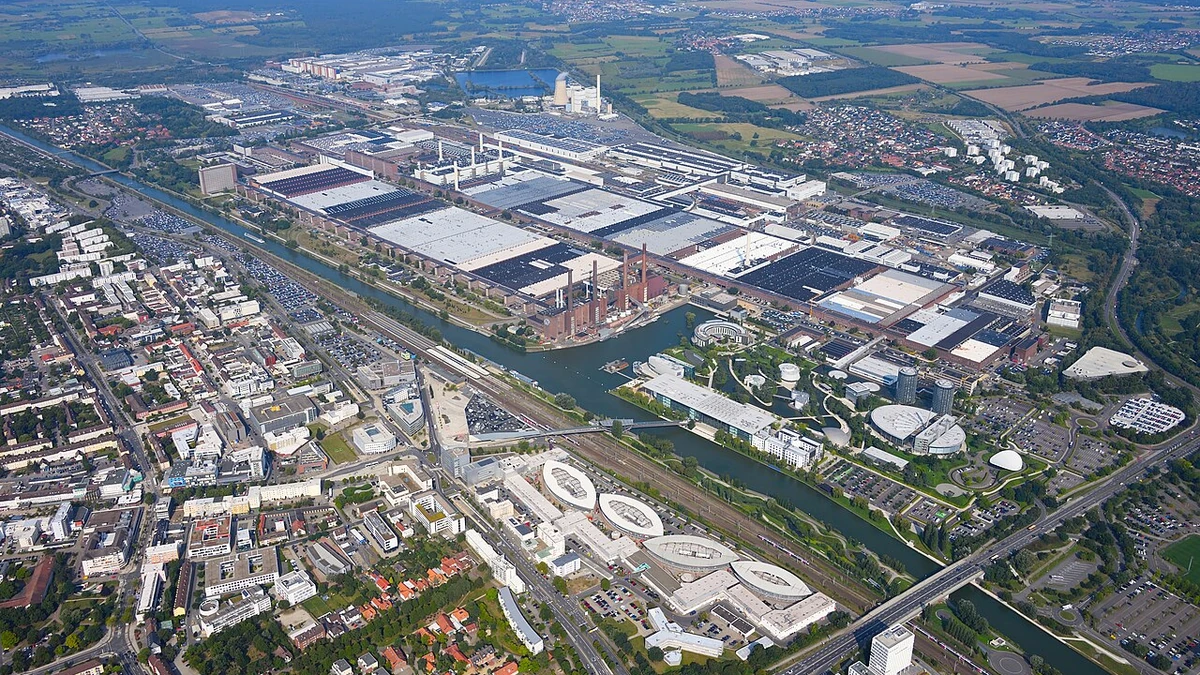
German companies are becoming less inclined to cut jobs, but the country’s automotive industry is still preparing for further workforce reductions, according to a survey released Wednesday by the ifo Institute.
The ifo Employment Barometer rose to 95.5 points in October from 95.1 in September. The modest improvement suggests that employers are growing more cautious about reducing staff rather than gearing up for a broad hiring rebound. Manufacturing remained an exception to the better overall reading, with carmakers among the businesses facing continued pressure to shrink their workforces.
Klaus Wohlrabe, ifo’s head of surveys, said the economic improvement was not yet strong enough to support widespread expansion in employment. Service businesses showed more willingness to hire, but companies in retail and wholesale trade continued to plan with fewer employees. Construction firms also indicated a slight reduction in staffing.
Hiring intentions improve, but the recovery remains narrow
The October ifo employment survey shows an uneven labor market rather than a uniform improvement. Manufacturers of data-processing equipment, electronic goods and optical products reported plans for additional hiring. That contrasts with the broader manufacturing sector, where companies still expect to operate with fewer staff.
Temporary employment agencies also became more confident as the economic outlook improved. That is a useful indicator of companies’ willingness to bring in additional workers, although ifo did not provide a figure for how many positions agencies expect to fill. Among other service providers, the balance of hiring plans was more positive than in September, when intentions to add and reduce jobs were broadly even.
October marked another small step up in the employment barometer. The indicator had reached 94.8 in August and 95.1 in September before its latest increase. Those readings point to less pressure on employment than earlier in the year, but the direction of the index should not be confused with an increase in actual payrolls. It measures businesses’ staffing intentions, which may change before any hiring or layoffs take place.
The distinction is particularly important because other German business surveys have become more encouraging. On October 26, ifo reported that its broader Business Climate Index rose to 90.2 from 89.9 in September. Manufacturers assessed their current business conditions and prospects more favorably, and reported stronger incoming orders along with plans to expand production.
Better production prospects do not automatically mean companies are ready to add permanent staff. The October reports measure different decisions: how much business companies expect to do and how many people they intend to employ. The improving readings can therefore coexist with continued caution about headcount, particularly in industries where recent reductions have already been substantial.
Official labor-market figures also argue against treating the latest ifo rise as a completed turnaround. Germany’s Federal Employment Agency reported 2.994 million unemployed people in September and an unemployment rate of 6.4%. The unadjusted total fell by 67,000 from August, but after seasonal adjustment unemployment increased by 12,000. The different movements show why a favorable monthly headline alone offers an incomplete picture of labor demand.
Auto manufacturers and parts suppliers face persistent job losses
Automotive employers remain among the clearest sources of weakness in the October survey. In its separate assessment released on October 5, ifo said the industry’s business-climate indicator had fallen to minus 35.0 points in September from a seasonally adjusted minus 22.0 in August. Automakers had downgraded their views of current business conditions, and expectations for employment and exports also declined during September.
The industry’s concerns extended beyond hiring plans. According to that earlier ifo survey, businesses rated their order backlogs less favorably, while companies reported a marked deterioration in third-quarter earnings compared with the second quarter. Those were companies’ survey assessments, not an independently calculated total for the sector’s profits, but they help explain why employment decisions remained cautious.
There is evidence of reductions already carried out. The Federal Statistical Office’s automotive employment figures showed 691,500 people working in the industry at the end of June 2026, down 42,300, or 5.8%, from a year earlier. Destatis said that was the lowest headcount recorded since 2005 and the sharpest annual percentage decline among Germany’s major manufacturing industries with more than 200,000 employees.
The losses were spread unevenly within automotive manufacturing. Vehicle and engine producers employed 429,200 people, a 6.1% decrease from a year earlier. Manufacturers of motor-vehicle parts and accessories had 219,500 workers, a steeper decline of 7.6%. Employment at producers of bodies, trailers and related equipment moved in the opposite direction, growing 10% to 42,800.
For comparison, employment across German manufacturing was 5.29 million at the end of the first half, down 144,100, or 2.7%, from a year before. The automotive workforce therefore contracted at more than twice the rate of manufacturing overall. The industry nevertheless remained the country’s second-largest manufacturing employer after mechanical engineering, according to Destatis.
Those figures cover establishments with at least 50 employees in the relevant manufacturing categories. They do not include every business whose revenue depends on the car industry, such as suppliers classified under other industries. Changes in how an establishment’s main activity is classified can also affect the totals. Most importantly, the June headcount figures measure an earlier period than ifo’s October survey and cannot be treated as a count of job losses occurring this month.
Export optimism improves before the hiring outlook
A separate ifo release on October 27 offered a more positive signal for German industry. Its export expectations indicator increased to 12.2 points from 9.0 in September, reaching its highest level since February 2022. Automotive companies were among those revising their expectations most sharply upward, and car manufacturers again anticipated rising exports after a negative outlook in September.
The improvement in export sentiment is relevant because German automakers sell heavily into overseas markets, but an expectation of stronger exports is not the same as a confirmed increase in shipments. Nor does it establish that companies have abandoned previously planned workforce reductions. The October employment survey still found that carmakers intended to reduce staffing, even as the separate export survey became more upbeat.
German manufacturers thus face two different near-term signals: a stronger outlook for orders and exports, and continued reluctance to expand payrolls. The surveys do not establish how quickly improved sales expectations might affect staffing. Companies could also adjust production without matching every change in demand with a new permanent position, making labor plans a slower-moving measure of recovery.
The next official reading on Germany’s wider labor market is scheduled for October 30, when the Federal Employment Agency will publish its October figures. Those results will offer evidence of whether the easing in employers’ planned cuts is appearing in national unemployment data, although they will not provide a direct count of automotive layoffs in October.
More News
Latest News
View all news- Sensex, Nifty End Lower in Diwali Muhurat Trading, Breaking Eight-Year Winning Streak
- Bank of Israel Finds 62% of Survey Respondents Faced Financial Fraud Attempts
- Singapore’s Lee Urges Australia to Invest More in Southeast Asia
- New Zealand’s Revised Parliamentary Funding and Expense Rules Take Effect
- U.S. Emergency Power Orders for Puerto Rico Take Effect, Extending Grid Support Into February
