
Guardian Pharmacy Converts Final 13.5 Million Reorganization Class B Shares Into Class A Stock
Guardian Pharmacy said 13.52 million Class B shares issued in its 2024 reorganization will automatically convert into Class A stock on Sept. 27, lifting Class A shares outstanding to 63.32 million and completing the last scheduled IPO-era tranche.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy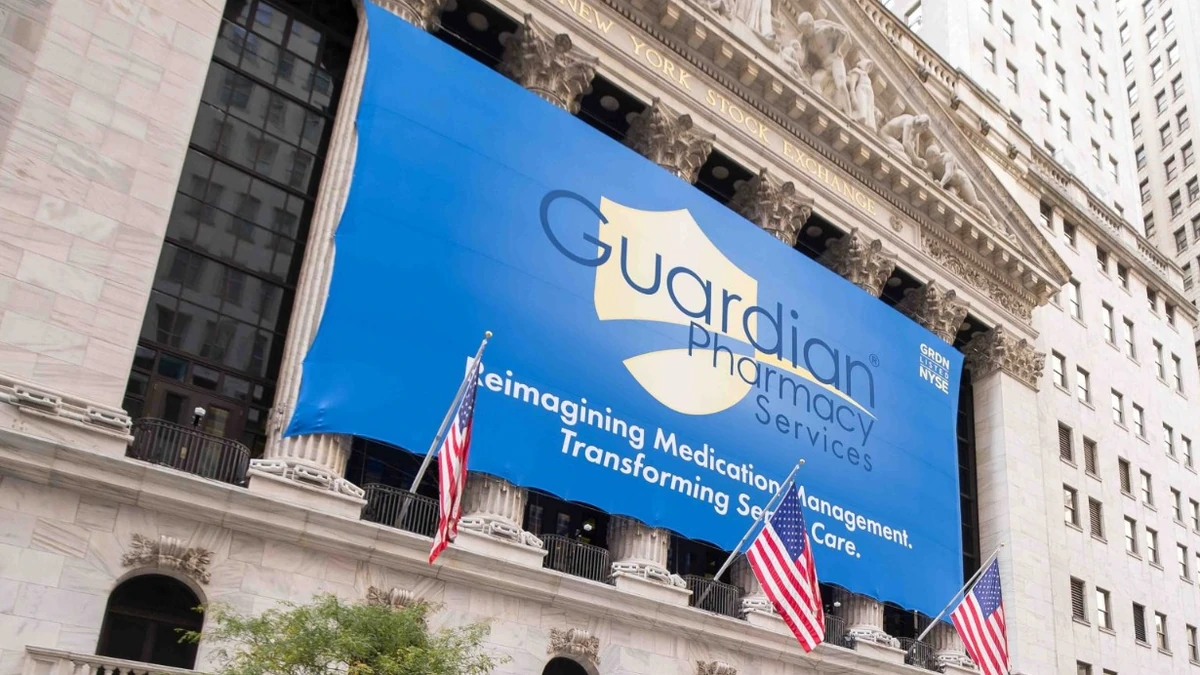
Guardian Pharmacy Services’ final scheduled tranche of Class B shares from its 2024 reorganization is set to convert automatically into Class A stock on Sunday, Sept. 27, moving 13,521,396 shares into the listed class and lifting total Class A shares outstanding to 63,320,300.
The change does not amount to a new capital raise or a discretionary insider sale. It is a charter-driven, one-for-one conversion that was built into the company’s structure when it reorganized and went public in 2024. Because the conversion date falls on a Sunday, the shift in Guardian’s capital structure will take effect before regular trading resumes on Monday.
In a Sept. 10 filing with the Securities and Exchange Commission, Guardian said the conversion covers the final tranche of Class B shares that were issued in the September 2024 reorganization. The same filing said the company simultaneously entered lock-up agreements with founders, executive officers and certain other employees, a detail that matters because it limits how much of the enlarged Class A pool is likely to become immediately available for sale.
Conversion completes the last scheduled reorganization tranche
Guardian’s public-company structure was designed so that the Class B shares created in the reorganization would not all convert at once. In its IPO documents, the company said 54,094,232 Class B shares were issued in the merger and related restructuring that preceded the offering. Those shares were scheduled to convert into Class A stock in four substantially equal tranches on March 28, 2025, Sept. 27, 2025, March 28, 2026 and Sept. 27, 2026.
That schedule is why Sunday’s event is significant even though it was not announced on Sunday itself. It closes out the last automatic conversion step tied to that original block of reorganization shares. In practical terms, investors who focus on float, insider ownership and future supply now have a cleaner post-IPO structure to work with than they did over the last two years, when these periodic tranche conversions were still unfolding.
The company’s Sept. 10 filing put the new Class A total at 63,320,300 shares after the conversion. That is a meaningful jump from the 49,798,904 Class A shares and 13,543,400 Class B shares that Guardian reported were outstanding as of Aug. 3 in its latest quarterly report. The numbers also explain why it is more precise to call Sunday’s event the final reorganization tranche rather than the conversion of every Class B share outstanding. The final scheduled tranche is 13,521,396 shares, slightly below the Class B total the company reported in August, so the safer reading is that the filing covers the last large block created in the 2024 reorganization.
That distinction matters because the headline effect can sound bigger than the economic reality. The conversion shifts shares from one class to another on a one-for-one basis, but it does not by itself create fresh proceeds for Guardian or represent an open-market decision by insiders to buy or sell. The key change is in the mix of outstanding stock and in how much of the company now sits in the publicly traded Class A line.
Lock-up agreements temper the immediate float effect
The other important element in the Sept. 10 filing is the lock-up package. Guardian said that, after giving effect to the Sept. 27 conversion, about 29.9 million Class A shares held by founders, executive officers and other employees who owned stock before the IPO will be subject to lock-up agreements running through Sept. 14, 2027, subject to limited exceptions and company consent.
Guardian said those restricted shares represent about 81% of the roughly 37 million Class A shares that will be held by that pre-IPO insider group after the conversion. Put differently, the conversion increases the Class A count, but it does not automatically mean an equivalent block of stock is about to hit the market. A large portion of the insider-held shares will remain restricted for nearly another year.
That may matter more to investors than the mechanics of the conversion itself. Conversions between classes can raise concerns about near-term selling pressure, especially when they increase the amount of listed stock. Here, the lock-up language suggests Guardian was trying to address that issue directly by pairing the final tranche conversion with a fresh commitment from insiders not to dispose of most of those shares during the stated period.
None of that eliminates overhang concerns entirely. Restricted stock still represents potential future supply, and investors will likely keep watching how Guardian’s ownership profile evolves in later filings. But the immediate effect is more controlled than it would be if the 13.5 million-share tranche converted without any accompanying restraint on insider sales.
Guardian enters the conversion with rising guidance and a stronger balance sheet
The capital-structure change is arriving against a backdrop of improving operating performance. In its second-quarter 2026 results, Guardian said revenue rose 2% from a year earlier to $351.8 million, while residents served increased 8% to about 210,000. Net income reached $22.1 million, although that figure included an $8.5 million settlement tied to a payor dispute. Adjusted EBITDA increased to $29.7 million from $25.0 million a year earlier.
The company also said it ended June with $89.8 million in cash and cash equivalents and no long-term debt outstanding under its credit facility. It raised its full-year 2026 outlook to $1.43 billion to $1.45 billion in revenue and $129 million to $131 million in adjusted EBITDA. Those figures do not directly change the meaning of Sunday’s conversion, but they help explain why the company may be comfortable locking up a large insider block while allowing the planned class shift to proceed.
Guardian’s operating story has also continued to include measured expansion. Alongside the second-quarter release, the company said it had completed the acquisition of Wellness Concepts in Virginia after quarter-end and opened a new greenfield pharmacy in Lexington, Kentucky, its first location in that state. That does not make the share conversion a growth catalyst by itself, but it does place the event within a business that is still expanding its footprint rather than simply cleaning up a capital structure in isolation.
For investors, the main takeaway is that Sunday’s conversion is best understood as the last scheduled step in Guardian’s reorganization-era equity rollout, not as a surprise financing or a new strategic move. It simplifies the post-IPO structure, raises the number of Class A shares outstanding and leaves a large insider-owned portion of that stock subject to lock-up through Sept. 14, 2027, the next clear date tied to this block of shares.
More from Investing
Latest News
View all news- UK Backs £43 Million Cornwall Lithium Project With Nearly £10 Million Support
- Adobe’s David Wadhwani Steps Down as Creativity & Productivity President
- DOE Order Keeping Colorado’s Craig Coal Unit Available Takes Effect
- Dutch Anti-Greenwashing Rules Take Effect for Consumer-Facing Businesses
- Qatar Financial Centre, U.S. Chamber Sign Cross-Border Investment MoU
