
India’s Economy Estimated to Grow 7.35% in Q2 as Finance Ministry Flags Inflation Risks
The Finance Ministry’s nowcast points to continued growth in July-September, but higher food prices, costly oil and crop uncertainty complicate the outlook.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy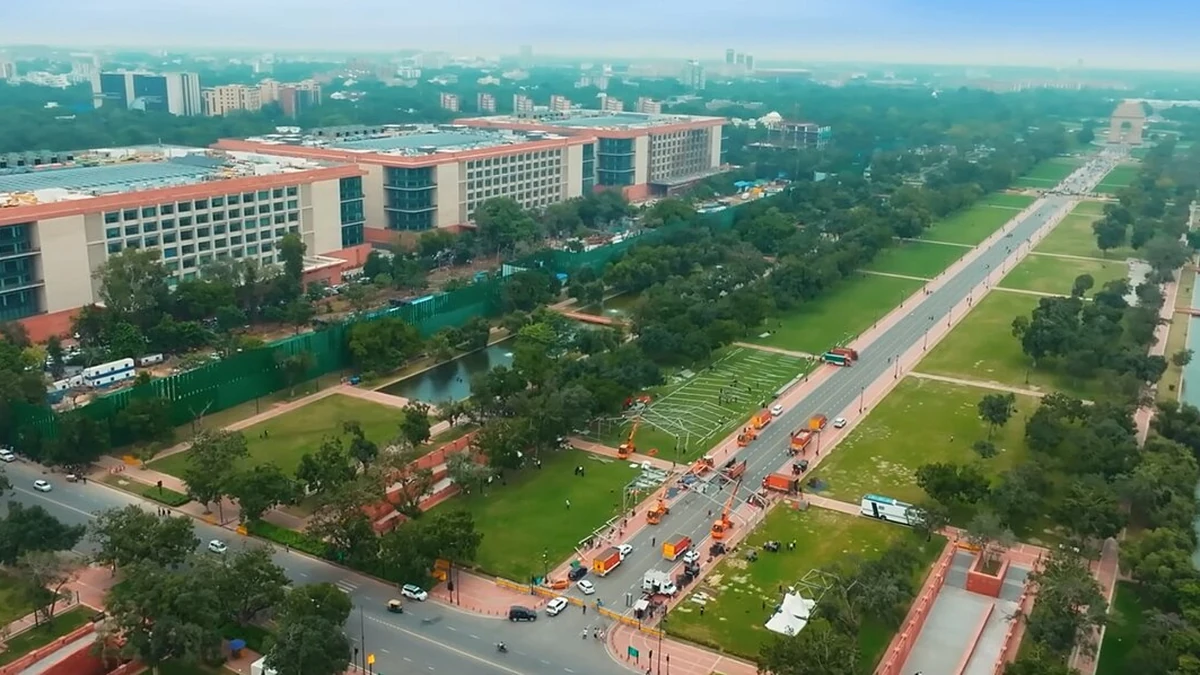
India’s economy is estimated to have grown 7.35% in the July-September quarter of the 2026-27 financial year, according to the Finance Ministry’s October economic review released on Thursday, October 29. The assessment points to continued expansion in domestic activity, but the ministry also warned that rising prices and uncertainty over agricultural supplies could complicate the outlook.
The figure comes from a nowcasting model used by the Department of Economic Affairs. It is a preliminary estimate of real gross domestic product growth, not the official second-quarter result. If confirmed, it would mark a moderation from the 7.8% year-over-year increase recorded in April-June, rather than a contraction in economic output.
The department had estimated second-quarter growth at about 7.3% in its September review, so the latest 7.35% reading represents only a small upward adjustment. The Finance Ministry’s Monthly Economic Review publication series tracks changes in output, prices, trade and financial conditions as economic data become available. Its October estimate is based on indicators released before the complete national accounts are compiled.
That distinction is important for interpreting the number. A growth rate above 7% would still represent a substantial year-over-year increase in inflation-adjusted output. The difference between the first and second quarters would show some easing in the pace of expansion, but by itself would not establish that domestic demand or investment had weakened across the economy.
Industrial activity supports the estimate, though September was slower
The ministry cited industrial production, energy consumption, port traffic, goods and services tax collections and vehicle sales among the indicators supporting its assessment. These measures give policymakers an earlier view of activity than the quarterly GDP publication. They also capture different parts of the economy, which is why strong readings in several series cannot be treated as a final GDP calculation.
Official industrial production figures illustrate both the momentum and the variation. The Index of Industrial Production rose 8.0% from a year earlier in August, with manufacturing output up 9.0%. By September, overall industrial production growth had eased to 6.7%, and manufacturing growth was 7.6%, according to the Ministry of Statistics and Programme Implementation’s October 28 release. Both months showed expansion, although the latest monthly reading was less rapid.
A separate measure, the Index of Core Industries, increased 7.9% year over year in September, compared with a revised 5.9% in August. The core-industry index covers key infrastructure-linked activities and is not directly interchangeable with the broader industrial production index. It nevertheless provides another indication of demand for energy, materials and industrial output during the quarter.
The Finance Ministry also pointed to stronger automobile sales and tax receipts as signs of continuing consumption and business activity. Bank lending expanded 21.6% year over year at the end of September, according to figures discussed in the review. Credit growth can support spending and investment, but it does not by itself show how much new productive capacity companies are building or how evenly the benefits are being felt.
There are limits to what the monthly numbers can establish. Industrial output can be influenced by shifts in production schedules and comparison periods, and the economy’s large services sector is not captured by a factory-output index. The 7.35% nowcast brings several signals together, but the official GDP release will provide a fuller account of services, agriculture, consumption and investment.
Food inflation and oil costs create a harder policy backdrop
The growth estimate comes as household prices are rising more quickly. India’s consumer price inflation reached a provisional 5.54% in September, up from a revised 4.83% in August, according to the official September consumer price index release. The increase of 0.71 percentage point in a month pushed headline inflation further above the Reserve Bank of India’s 4% target.
Food costs were a major pressure point. The consumer food price index rose 7.74% from a year earlier in September, compared with 5.97% in August. Rural headline inflation stood at 6.08%, above the 4.88% reported for urban areas. Those differences matter because the effect of higher food prices depends partly on where households live and how much of their spending goes toward essentials.
For the Finance Ministry, the immediate concern is not simply that inflation has risen. Higher global crude oil prices and disruption to shipping routes in West Asia can increase costs for transport, energy-intensive production and imports. Whether those expenses reach retail prices depends on supply contracts, domestic policies and the extent to which businesses absorb them. The ministry described them as risks to the inflation outlook, not as a certainty that all costs will be passed on to consumers.
Agriculture adds another source of uncertainty. The review cited concerns about the kharif crop and the possibility that adverse weather could affect food supplies. A weaker harvest or delays in bringing produce to market can put pressure on particular food categories even when factory and service activity remains healthy. The extent of any impact will depend on actual crop yields, inventories and supply-management measures.
Faster consumer-price increases can also change how economic growth feels to households. GDP growth is measured after adjusting for prices, while families face the rupee amounts charged for food, transport and other necessities. When essentials rise faster than incomes, consumers may have less money available for discretionary spending. That is a potential constraint on demand, although the latest price figures alone do not establish that a broader spending slowdown has begun.
The official GDP release will provide the next test
The Finance Ministry’s relatively strong second-quarter estimate leaves policymakers managing competing signals. Output measures still suggest expansion, and credit and industrial activity point to continuing business demand. At the same time, the inflation figures underline the difficulty of supporting growth without adding to price pressures. The ministry’s October review characterized maintaining activity while protecting price stability as a priority for the second half of the fiscal year.
The comparison with April-June also needs a consistent statistical basis. The Ministry of Statistics and Programme Implementation reported first-quarter real GDP growth of 7.8% using the national accounts series based on 2022-23 prices. The latest Finance Ministry estimate is also stated in real terms, but it remains a model-based reading subject to replacement by the official estimate once more complete data are incorporated.
A nowcast is designed to provide a timely picture before that release. It can change as fresh data on output, consumption, government expenditure and other components arrive. Small differences between successive nowcasts, such as the change from 7.3% to 7.35%, should not be mistaken for precise knowledge of the quarter’s final growth rate.
The Ministry of Statistics and Programme Implementation has scheduled publication of the July-September 2026 GDP estimates for November 30. Those figures will show whether the economy matched the Finance Ministry’s projection and provide the expenditure and sector breakdowns needed to assess how broad the expansion was.
More News
Latest News
View all news- DoorDash Agrees to Acquire Instacart in $17 Billion Deal
- Thrive Holdings Agrees to Buy ADT for $15.3 Billion
- U.S. Economic Growth Accelerates to 3.4% in Third Quarter
- Freddie Mac Reports $3.2 Billion Quarterly Profit as Mortgage Portfolio Expands
- Justice Department Names New Director of Federal Bankruptcy Oversight Program
