
Irish Non-Banks Now Hold 15% of Mortgage Balances, Central Bank Data Show
The non-bank share has more than doubled from 7% a decade ago, with weighted-average rates on principal-dwelling mortgages at 3.58% in June.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy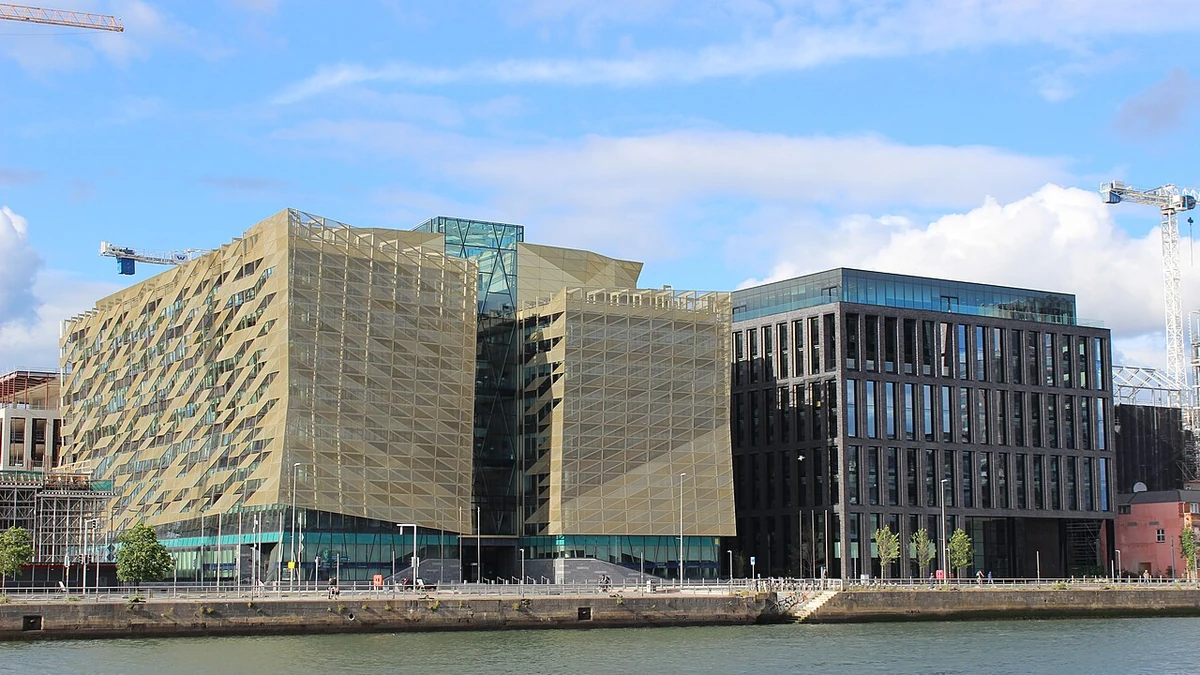
Non-bank financial institutions held 15% of Ireland’s outstanding mortgage balances at the end of June 2026, more than double their 7% share a decade earlier, according to data published by the Central Bank of Ireland. The figures show how much of the mortgage stock now sits outside traditional banks, even as the pricing of those loans varies sharply by mortgage type and by the kind of non-bank institution holding them.
The weighted-average interest rate on principal-dwelling-home, or PDH, mortgages held by non-banks was 3.58% at the end of June. That was 7 basis points lower than a year earlier. Buy-to-let mortgages held by non-banks carried a lower weighted-average rate of 3.32%, leaving the PDH rate 26 basis points higher.
The data come from the Central Bank’s new non-bank mortgage interest-rate series, which uses information from the Central Credit Register. The series distinguishes between non-banks that originate mortgages and non-banks that mainly hold or service loans acquired from other lenders. That distinction matters because the growth in non-bank ownership does not mean all of those mortgages were originally written by non-bank lenders.
Non-bank mortgage ownership has more than doubled in a decade
The rise from 7% to 15% of outstanding mortgage balances over 10 years marks a substantial shift in where Irish mortgage debt is held. The Central Bank defines non-banks for the purposes of this publication as lenders or holders of mortgage loans that are not banks, credit unions or government-sponsored entities. The category includes retail credit firms and credit servicing firms.
Within the non-bank PDH market, the larger share of balances is still held by institutions that do not originate new mortgages. Non-lending non-banks held 60% of the outstanding PDH amount in the segment at the end of June, compared with 40% for lending non-banks.
The interest-rate profiles of those two groups were different. Lending non-banks charged a weighted-average PDH mortgage rate of 3.70%, up 18 basis points from the same point in 2025. Non-lending non-banks had a weighted-average rate of 3.51%, down 22 basis points from a year earlier. The gap shows that the broad non-bank category contains portfolios with different rate profiles.
Non-lending firms can hold older loans bought from originating institutions, including mortgages with pricing terms that reflect earlier interest-rate environments. The Central Bank’s data therefore show the current holder of the mortgage, rather than implying that the holder originally set every loan’s terms.
Variable-rate loans remain the most expensive part of the mix
The largest pricing gap appears when non-bank PDH mortgages are split by interest-rate type. Variable-rate mortgages had a weighted-average rate of 4.73% at the end of June, well above the 3.33% average for tracker mortgages and the 2.90% average for fixed-rate mortgages.
Those figures moved in different directions over the year. The average fixed rate was 21 basis points higher than in June 2025, while the variable-rate average was 23 basis points lower. Tracker mortgages were little changed, with their average rate down 2 basis points from a year earlier.
The composition of the non-bank PDH book also shifted toward fixed rates. Fixed-rate mortgages accounted for 41% of outstanding PDH balances held by non-banks at the end of June, up from 36% a year earlier. Tracker loans fell to 28% of balances from 31%, while variable-rate loans declined to 31% from 33%.
The Central Bank said the rising fixed-rate share and falling tracker share partly reflect the legacy nature of tracker mortgages, which on average have shorter remaining maturities. That helps explain why the mix can change even without a single uniform repricing across the entire non-bank portfolio.
Average balances are highest in Dublin, Wicklow and Kildare
The average outstanding balance on a non-bank-held PDH mortgage was about €166,000 at the end of June. Dublin had the highest county-level average at roughly €209,000, followed by Wicklow at €199,000 and Kildare at €184,000.
There were also geographic differences in which kind of non-bank held the loans. Non-lending non-banks were particularly prominent in Donegal, where they accounted for about 74% of non-bank PDH mortgage balances. Lending non-banks held a slight majority only in Cork and Sligo, with shares of 52% and 51%, respectively.
For borrowers, the data underline why the label “non-bank” is too broad to describe the cost of a mortgage on its own. A loan held by a non-bank may be fixed, tracker or variable; it may have been originated by the current holder or acquired from another institution; and its rate can reflect the terms of a much older mortgage contract. The 3.58% PDH average therefore describes the portfolio as a whole, not a single rate available to all borrowers.
The Central Bank is publishing the figures as Frontier Statistics, a category used for data and methods that are still in development and may be revised more often than official statistics. The non-bank mortgage series is scheduled to be updated quarterly. For now, the June figures put the non-bank share of Irish mortgage balances at 15%, with the biggest pricing difference inside the segment running between variable-rate and fixed-rate PDH loans.
More from Banking
Latest News
View all news- Google, Constellation Sign 3.59-GW PJM Power Deal, With $4.3 Billion-Plus Going to Nuclear Uprates
- RPM Posts Record $2.22 Billion Fiscal Q1 Sales, Narrows FY2027 Outlook
- Zscaler Reaffirms Q1 and FY2027 Financial Guidance at Investor Day
- U.S. Trade Deficit Widens 13.7% to $105.6 Billion in August as Imports Surge
- Type One Energy Raises $200 Million Series B to Advance Tennessee Fusion Project
