Japan’s 30-Year Government Bond Auction Draws Bids as Long-Term Yields Stay Elevated
Japan sold 30-year bonds at a 3.847% average auction yield, below October's level but above last year's, as bidding coverage eased from the previous sale.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy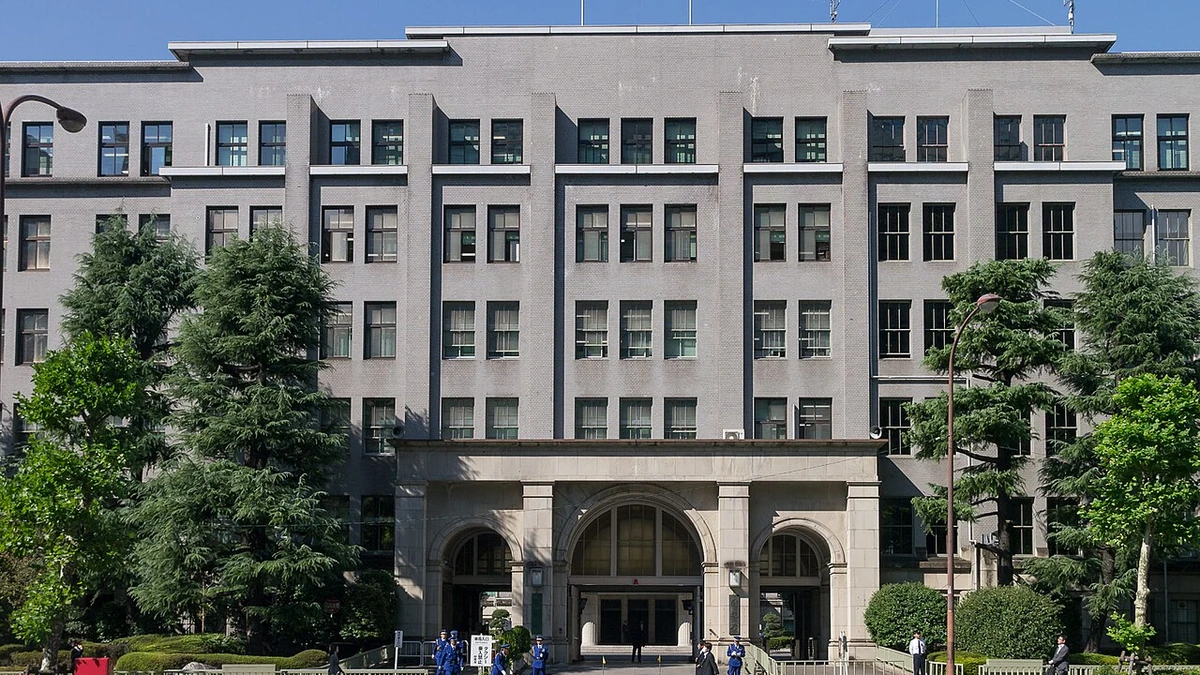
Japan’s Ministry of Finance sold 30-year government bonds on Tuesday, November 10, with a yield of 3.847% at the weighted-average accepted price, drawing ¥1.5126 trillion in competitive bids for ¥450.7 billion of competitively allotted bonds. The bids amounted to about 3.36 times the competitive awards, showing that buyers remained willing to take on long-dated Japanese debt at the prices accepted by the government.
The result captured a mixed picture of the market. The average yield fell from 4.109% at the October auction of the same bond issue, but remained above the 3.166% recorded at the comparable sale a year earlier. Competition measured by bids relative to competitive awards also eased from October, even as bonds were allotted at higher prices.
Bidding coverage eased from October
The Ministry of Finance’s auction results show that investors submitted ¥1.5126 trillion in competitive bids, with ¥450.7 billion accepted through the price-competitive process. The resulting bid-to-cover measure of approximately 3.36 is calculated from those two figures; it is not a separate measure of total government borrowing or the number of individual bidders.
At the October 8 auction, the ministry accepted the same ¥450.7 billion through competitive bidding, but received ¥1.7472 trillion in bids. That produced a ratio of about 3.88, higher than Tuesday’s result. The decline means fewer bids were submitted for each yen awarded through the competitive process, rather than proving that the sale failed or that investors broadly abandoned long-term Japanese bonds.
There is another useful comparison. At the November 2025 sale, competitive bids were ¥1.643 trillion against ¥525.8 billion accepted, a ratio of roughly 3.12. Tuesday’s 3.36 was higher than that year-earlier reading, although the two sales involved different issues and different amounts of debt. Together, the three auctions show why a single ratio is a limited basis for declaring demand either exceptionally strong or weak.
The finance ministry allotted another ¥148.8 billion in the first non-price-competitive channel reserved for JGB market special participants, bringing awards in those two channels to ¥599.5 billion. A subsequent second non-price-competitive auction recorded no additional awards. The total was close to the roughly ¥600 billion offering announced in advance, and the competitive bid figure should not be confused with that issuance amount.
Prices increased, but the yield remained above last year’s
Tuesday’s sale reopened the 30-year bond designated Issue No. 92, which carries an annual coupon of 4.2% and matures on September 20, 2056. Its issue date for this auction is November 11. The weighted-average accepted price was ¥104.90 per ¥100 of face value, while the lowest accepted price was ¥104.55, corresponding to a yield of 3.871%.
Because the bonds were allotted above face value, their yield at the average accepted price was lower than the fixed 4.2% coupon. The coupon specifies the contractual interest payment on the bond’s principal; the auction yield reflects what investors pay to receive those payments and the principal at maturity. For a bond with decades left to run, a change in price can produce a meaningful change in the yield available to a new buyer.
At the October auction of this same issue, the weighted-average accepted price was ¥101.21 and the corresponding yield was 4.109%. The November average price was ¥3.69 higher per ¥100 of face value, and the yield was 0.262 percentage points lower, equivalent to 26.2 basis points. That month-to-month comparison is particularly informative because the coupon and maturity date did not change between the two reopenings.
The longer comparison points in a different direction. November 2025’s 30-year auction cleared at an average yield of 3.166%, so the latest result was 68.1 basis points higher. Those were different bonds, with different coupons and remaining maturities, making this a broad comparison of the government’s long-term funding environment rather than a like-for-like price move in one security.
These figures are yields on bonds accepted at specific government auctions, not an intraday quotation for the entire 30-year government-bond market. They establish what the ministry accepted in each sale, but they do not by themselves establish the closing yield, an immediate price reaction after the result, or the motives of the investors who placed bids.
Reduced supply and central-bank purchases shape the backdrop
The government has already adjusted the amount of debt it brings to investors at the longest maturities. In its initial fiscal 2026 issuance plan, the Ministry of Finance called for reducing monthly issuance in the super-long-term sector, covering 20-, 30- and 40-year maturities, by ¥100 billion after discussions with market participants. Planned annual 30-year issuance under that comparison fell to ¥7.2 trillion from ¥8.7 trillion in the previous fiscal year’s supplementary-budget plan.
November’s announced offering of about ¥600 billion also compares with about ¥700 billion for the 30-year sale scheduled in November 2025. Smaller offerings can make it easier for investors to absorb new supply, although changes in demand and prevailing prices still determine auction results. The lower amount does not, on its own, explain why coverage changed or why Tuesday’s average yield differed from October’s.
The adjustment followed concerns raised in discussions with dealers. At a December 2025 meeting of JGB market special participants, some attendees argued for cutting issuance across super-long maturities, with particular emphasis on the 30-year sector. The ministry’s published account describes those views as comments from participants, not a unanimous judgment about future bond prices or a guarantee that smaller sales would attract stronger demand.
Japan’s central bank is also gradually reducing its purchases of government securities after years of unusually large bond-buying operations. In an October 15 speech, Bank of Japan Policy Board member Junko Koeda described a plan to lower monthly JGB purchases by about ¥200 billion each calendar quarter through March 2027 and then maintain purchases at around ¥2 trillion per month from April 2027. That schedule relates to the central bank’s broader operations, not to direct participation in Tuesday’s finance-ministry auction.
Less central-bank buying and reduced government issuance point in different directions for supply and demand in the secondary market, and their net effect cannot be read directly from one auction. Long-dated yields also reflect investors’ assessments of inflation, future interest rates and the risk of holding a fixed payment for decades. Higher yields affect the cost of newly issued or refinanced debt over time; they do not immediately change the coupons the government owes on bonds already outstanding.
The next scheduled test in Japan’s conventional long-term bond calendar is a 20-year JGB auction on November 18, following a five-year sale on November 12. Those results will provide another comparison across maturities, but Tuesday’s figures remain a record of one 30-year offering rather than a forecast for the next sale.
More from Investing
Latest News
View all news- U.S. Consumer Prices Rise 0.4% in October as Inflation Remains Elevated
- India’s Unemployment Rate Falls to 5.1% as Rural Job Market Improves
- U.S. Real Hourly Earnings Stall in October as Inflation Offsets Wage Gains
- Fed Governor Waller Backs December Rate Increase Despite Stable U.S. Labor Market
- U.S. Small-Business Confidence Holds Near Long-Term Average as Tax Concerns Rise