
Johnson & Johnson Raises 2026 Sales Outlook After $25.4 Billion Third-Quarter Revenue
The company raised its annual sales forecast as medicine revenue grew 7.7%, even as medical devices lagged and a proposed talc settlement sharply reduced reported profit.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy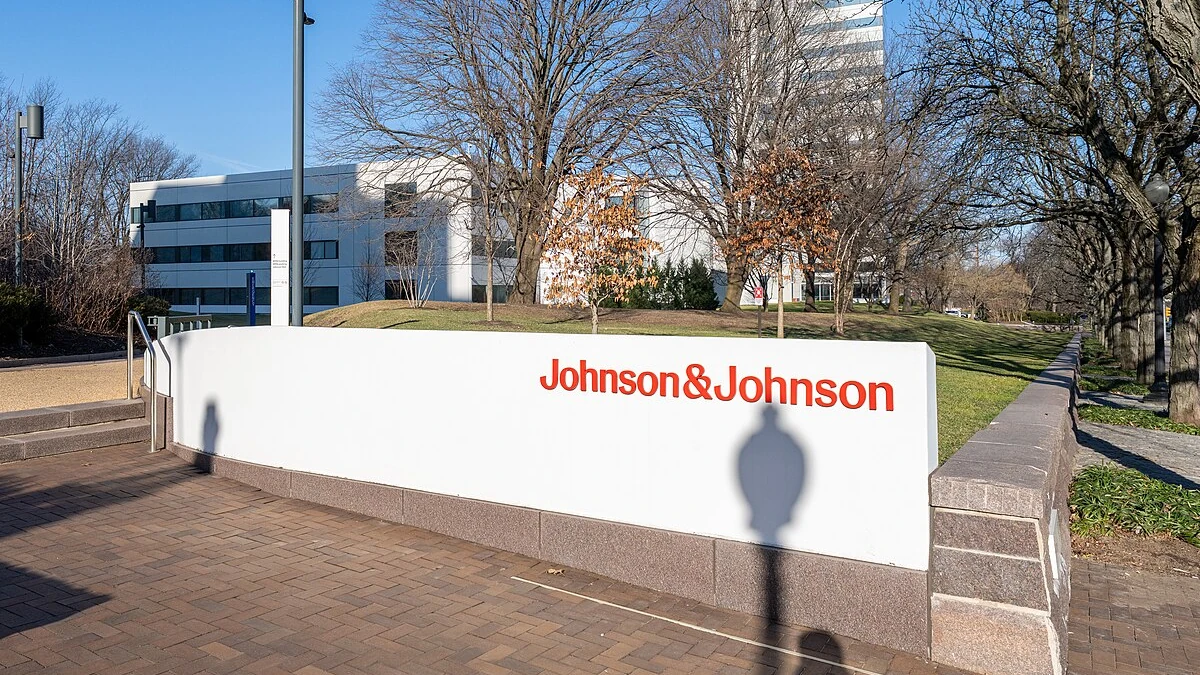
Johnson & Johnson raised its 2026 sales outlook on Tuesday after third-quarter revenue rose 5.9% to $25.4 billion, with stronger demand for its prescription medicines compensating for a much slower increase in medical-device sales. The company also increased its full-year adjusted earnings forecast, although profit for the quarter was sharply reduced by special charges.
The new reported-sales forecast of $101.0 billion to $101.4 billion puts the midpoint at $101.2 billion, up $100 million from the midpoint of July’s guidance. If achieved, it would mark the first time Johnson & Johnson has generated more than $100 billion in annual revenue. The upper end of the range has not changed, making this a relatively modest upgrade rather than a broad reset of expectations.
In its third-quarter earnings release, the New Brunswick, New Jersey-based company reported revenue of $25.399 billion, compared with $23.993 billion a year earlier. Sales grew 6.0% on an operational basis, which excludes the effects of currency translation. The results also showed a growing gap between its Innovative Medicine and MedTech businesses, a distinction that matters when evaluating the higher annual forecast.
A higher sales floor and a narrower earnings forecast
The change to the annual revenue range is concentrated at the low end. Johnson & Johnson previously expected reported sales of $100.8 billion to $101.4 billion; it now expects at least $101.0 billion. The new midpoint implies 7.4% reported sales growth for the year, compared with 7.3% under the earlier estimate. Management raised its operational sales range to $100.5 billion to $100.9 billion from $100.3 billion to $100.9 billion.
These figures use different measurement bases. Reported sales include the effect of currency movements, while operational growth strips out currency translation. Adjusted operational growth also removes the net effect of acquisitions and divestitures. On that latter basis, the company now forecasts 6.4% to 6.8% growth, compared with its previous range of 6.2% to 6.8%. The distinctions are important because a higher dollar sales forecast need not represent an equal improvement in underlying demand.
Johnson & Johnson lifted its 2026 adjusted diluted earnings-per-share forecast to $11.05 to $11.15, up from $10.96 to $11.11. The midpoint rose six cents to $11.10. Those are non-GAAP projections that exclude certain expenses, including intangible-asset amortization and special items; they are not forecasts of earnings calculated under standard U.S. accounting rules.
The company said it cannot reasonably estimate forward-looking GAAP profit because the eventual financial effects of litigation, acquisition costs and other unusual items remain uncertain. For investors, that limits how directly the adjusted outlook can be compared with the exceptionally low reported earnings in the latest quarter. The guidance also depends on assumptions about exchange rates and business conditions for the remainder of 2026.
Geographically, the quarter was much stronger in the United States. Domestic revenue grew 9.1% to $14.96 billion, compared with a 1.5% increase to $10.44 billion internationally. Currency movements had only a small effect on the consolidated growth rate, so the regional difference largely reflects a difference in reported business performance rather than exchange-rate translation.
Medicine growth offsets a disappointing device quarter
Innovative Medicine, the larger of Johnson & Johnson’s two operating segments, generated $16.76 billion in quarterly sales, up 7.7% from a year earlier. MedTech brought in $8.64 billion, an increase of 2.5%. Medicine contributed about $1.19 billion of the company’s $1.41 billion year-over-year revenue gain, highlighting how much of the overall improvement came from its pharmaceutical portfolio.
Management pointed to cancer treatments, immunology medicines and newer neuroscience products as the major contributors. The immunology drug Tremfya recorded 68% sales growth during the quarter, according to the company’s prepared earnings-call remarks. Oncology revenue grew approximately 17%, while products including Darzalex, Carvykti and Tecvayli helped support the broader medicine business. Growing sales of Spravato and Caplyta also contributed.
The picture was not uniformly positive within pharmaceuticals. Johnson & Johnson said falling sales of Stelara created an approximately 690-basis-point drag on Innovative Medicine’s operational growth rate. The performance of newer medicines was therefore particularly important to maintaining the segment’s expansion despite pressure on established products. That gives the updated outlook a clearer operating basis than the consolidated sales increase alone would suggest.
Medical devices presented a different challenge. The $8.64 billion segment grew, but its pace lagged the rest of the company, and Chief Financial Officer Joe Wolk acknowledged that MedTech had fallen short of management’s expectations. He identified cardiovascular and surgery operations outside the United States as areas requiring improvement. International MedTech revenue was almost unchanged at $4.13 billion, rising only 0.1%, while U.S. MedTech sales increased 4.8%.
There were pockets of growth. Johnson & Johnson cited its electrophysiology and Shockwave cardiovascular products, contact lenses and orthopaedic trauma devices as contributors. But management also said physician selectivity continued to affect Abiomed’s heart-recovery business. Strong results in individual product lines have not yet produced the broad acceleration in MedTech that the company wants.
One of the device business’s longer-term bets is Ottava, the surgical robotic system that received U.S. Food and Drug Administration De Novo authorization in July. The company said it had signed its first commercial customer and was progressing its clinical-development program. Those milestones may support future device growth, but they do not change the slower sales result reported for the third quarter. Management expects the system’s revenue contribution to build over time.
Talc provision depresses profit as portfolio changes continue
The headline profit figures were substantially weaker than the sales figures. Johnson & Johnson reported net earnings of $210 million, down from $5.15 billion in the third quarter of 2025. Diluted earnings per share fell to nine cents from $2.12. The company linked the unusual result to special charges, including the proposed resolution of ovarian talc litigation, its acquisition of Firefly Bio and a research collaboration with Sail Biomedicines.
The litigation proposal is a material part of that explanation. Management said a $5.5 billion proposed resolution announced in July is reflected in its third-quarter GAAP results. The agreement remains conditional on express participation by at least 95% of the remaining ovarian claims. Johnson & Johnson said participation was trending toward that threshold, but the condition means the proposal should not be described as a fully completed settlement.
Even on an adjusted basis, quarterly profit fell. Adjusted diluted EPS was $2.59, compared with $2.80 a year earlier, a 7.5% decline. Adjusted net earnings decreased 6.8% to $6.34 billion. Those figures exclude specified special items and amortization costs, but they make clear that stronger revenue did not translate into higher adjusted earnings in the quarter. The raised full-year EPS outlook is a projection for all of 2026, not a statement that third-quarter earnings improved.
The company remains active in business development. It completed the $1 billion acquisition of Firefly Bio during the quarter, adding research capabilities in oncology, and entered into a collaboration with Sail Biomedicines on cell-therapy approaches to immune-mediated diseases. Wolk said the two investments are expected to reduce adjusted earnings per share by a combined $1.36 in 2027, an estimate that will become more relevant as investors evaluate next year’s earnings base.
Cash generation gives Johnson & Johnson some flexibility as it pursues those investments. The chief financial officer reported more than $6 billion in third-quarter free cash flow and reiterated an approximately $21 billion full-year free-cash-flow outlook. At quarter-end, the company held about $17 billion in cash and marketable securities against roughly $45 billion of debt, leaving net debt near $28 billion.
Management is also working toward separating DePuy Synthes, its orthopaedics business, by mid-2027. Wolk said a spinoff was emerging as the preferred option, although Johnson & Johnson was still assessing the available structures. The separation is therefore planned rather than completed, and its final form is not yet settled.
The company has scheduled an Enterprise Business Review for December 8, 2026, when it expects to provide more detail on its 2027 outlook and the growth assumptions behind its longer-term plans. That update should also provide another opportunity to assess whether MedTech is beginning to close the performance gap with Innovative Medicine.
More from Investing
Latest News
View all news- Fed’s Waller Says Higher Treasury Yields Reflect Strong Growth More Than Inflation Expectations
- U.S. Small-Business Optimism Falls to 97.9 as Uncertainty and Hiring Concerns Persist
- U.S. Existing-Home Sales Rise 1.5% in September Despite High Mortgage Rates
- IMF Raises Global Growth Forecast to 3.1% as AI Investment Supports the U.S. Outlook
- FTC Seeks Contempt Sanctions Against Martin Shkreli Over Alleged Biotech Stock Trading
