
JPMorgan Reports $15.3 Billion Third-Quarter Profit as Revenue Hits $50.2 Billion
Equities trading jumped 49% and lending balances grew, although a $658 million securities loss and rising expenses weighed on the quarter.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy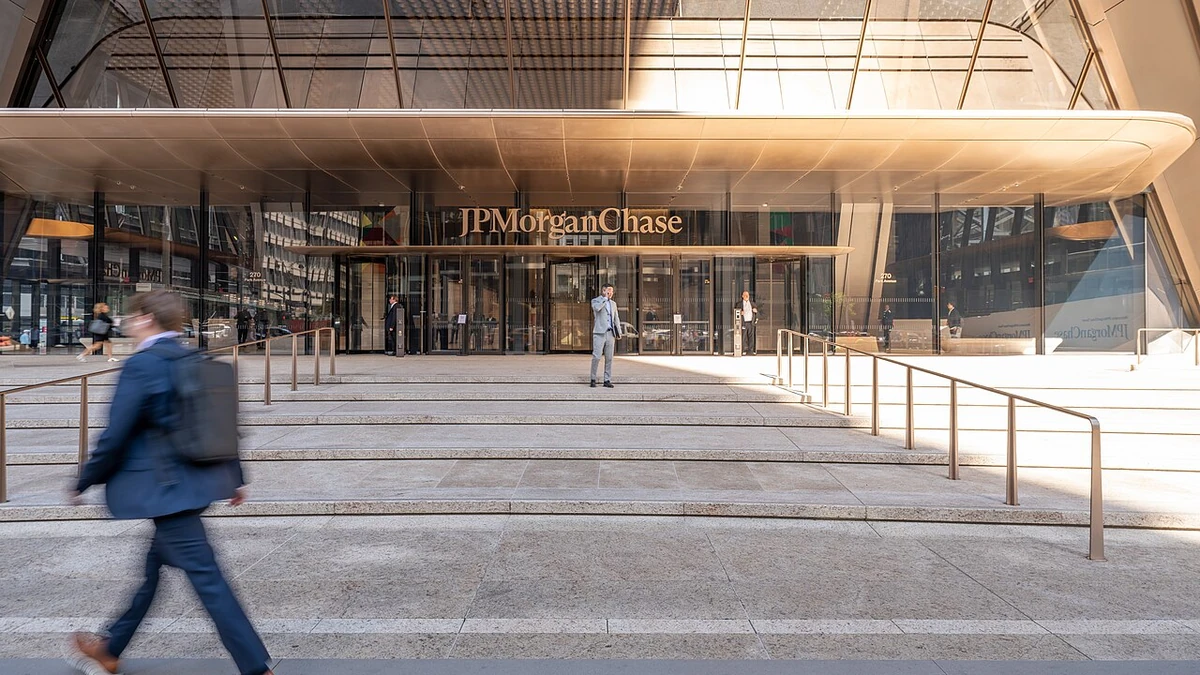
JPMorgan Chase reported a $15.3 billion profit for the third quarter of 2026, up 6% from a year earlier, as reported revenue rose 8% to $50.2 billion. The bank earned $5.57 per diluted share, compared with $5.07 in the same period last year, but a loss on investment securities reduced the amount that reached its bottom line.
The results showed continued growth in lending, deposits and several fee-generating businesses. Equity trading was particularly strong, and consumer banking benefited from higher credit card balances. Those gains came alongside higher operating costs and a less even performance across investment banking and trading than the headline revenue increase might suggest.
There is also an important distinction in the revenue figures. JPMorgan reported $50.17 billion under U.S. accounting rules, rounded to $50.2 billion in its earnings summary. Its separate managed revenue figure was $50.91 billion, or $50.9 billion, reflecting adjustments designed to put taxable and certain tax-advantaged income on a comparable basis. The two figures should not be treated as interchangeable.
In its third-quarter earnings release filed with the Securities and Exchange Commission on October 13, JPMorgan reported net income of $15.305 billion, compared with $14.393 billion a year earlier. Profit was considerably lower than the $21.155 billion earned in the second quarter, when the bank also recorded more revenue. Management said client activity in markets and investment banking had moderated during the latest quarter, even though both remained ahead of their year-earlier levels.
Securities losses reduced earnings, while operating costs climbed
A $658 million net loss on investment securities was one of the main qualifications to the quarter’s profit figure. JPMorgan said the loss had an after-tax effect of $498 million and reduced diluted earnings by 18 cents a share. Excluding that significant item, net income would have been $15.8 billion and earnings $5.75 a share. Those adjusted figures offer a view of performance without the securities loss, but the $15.3 billion profit and $5.57 per share remain the reported results.
The loss was recorded in the bank’s Corporate business, which posted a $455 million net loss against an $825 million profit in the year-earlier quarter. Corporate revenue fell sharply as securities results reversed from a $105 million gain a year earlier to the $658 million loss this quarter. This helps explain why the firm’s overall profit growth was more restrained than the gains reported by several of its operating divisions.
Expenses also outpaced revenue growth. Firmwide noninterest expense rose 12% to $27.3 billion, compared with an 8% rise in reported revenue. The bank cited higher compensation, including pay tied to revenue and additional front-office staff, together with brokerage, marketing and technology costs. Its reported overhead ratio was 54%, making the cost of generating additional business an important part of the earnings picture.
Net interest income, measured on the bank’s managed basis, rose 13% to $27.1 billion. Excluding Markets, it reached $24.7 billion, up 6%, helped by larger deposit, credit card and wholesale loan balances. Those gains were partly offset by lower interest rates. The distinction matters because loan and deposit growth can support revenue even when changing rates do not provide the same margin benefit across every part of the bank.
Equities trading surged as investment banking lost some momentum
The Commercial & Investment Bank generated $22.7 billion in revenue, a 14% increase from a year earlier, and $8.2 billion in net income, up 20%. Markets revenue was $10.3 billion, 15% higher than a year ago. Underneath that increase, the two major trading businesses moved in opposite directions: equities revenue jumped 49% to $5.0 billion, while fixed-income markets revenue slipped 4% to $5.4 billion.
JPMorgan attributed the equities performance to strength across products, notably prime services and derivatives. In fixed income, lower revenue in commodities, rates, credit and public finance was largely balanced by stronger currencies and emerging-markets activity. The divergence shows why a broad markets growth number can conceal markedly different trading conditions between asset classes.
Investment banking fees rose 14% from a year earlier to $3.0 billion, largely because of higher advisory fees. Yet those fees were 8% below the second quarter, illustrating the slower pace of activity as the quarter progressed. Revenue for the broader Commercial & Investment Bank was also down 9% sequentially, despite its double-digit year-over-year growth. The annual improvement therefore came with a clear slowdown from the second quarter.
The division’s Banking & Payments revenue increased 16% to $11.0 billion, including $5.6 billion in payments revenue, up 14%. Higher deposit balances and payment-related fees helped support that business. The payments growth was one of the clearest sources of recurring fee income in a quarter when markets results varied considerably by asset class.
Consumer & Community Banking provided another substantial contribution. Its revenue climbed 9% to $21.2 billion, while net income rose 13% to $5.7 billion. Card Services & Auto revenue increased 15% to $8.3 billion, helped by higher card balances and interest income. Debit and credit card sales volume grew 10% from a year earlier, and the bank said it added more than 650,000 net new checking accounts during the quarter. Home lending was weaker, with revenue down 3% to $1.2 billion.
Credit costs eased, but the balance sheet remains central
The provision for credit losses fell to $2.7 billion from $3.4 billion a year earlier. Net charge-offs, reflecting loans the bank determined it could not collect after recoveries, were $2.2 billion, down from $2.6 billion. JPMorgan also added $539 million to its reserves, compared with an $810 million build in the prior-year period. Lower overall credit costs supported earnings, though the latest reserve addition shows the bank was still providing for potential losses.
Loan balances were also growing across the firm. Average loans across JPMorgan were up 10% from a year earlier, while average deposits increased 8%. Within Consumer & Community Banking, the card services net charge-off rate was 2.91%. That measure offers a more specific reading of card credit performance than the bankwide provision alone, which also includes wholesale exposures and changes in reserves.
Asset & Wealth Management added a different source of growth. Revenue rose 14% to $6.9 billion, with net income of $1.8 billion, up 11%. Assets under management reached $5.2 trillion, 13% above a year earlier, while total client assets rose 15% to $7.9 trillion. JPMorgan attributed the gains to continued inflows and higher market levels, alongside growth in fees and lending balances. Expenses in the division also rose 14%, partly reflecting compensation and expansion of private-banking adviser teams.
At quarter-end, the bank reported several measures of its capital position. The bank reported a standardized common equity Tier 1 capital ratio of 13.9% and a 20% return on tangible common equity for the quarter. It paid $4.4 billion in common dividends, equivalent to $1.65 a share, and made $664 million of net common-share repurchases. Chief Executive Jamie Dimon said repurchases were reduced as the firm prioritized opportunities to deploy capital in its businesses.
Dimon described U.S. economic activity as supported by business investment and consumer spending, but also cited large fiscal deficits, persistent inflation, elevated asset prices, rising rates and geopolitical conditions as sources of risk. For JPMorgan, the immediate financial question is whether growth in loans, payments and client assets can continue to offset uneven trading activity and a higher expense base. The bank has scheduled its fourth-quarter earnings conference call for January 14, 2027.
More from Investing
Latest News
View all news- Fed’s Waller Says Higher Treasury Yields Reflect Strong Growth More Than Inflation Expectations
- U.S. Small-Business Optimism Falls to 97.9 as Uncertainty and Hiring Concerns Persist
- U.S. Existing-Home Sales Rise 1.5% in September Despite High Mortgage Rates
- IMF Raises Global Growth Forecast to 3.1% as AI Investment Supports the U.S. Outlook
- FTC Seeks Contempt Sanctions Against Martin Shkreli Over Alleged Biotech Stock Trading
