
ManpowerGroup Q3 Earnings Rise as Revenue Reaches $4.8 Billion
Net income nearly doubled to $34.1 million as lower administrative costs lifted profit, even as gross margin narrowed and regional demand remained uneven.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy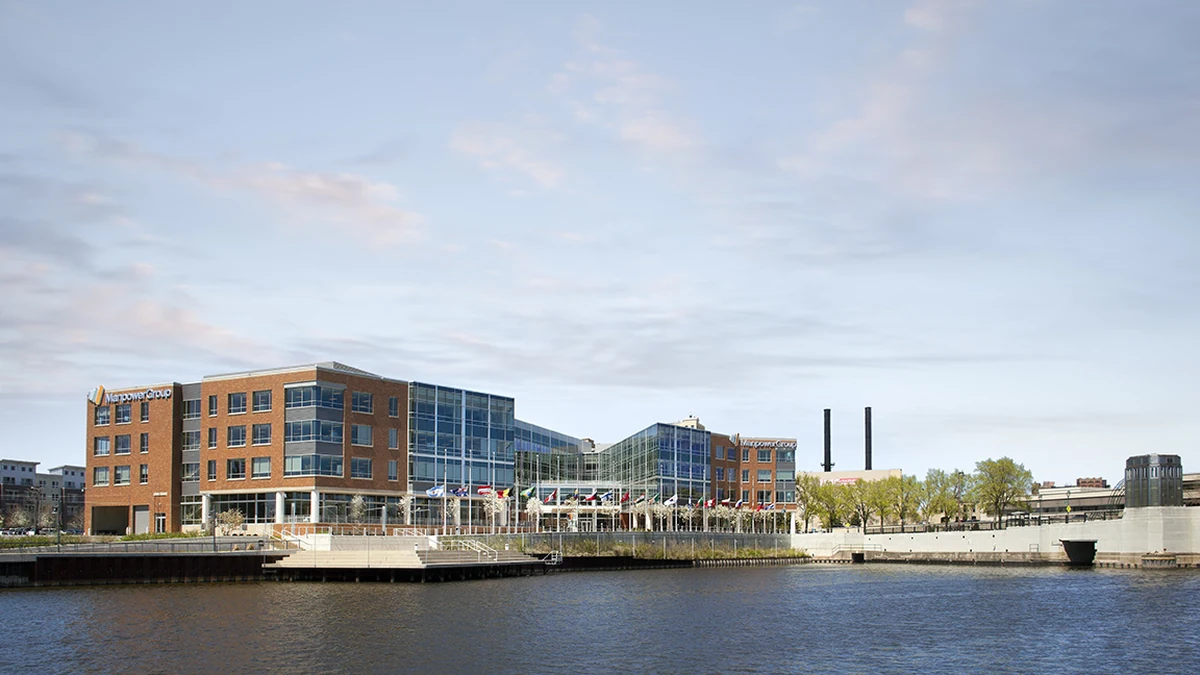
ManpowerGroup reported a sharp rise in third-quarter earnings on Thursday as revenue grew to $4.84 billion and lower administrative spending helped offset pressure on profitability from its staffing services. The Milwaukee-based workforce company earned $34.1 million in the three months ended September 30, 2026, compared with $18.0 million a year earlier.
Diluted earnings per share rose to $0.71 from $0.38, while revenue increased 4.4% from $4.63 billion. Operating profit climbed 23.7% to $82.3 million. The improvement was substantial, but the results also showed that higher sales did not automatically produce higher gross profit, an important distinction for a business where staffing costs make up most of the revenue base.
On a constant-currency basis, sales increased 5.2%, reflecting the effect of exchange rates on ManpowerGroup’s international operations. The company put organic constant-currency growth, which also adjusts for changes in the business portfolio, at 6%. U.S. staffing demand strengthened, although performance remained uneven across brands and regions.
Profit improves even as gross margin narrows
The figures in ManpowerGroup’s third-quarter earnings release show why the increase in net income needs to be read alongside its operating costs. Gross profit edged down to $767.3 million from $768.9 million despite the rise in revenue. Costs of services increased 5.4%, faster than the 4.4% growth in sales, leaving a smaller share of revenue after direct service costs.
Gross margin was 15.9%, down about 70 basis points from a year earlier. For a staffing company, that measure reflects the amount retained from revenue after the direct cost of providing workers and other services. The decline suggests that the revenue recovery has not yet translated into broad improvement in the economics of each dollar of business.
A more favorable trend appeared further down the income statement. Selling and administrative expenses fell to $685.0 million from $702.3 million, a reduction of $17.3 million, or 2.5%. That decrease more than covered the $1.6 million decline in gross profit, helping lift operating earnings to $82.3 million from $66.6 million.
Reported net earnings also included charges related to restructuring, strategic transformation work, an adjustment tied to the sale of the U.S. Jefferson Wells business, and a small noncash currency translation loss in Argentina. Together, the items reduced third-quarter diluted earnings per share by $0.30, according to ManpowerGroup. Excluding them, the company reported adjusted EPS of $1.01 and said that figure was 24% higher in constant currency on a comparable adjusted basis. The $1.01 adjusted figure should not be compared directly with last year’s $0.38 reported EPS because the prior-year quarter also contained charges excluded from the adjusted comparison.
The nine-month results provide another view of the recovery. Revenue for January through September reached $14.21 billion, up 7.3% from the comparable 2025 period. ManpowerGroup posted net earnings of $90.1 million for those nine months, against a $43.5 million net loss a year earlier. Both periods included special items, so the swing in reported earnings is not, on its own, a measure of recurring profitability.
U.S. demand strengthens, with different trends across Europe
The Americas produced the quarter’s strongest regional revenue growth. Sales reached $1.25 billion, an increase of 13.5% on a reported basis and 11.5% in constant currency. Within that total, U.S. revenue was $728.8 million, up 5.5% from $690.8 million a year earlier. Revenue in the rest of the Americas rose 27.0% as reported, making the broader region a larger contributor to group growth.
Regional operating unit profit in the Americas rose to $47.4 million from $37.9 million. In the United States alone, operating unit profit increased to $24.3 million from $20.6 million. Management described strength in the Manpower staffing brand, especially in its home market, as a principal driver of the quarter’s top-line improvement.
Southern Europe remained the company’s largest operating region, generating $2.23 billion of revenue, nearly half of the group’s total. Its sales rose only 1.0% as reported. France, an important market within the region, recorded a 3.5% revenue decline to $1.13 billion, while Italy grew 4.5% to $483.1 million. Southern Europe’s operating unit profit slipped to $64.6 million from $65.6 million.
The picture was different in Northern Europe. Revenue increased 5.4% to $860.6 million and operating unit results improved to a $7.5 million profit from a $14.9 million loss in the year-earlier quarter. That swing is one of the clearer signs of progress outside the Americas, although profitability in the region remains modest relative to its sales.
In the Asia-Pacific and Middle East reporting region, identified by the company as APME, sales declined 1.1% in reported dollars to $514.9 million but increased 4.3% in constant currency. The contrast illustrates why headline dollar growth alone can give an incomplete picture of an international staffing company’s underlying demand.
Manpower leads growth as Experis steadies
The regional figures sit alongside different trends in the company’s main service brands. In its quarterly results presentation filed with the SEC, ManpowerGroup said the Manpower brand generated 7% organic constant-currency revenue growth, following 8% growth in the second quarter. That performance points to continuing momentum in its core staffing operation rather than a recovery confined to one geography.
Experis, which focuses on technology and specialist talent, was flat on the same organic constant-currency measure after a 2% decline in the previous quarter. ManpowerGroup also said its U.S. Experis business returned to growth during the third quarter. Those indications are an improvement in direction, though flat worldwide Experis revenue does not yet establish a broad-based acceleration in specialist hiring.
Talent Solutions recorded 1% organic constant-currency revenue growth, compared with a flat result in the second quarter. The company attributed improvement to recruitment process outsourcing and managed service provider activities, partly offset by lower outplacement activity in Right Management. The brands serve different kinds of employment needs, so their growth rates are not interchangeable measures of the wider job market.
Management has also been working to lower its structural cost base. The drop in selling and administrative expenses shows that some of those savings are already visible in reported operating results. But a narrower gross margin means the company still needs either better pricing, a more profitable service mix or continued cost discipline to convert additional revenue into stronger operating performance. Those are potential paths, not outcomes guaranteed by the quarter’s figures.
Fourth-quarter guidance comes with a CEO handover
For the fourth quarter, ManpowerGroup forecast diluted earnings per share of $1.03 to $1.13, assuming an effective tax rate of 44%. Its results presentation projected revenue growth of 3% to 7% both as reported and in constant currency, with organic constant-currency growth of 4% to 8%. The company’s outlook excludes expected restructuring and strategic transformation program costs from the underlying earnings guidance.
The guidance also calls for a fourth-quarter gross margin between 15.8% and 16.0%, close to the third-quarter level. That forecast offers a caution against reading the rise in net income as evidence that pricing or margins have already recovered across the business. Foreign-exchange movements, client hiring decisions and the pace of economic activity remain relevant uncertainties around the projection.
The earnings announcement coincided with a significant management change. ManpowerGroup separately said Becky Frankiewicz, its president and chief strategy officer, will become chief executive officer on January 1, 2027. Jonas Prising, CEO since 2014, will move to the executive chair role. Frankiewicz joined ManpowerGroup in 2017 and has since held senior commercial and strategy positions.
The transition gives incoming leadership a business showing improving staffing demand and better expense control, but not uniform growth across its markets. The scheduled January 1 handover will follow the company’s final quarter under Prising as CEO, with the fourth-quarter guidance providing a measurable benchmark for performance before the change.
More News
Latest News
View all news- Prologis Q3 Core FFO Rises to $1.60 a Share as Leasing Demand Holds Firm
- U.S. Natural Gas Storage Rises 67 Bcf to 3,567 Bcf, EIA Reports
- U.S. Business Inventories Increase 0.4% in August as Sales Climb 1.1%
- Philadelphia Fed Manufacturing Index Falls to 20.9 as Factory Growth Moderates
- New York Manufacturing Index Jumps to 25.5, Highest Since December 2021
